
What is Stanley’s SWOT analysis? Stanley 1913’s strengths sit in an installed base of more than 10 million Quenchers, a lifetime-warranted steel body, an owned factory network and a parent company built around supply chain. Its weaknesses and threats sit in the components that lifetime warranty explicitly excludes: lids, seals and straws. Owala took the number-one US steel bottle position with a better lid. Stanley’s owned Chinese capacity cannot be re-sourced away from tariffs the way a contract can. And a brand built on images has little for an AI search engine to read.
Stanley SWOT Analysis at a Glance
What it is: A strategic breakdown of the internal Strengths and Weaknesses, plus the external Opportunities and Threats, facing Stanley 1913, the drinkware brand operated by PMI WW Brands and owned by the privately held HAVI Group.
The core tension: Stanley sells an object engineered never to need replacing, to a US market that already owns one. Growth has to come from somewhere other than repeat purchase of the hero product.
Read this if: You want the structural version of the Stanley story rather than the viral one. The marketing side of the argument lives in our Stanley marketing strategy breakdown, which covers the scarcity flywheel and the 2026 rebuild. This piece covers the balance sheet underneath it.
Contents
- What the SWOT is measuring: who actually owns Stanley
- Strengths
- Weaknesses
- Opportunities
- Threats
- The Stanley SWOT matrix
- What the four quadrants add up to
- Frequently asked questions
- The Business Model Analyst Take
What the SWOT is measuring: who actually owns Stanley
Most Stanley write-ups treat the company as a brand. For a SWOT, the corporate structure decides half the answer.
The legal entity is PMI WW Brands, LLC, the Seattle business formerly known as Pacific Market International. PMI acquired the Stanley and Aladdin retail and branding rights in 2002 and moved production to China that same year. Since 1 September 2021, PMI has been a business unit of The HAVI Group, LP, a privately held supply chain, sourcing and consumer engagement firm founded in 1974 that employs more than 10,000 people across 100-plus countries. HAVI bought PMI from the private equity firm Endeavour Capital. Neither side disclosed the price.
The date matters more than the price, because of where it lands on Stanley’s revenue curve.
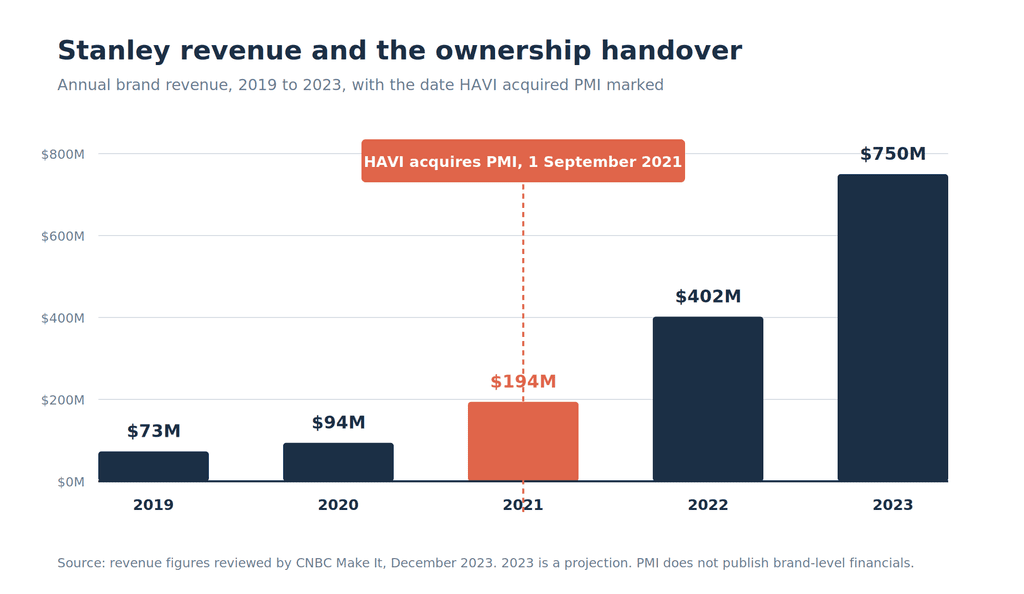
Endeavour sold on the third rung of a five-rung ladder. HAVI collected the next 3.9x in twenty-four months. That is the single most under-reported fact in the Stanley story, and it explains the shape of the company you are analyzing: Stanley’s owner is a logistics business that acquired a consumer brand, not a consumer brand holding company that acquired a factory.
You can see the same instinct in the asset base. PMI holds ownership in three manufacturing plants, one in China (PMI Joinease) and two in Brazil (Rio de Janeiro and Manaus). It runs offices in Seattle, San Francisco, Shanghai, Shenzhen, Amsterdam, Manila, Rio de Janeiro and Bentonville, Arkansas. Alongside Stanley it operates Aladdin, the Asia-Pacific brand Migo, and a private label business that manufactures store-brand containers for global retailers.
That last line is worth sitting with. Stanley’s parent manufactures the private label drinkware sold by some of the same retailers that stock Stanley.
Strengths
1. An installed base that keeps generating demand for itself
Stanley had sold more than 10 million Quenchers by the end of 2023. Two and a half years later the brand still holds roughly 30% of US direct-to-consumer spend on water bottles, according to Consumer Edge, with its strongest momentum among 25 to 54 year olds.
The traffic number is more surprising. Stanley1913.com pulled 6.6 million global desktop and mobile visits in July 2026, up 35.5% against July 2025, per Similarweb. A brand widely described as post-peak grew its owned audience by more than a third in a year.
2. Manufacturing it owns rather than rents
Yeti, Hydro Flask and most of the category buy production from contract factories. PMI holds equity in three of its plants and sits inside a parent whose core competence is moving physical goods. That combination let Stanley take revenue from $94 million to $750 million in three years without the fulfillment collapse that usually kills a viral consumer brand.
3. Color as a zero-tooling product roadmap
A new colorway needs no new engineering, no new supply chain and no new SKU architecture. Stanley has released the Quencher in more than 100 colors off one body. We covered the mechanics of this in the marketing strategy piece; for SWOT purposes the point is narrower. Stanley can manufacture perceived newness at close to zero marginal cost, which is a structural margin advantage over any rival that has to tool a new product to stay interesting.
4. International infrastructure that is already standing
Stanley operates localized storefronts across four Americas markets (US, Canada, Brazil, Argentina), seven European countries and nine Asia-Pacific regions. Global president Matt Navarro has said international has been the brand’s largest growth area for the last twelve to eighteen months, with the UK, Germany, Spain, France, Japan, China, Korea, Australia and New Zealand as the active build.
Compare that with Yeti, which expects to be live in eleven international markets by the end of 2026, up from four the year before. The two companies count markets differently, so this is not a clean scoreboard. The direction of travel is still clear: Stanley’s international plumbing was installed years ago, and Yeti is laying pipe now.
5. A lifetime warranty as a trust instrument
Stanley warrants its stainless steel vacuum products for the life of the product against defects in material and workmanship, including degradation of thermal performance. In a category where the 2024 lead-pellet story introduced doubt, an unlimited-duration promise is a cheap and durable credibility asset.
Weaknesses
1. The warranty covers the part that never breaks
Read Stanley’s own warranty language. Coverage on drinkware and food containers lasts the life of the product, “not including lids, seals and straws.” Soft goods, meaning the bags and totes Stanley launched in 2024 and expanded through the 2026 Vitalize Collection, carry a three-year limited warranty. The company’s newsroom boilerplate now describes the promise as a “limited lifetime warranty.”
Stack those three facts and the picture inverts. Stanley guarantees the double-walled steel cylinder, which is the component that does not fail. It excludes the lid, the seal and the straw, which are the components that crack, leak, stain and get lost. And it caps the newest growth category at three years.
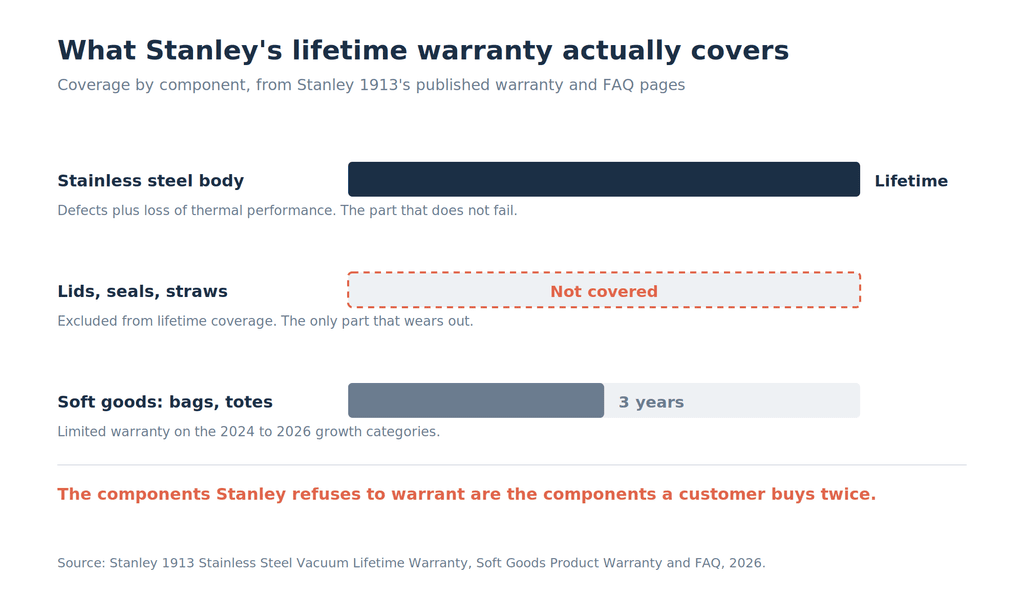
The excluded parts are the only consumable Stanley sells.
2. No replacement cycle on the hero product
A Quencher that survives a car fire, which is the brand’s most famous piece of earned media, is a Quencher its owner never has to buy again. Ten million-plus units of installed base is Stanley’s largest single competitor. The company solved this once by turning the cup into a collectible, so the same household bought six. That mechanism depends on the color drop staying culturally interesting, and it has no floor underneath it.
3. Owned Chinese capacity cannot be re-sourced
Here the strength runs backward. Yeti spent 2025 dismantling its Chinese manufacturing base and told investors it expected less than 5% of total cost of goods sold to carry US tariff exposure on China-sourced goods by year end, using a network across Vietnam, the Philippines, Thailand, Mexico, Cambodia, Indonesia, Malaysia and the US.
Yeti could do that because it rents its capacity. Stanley’s parent owns a plant in China and has manufactured there since 2002. You can switch a contract manufacturer in a quarter. Switching out of a factory you hold equity in means writing off the asset, and PMI’s Brazilian plants serve South America rather than the US.
Navarro’s public answer is that PMI has “an incredible team building a flexible, agile, resilient supply chain all around the world” and that tariffs have been tricky. He may be right. Nothing in the public record shows the mix.
4. Brand equity encoded in pictures
Stanley’s chief brand officer Kate Ridley has been candid about this. The brand’s occasion marketing around Mother’s Day, Teacher Appreciation Week and Nurse Appreciation was, in her words, heavy on imagery and light on copy explaining the use, the occasion and why the product made a good gift. Human buyers infer that from a photograph. Language models cannot.
Every dollar of equity Stanley built between 2020 and 2024 went into a format that does not survive translation into text.
5. No disclosure, therefore no external discipline
PMI publishes nothing. There is no gross margin, no channel split, no inventory figure, no unit economics. Private ownership let Stanley under-supply a sold-out product and call it strategy. It also means nobody outside the company can see whether the 2026 rebuild is working until the third-party trackers catch up.
Opportunities
1. Sell the parts the warranty excludes
Stanley has already drawn the line between the durable asset and the consumable. Lids, seals and straws sit outside lifetime coverage, which makes them the natural repeat-purchase line for a brand that has none. Replacement lids, upgraded straw systems and seal kits convert a warranty exclusion into a revenue stream, and the customer is already in the door.
2. Categories with cheaper warranty liability
The soft goods push carries a three-year cap rather than a lifetime promise. Backpacks, totes and gym bags wear out, get replaced, and cost less to stand behind. Stanley’s February 2026 Vitalize Collection, the Clutch Bottle and the Flowstate Spring Bottle all point this direction. The company reported a 22% first-week sell-through on the Flowstate Spring Bottle with retail partners and 50% in DTC.
3. Agentic commerce, from a standing start
Stanley has been testing Shopify and Google’s Universal Commerce Protocol to push its catalog directly into chat conversations, and working with Yotpo’s Discovery product to measure how often the brand shows up in LLM answers. With 42% of US adults now using AI chatbots to search for information according to Pew Research Center, structured product data is turning into a distribution channel.
Stanley starts behind on content and ahead on catalog depth. Fixing the copy is a writing problem, and writing problems are solvable in a quarter.
4. The male customer at a higher price point
Navarro has named men as a recent target, pursued through football clubs, golf and the 2026 World Cup calendar. Stanley served this customer for a century before 2020, at a fraction of today’s average selling price. Reacquiring him at $45 rather than $25 is the highest-margin version of a customer win available to the company.
5. Brazil as a non-China footprint
PMI’s two Brazilian plants exist to serve South America, and Stanley is a mainstream brand there in a way it never was in Europe. In a decade where US trade policy keeps rewriting itself, holding hard assets outside China gives PMI an option that pure-import rivals have to build from scratch.
Threats
1. Tariffs land on the part of Stanley that cannot move
On 2 April 2026 the White House restructured Section 232 metal tariffs. Effective 6 April, duties apply to the full customs value of covered steel, aluminum and copper articles and their derivatives, rather than to the value of the metal content alone. Products made almost entirely of non-US-origin steel face 50%; derivative articles substantially made of the metal face a flat 25%.
Stanley does not report what it pays. Yeti does, and Yeti is the closest audited proxy in the category:
| Period | Yeti tariff impact |
|---|---|
| Full year 2025 | 230 bps of gross margin, $0.35 of adjusted EPS |
| Q4 2025 | $0.15 of adjusted EPS |
| Q1 2026 | 280 bps of gross margin |
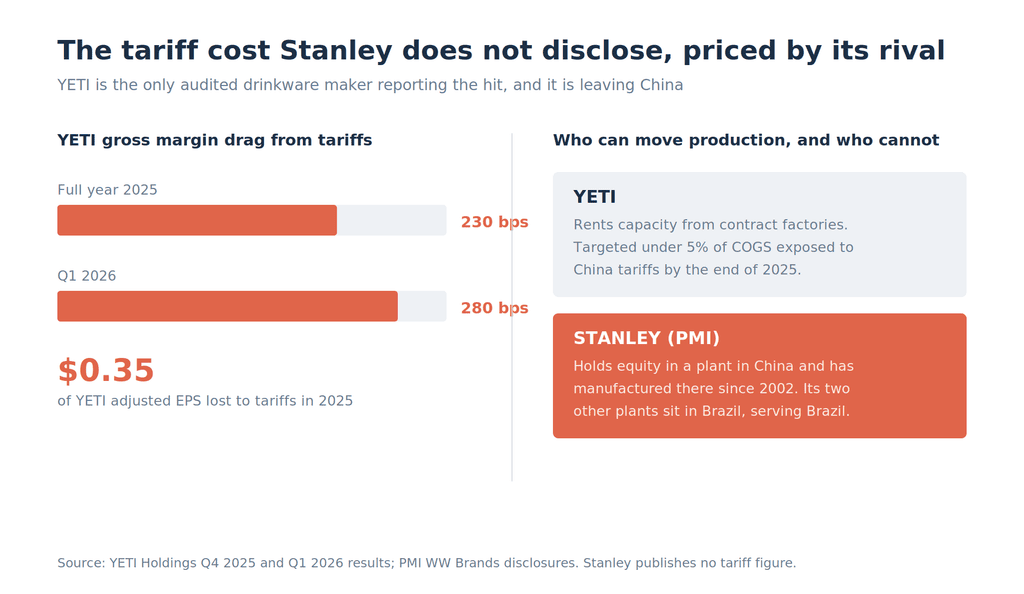
Yeti absorbed that while exiting China. Stanley is absorbing something similar while owning a plant there.
2. Owala won on the component Stanley does not warrant
Owala became America’s best-selling stainless steel water bottle in 2023 on the strength of its FreeSip lid, a two-in-one spout that lets you sip through a straw or drink from a wide mouth. Stanley lost the volume crown on the exact part it excludes from lifetime coverage.
That is not a coincidence so much as a revealed priority. Stanley engineered and guaranteed the vessel. A competitor engineered the interface.
3. AI search rewards features you can describe in a sentence
Owala’s advantage compresses into one line of text a model can extract, quote and recommend. Stanley’s advantage between 2020 and 2024 was a photograph of the right color next to the right outfit.
As buyers shift discovery toward chat interfaces, a functional differentiator outperforms a cultural one, because only one of the two is machine-readable. Stanley’s own brand leadership has identified the gap. Closing it means rebuilding four years of visual equity as prose, in a channel where competitors have a head start by accident of product design.
4. A category that stopped compounding
Stanley’s US direct-to-consumer spend grew more than 300% in 2022 and fell about 20% in 2025, per Consumer Edge. 2026 has been choppy: Q1 up year over year, Q2 down. Meanwhile Yeti’s drinkware segment posted growth in three consecutive quarters through Q2 2026, ending at 2% growth on $241 million.
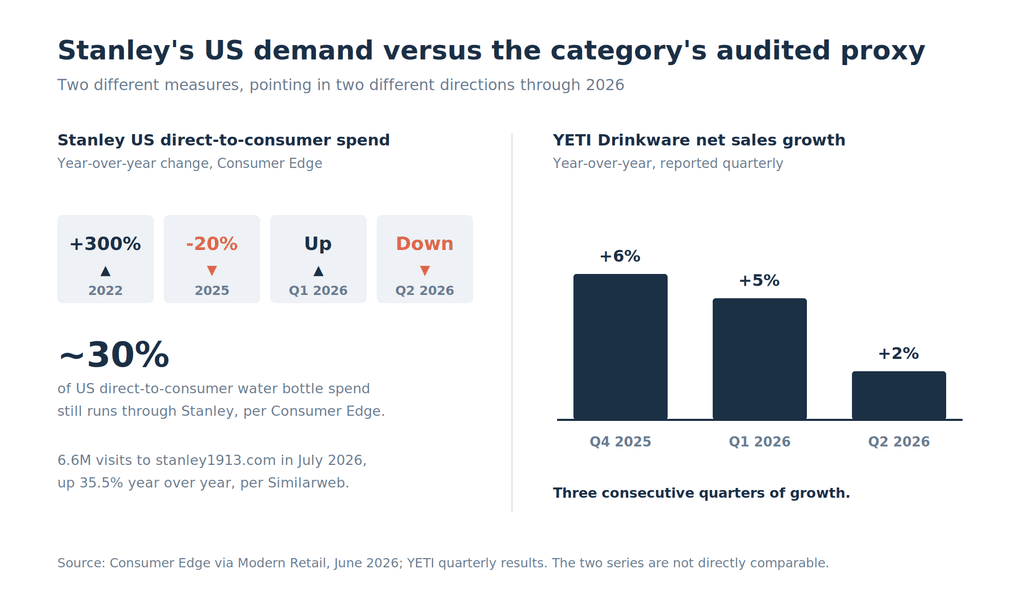
If the audited competitor’s drinkware is recovering while Stanley’s US DTC swings, the category is not the whole story. Some of it is share.
5. Discretionary exposure and the residue of the lead story
Stanley sells a $45 cup to people who could use a $6 one. Navarro has acknowledged that some of the brand’s customers are watching their budgets. Separately, the federal class action over the lead-containing vacuum-sealing pellet was dismissed in April 2026, with the court finding that the presence of lead alone, absent a plausible safety risk, was not material to consumers. Stanley won. The disclosure remains on its own FAQ page, and competitors keep marketing against it.
The Stanley SWOT matrix
| Strengths | Weaknesses |
|---|---|
| 10M+ Quenchers sold; ~30% of US DTC water bottle spend | Lifetime warranty excludes lids, seals and straws |
| Site traffic 6.6M visits in July 2026, +35.5% YoY | No replacement cycle on the hero product |
| Equity in three plants; HAVI supply chain parent | Owned China capacity cannot be re-sourced |
| 100+ colorways off one body, near-zero tooling cost | Brand equity stored as images, not text |
| Roughly 20 localized storefronts worldwide | Zero public financial disclosure |
| Opportunities | Threats |
|---|---|
| Monetize the warranty-excluded consumables | Full-customs-value Section 232 duties from 6 April 2026 |
| Soft goods at a 3-year warranty liability | Owala leads US steel bottles on lid design |
| Shopify and Google UCP catalog into chat | AI discovery favors describable features |
| Reacquire the male customer at 2026 pricing | US DTC down ~20% in 2025, choppy through 2026 |
| Brazilian plants as non-China capacity | Discretionary spend pressure, residual lead coverage |
What the four quadrants add up to
Three of Stanley’s five most serious problems converge on the same few inches of plastic.
The lifetime warranty stops at the lid. The competitor that took the volume crown took it with a lid. And the feature a language model can describe to a shopper is a lid, not a color.
Stanley spent a century perfecting the part of the product that customers never think about, and its entire 2020s success came from making them think about the part they can see. The company now needs a third act built on the part they touch.
Read the 2026 moves through that lens and they stop looking like a scattergun. Backpacks and shaker bottles carry three-year warranties instead of lifetime ones. Sport sponsorships buy a customer who was never in the Quencher’s installed base. International sells the same cup to households that do not own one yet. Every one of those plays changes the denominator rather than fixing the frequency.
Fixing the frequency would mean building a business on the lid, the seal and the straw. Stanley already knows exactly which parts those are, because it wrote them out of the warranty.
Frequently asked questions
Who owns Stanley in 2026? Stanley 1913 is operated by PMI WW Brands, LLC of Seattle, formerly Pacific Market International, which has been a business unit of the privately held HAVI Group, LP since 1 September 2021. PMI acquired the Stanley brand rights in 2002 and also owns Aladdin and Migo.
What are Stanley’s biggest strengths? An installed base of more than 10 million Quenchers, roughly 30% of US direct-to-consumer water bottle spend, equity in three manufacturing plants, a parent company built around supply chain, and a color-drop model that produces new product at almost no tooling cost.
What are Stanley’s biggest weaknesses? A product durable enough to have no replacement cycle, a lifetime warranty that excludes the only components that wear out, manufacturing capacity in China that it owns rather than rents, and brand equity built in images that AI search engines cannot read.
Is Stanley’s lifetime warranty really unlimited? Not on the whole product. Stanley covers stainless steel vacuum drinkware and food containers for the life of the product against defects and thermal degradation, but excludes lids, seals and straws. Soft goods such as bags and totes carry a three-year limited warranty.
Who is Stanley’s biggest competitor? Owala, which overtook Stanley as America’s best-selling stainless steel water bottle in 2023 on the strength of its FreeSip lid. Yeti, Hydro Flask and Simple Modern compete directly, and Yeti is the only one that publishes audited numbers. Our Yeti competitors breakdown maps the field.
Are Stanley cups still safe after the lead story? Stanley uses a lead-containing pellet to seal the vacuum insulation at the base of its products, covered by a stainless steel layer. The company states no lead touches the drink or the user in normal use, and a federal court dismissed the related consumer class action in April 2026.
The Business Model Analyst Take
Stanley’s SWOT is unusual because the strengths and the weaknesses are the same object viewed from two ends.
As a manufactured good, the Quencher is close to perfect. Double-walled steel, a lifetime promise, more than a hundred colors off one tool, produced in plants the parent company holds equity in. As a purchase, it is close to terminal. It does not break, it does not run out, and after four years of saturation coverage most of the American households that want one have one.
Everything Stanley has done since 2025 accepts that. Football clubs, Messi, the Middle East, backpacks and shaker bottles are all ways of finding new bodies rather than new occasions. That is the right response to a saturated installed base, and it is expensive. It is also the response that puts a supply-chain parent in exactly the position it understands: more units, more markets, more SKUs.
The move nobody at Stanley has made yet is the cheaper one sitting in its own warranty document. The company drew a bright line between the part it guarantees forever and the parts it will not guarantee at all. That line is a product roadmap. The lid is where the competitive loss happened, where the repeat purchase lives, and where a machine reading a product page can find something worth quoting.
Whether Stanley gets there depends on a question the private ownership makes unanswerable from outside. HAVI bought a supply chain business and got a cultural phenomenon attached to it. Nobody knows which one it thinks it owns.