
What is Stanley’s marketing strategy? Stanley 1913’s marketing strategy is built on manufactured scarcity applied to a legacy product. The brand reassigned a century-old utility item to an audience nobody in the category was serving, made color the primary product variable, released limited drops that sold out on purpose, and let the resulting fan content and press coverage do the paid media work for free. Since 2025, with the hydration category saturated and US sales cooling, Stanley has been rebuilding that strategy around sports sponsorships, male customers, non-drinkware categories, and international markets.
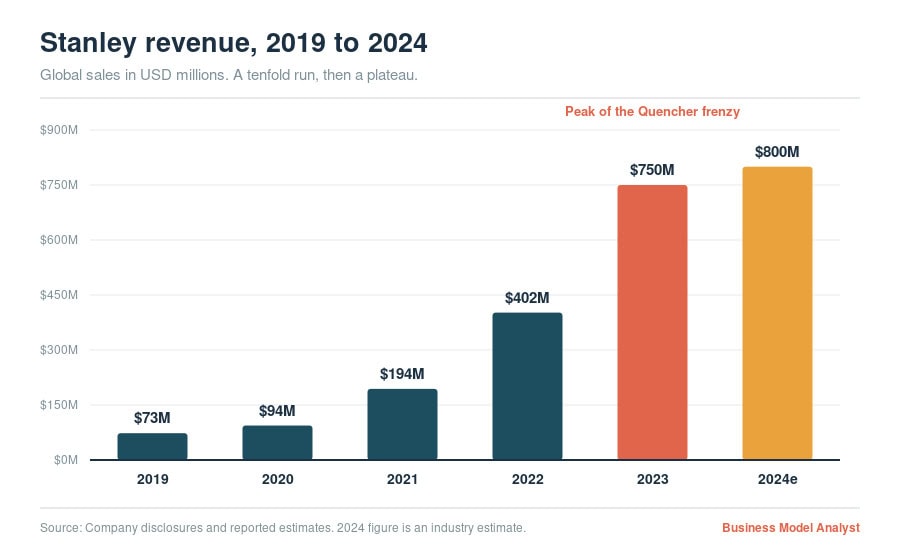
Most brand case studies about Stanley stop at the good part. Revenue went from $73 million in 2019 to roughly $750 million in 2023, the Quencher out-searched Taylor Swift on Amazon, and people fought each other in Target parking lots over a pink cup. That is a great story, and it is also a story with an ending that most write-ups skip.
The more useful question in 2026 is not how Stanley got hot. It is what a brand does when the heat leaves, because that is the phase Stanley is in right now, and it is the phase that reveals whether the marketing strategy was ever a strategy or just a very well-timed accident.
Who owns Stanley, and why that matters to the strategy
Stanley is owned by Pacific Market International (PMI), a privately held Seattle company. Private ownership is not trivia here. It means no quarterly earnings calls, no analyst pressure to defend a slowing category, and no public disclosure requirement. It also means every revenue figure you will read, including the ones in this article, is an estimate or a voluntary disclosure. Treat them accordingly.
It also gave Stanley something most consumer brands do not have: permission to deliberately under-supply a product that was selling out. A public company with a sell-through problem gets punished. A private one can call it strategy.
The four eras of Stanley
| Era | Years | Audience | Marketing engine |
|---|---|---|---|
| The utility era | 1913 to 2019 | Tradesmen, hunters, outdoorsmen | Product durability and word of mouth |
| The reassignment | 2020 to 2021 | Suburban women, roughly 25 to 55 | The Buy Guide affiliate partnership, color |
| The frenzy | 2022 to 2024 | Mass US consumer, heavily female | Scarcity drops, collaborations, UGC |
| The rebuild | 2025 to 2026 | Adding men, adding international | Sports sponsorship, category expansion |
The pivot point was 2020, when Terence Reilly left his role as CMO of Crocs to become president of Stanley. He carried the Crocs marketing strategy playbook with him almost intact: bold colors, creators who already loved the product, limited collaborations, and a willingness to let the internet be weird about your brand. It worked twice, which is the strongest available evidence that it was a repeatable method rather than luck.
The five pillars of the Stanley marketing strategy
1. Audience reassignment, not audience expansion
This is the part most brands get wrong when they copy Stanley. Stanley did not add women to its existing customer base. It effectively abandoned the customer it had built a century of equity with and handed the product to a completely different person.
The trigger was external. The Buy Guide, an Instagram account run by three women with an audience skewed heavily toward women aged roughly 35 to 44, had been quietly evangelizing the Quencher for years while Stanley was close to discontinuing it. Stanley’s insight was not discovering the audience. It was believing the audience when it showed up unrequested, and then restructuring the entire brand around it.
The affiliate deal that followed, where The Buy Guide bought inventory and resold it directly, gave Stanley a zero-risk proof of demand before it committed a dollar of its own marketing budget.
2. Color as the product roadmap
Stanley’s chief product and sustainability officer, Graham Nearn, has been explicit that changing color changed the trajectory of the company. That sounds like brand fluff until you look at what it does operationally.
A new colorway is not a new product. It requires no new tooling, no new engineering, no new supply chain. It is the cheapest possible way to manufacture newness. Stanley turned a single SKU into an infinite content calendar, and it did so while keeping one of the simplest supply chains in consumer goods. Seasonal palettes, holiday drops, and retailer exclusives all run off the same tumbler.
The strategic trade is elegant: maximum perceived novelty, minimum operational complexity, and a margin structure that survives it.
3. Manufactured scarcity, stated out loud
Reilly was unusually candid about this. He has said the frenzy is not accidental and that scarcity exists to create the demand. Most brands run this play and then pretend the sellouts surprised them. Stanley said the quiet part into a microphone.
The mechanism is a closed loop. Limited units create sellouts. Sellouts create resale premiums and queues. Queues create fan content and news coverage. Coverage creates demand for the next drop. The Starbucks collaboration sold at Target in early 2024 is the canonical example: people camped overnight, footage of the stampede went everywhere, and Stanley paid nothing for the distribution.
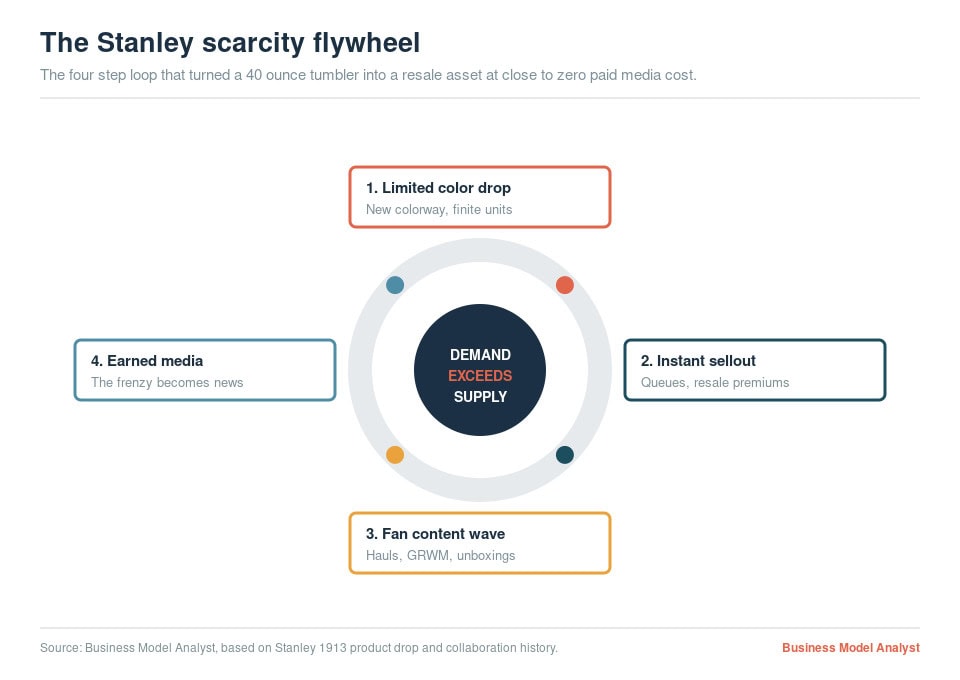
The important thing to understand about this flywheel is that it is a demand accelerant, not a demand generator. Scarcity multiplies desire that already exists. It cannot create desire from nothing. That distinction is why the flywheel eventually stopped, and we will come back to it.
4. The collaboration ladder
Stanley’s collaborations were not random celebrity grabs. They followed a legible logic, each one extending the brand into a new identity territory while staying inside the same product.
| Collaboration type | Examples | Strategic job |
|---|---|---|
| Retail exclusive | Target, Starbucks | Manufacture in-store scarcity events |
| Beauty and fashion | e.l.f. (lip gloss holder), LoveShack Fancy (bows) | Confirm the tumbler as an accessory, not a bottle |
| Music and celebrity | Olivia Rodrigo, Post Malone, Lainey Wilson | Buy cultural relevance across subcultures |
| Global pop | JENNIE (first K-pop partnership, Quencher Luxe) | Enter Asia-Pacific with a native icon |
| Sport | Arsenal, PSG, Juventus, Lionel Messi, Caitlin Clark | Acquire male and international customers |
The e.l.f. and LoveShack Fancy partnerships deserve particular attention, because they were reverse-engineered from social listening. Consumers were already accessorizing their Quenchers with bows and clip-on pouches. Stanley did not invent those behaviors. It productized them and sold them back.
5. Reactive marketing at speed
The car-fire moment is the best-known instance. A customer posted footage of her burnt-out vehicle with an intact Stanley still holding ice. Reilly responded personally, replaced the cup, and then replaced the car. The cost was one vehicle. The return was a global earned-media cycle no ad budget could have purchased.
This is the pillar least amenable to copying, because it depends on a leader with the authority to make an expensive, unbudgeted decision inside a few hours. Most brands route that decision through legal and lose the moment.
Where the strategy broke
Here is the part the case studies leave out.
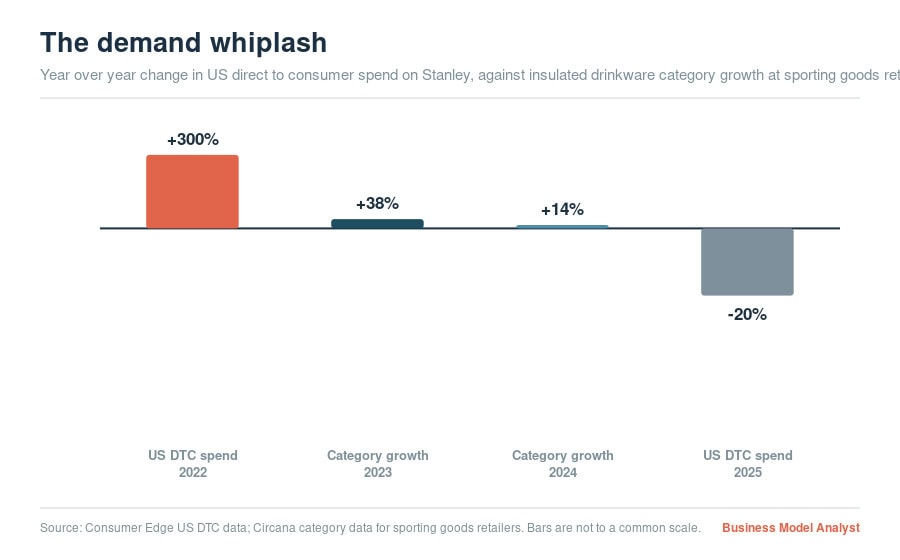
The hydration category saturated. Sales of bottles and insulated containers at sporting goods retailers declined year over year every month from September 2024 through February 2025, according to Circana. On a full-year basis, the category decelerated from 38% growth in 2023 to 14% growth in 2024. Consumer Edge data shows US direct-to-consumer spend on Stanley grew more than 300% in 2022 and then fell about 20% in 2025. Stanley’s own e-commerce store did roughly $138 million in 2025, down high single digits year over year.
Three things happened at once, and each one attacks a different pillar.
Ubiquity killed scarcity. Once everyone owns the cup, a limited color is no longer a status object. Scarcity marketing has an inverse relationship with penetration. The more successful it is, the faster it destroys its own precondition.
A better product showed up. Owala overtook Stanley as America’s best-selling stainless steel water bottle in 2023 on the strength of a lid, of all things. Stanley won the culture war and then lost the product war to a competitor with a better spout. Yeti and Hydro Flask continue to hold their positions. Our Yeti competitors breakdown maps that field in more detail.
The architect left. Reilly departed in 2024 to run Crocs’ HeyDude brand. The playbook stayed. The person willing to give away a car did not.
There was also the 2024 lead controversy, in which the vacuum-sealing pellet at the base of the cup was found to contain lead. The technical reality was that it cannot contact the drink in normal use, and the related class action was dismissed in April 2026. But the episode cost Stanley something more expensive than a settlement: it introduced doubt into a brand whose entire proposition was uncomplicated aspirational fun.
The 2026 rebuild
Under CEO Matt Navarro, Stanley is now executing a different strategy. Not a refinement of the old one. A different one.
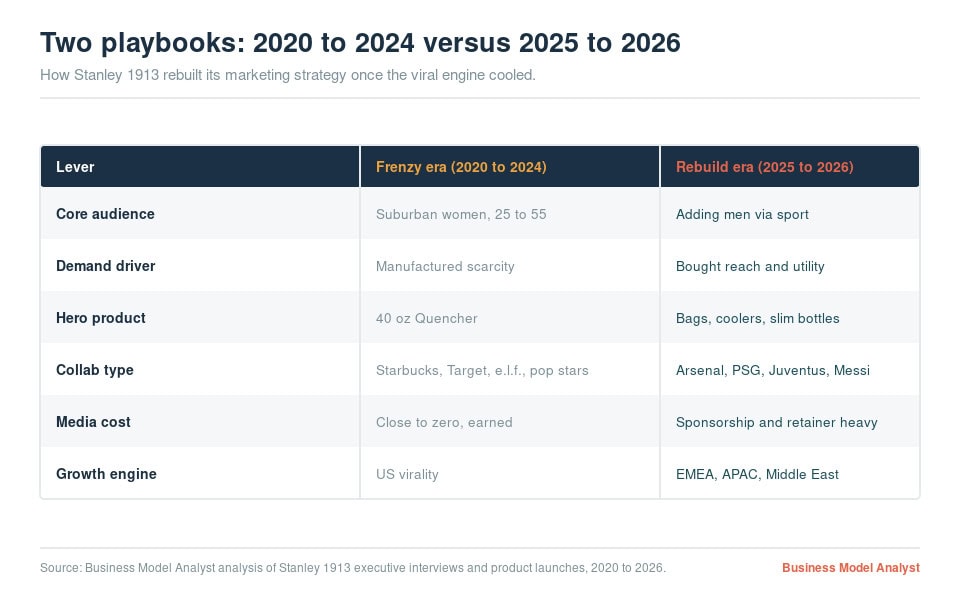
Sport as the customer acquisition channel. Stanley has signed multi-year partnerships with Arsenal, Paris Saint-Germain, and Juventus, a collection with Lionel Messi timed to the 2026 World Cup, a deal with Caitlin Clark, a partnership with women’s sports platform Togethxr, and a large activation at the Masters. EMEA general manager Ben James has described football partnerships as the highest-generating new-customer acquisition group the brand has built to date. That is the single most revealing sentence Stanley has said publicly in two years.
The male customer. Navarro has called men a more recent target. This is a return to the brand’s pre-2020 demographic, but at a much higher price point and with none of the original positioning left.
Category expansion. Soft goods since 2024, and in 2026 the Vitalize Collection of backpacks, totes, and shaker bottles, the Clutch Bottle, and the Flowstate Spring Bottle. The intent is to become an accessories brand rather than a drinkware brand, which is the standard escape route for a company whose hero product has peaked.
Geography. Middle East and Asia-Pacific are the growth markets, with EMEA already Stanley’s fastest-growing region.
The uncomfortable trade nobody is naming
Every element of the 2020 to 2024 strategy was cheap. Color drops, affiliate relationships, creator seeding, and reactive stunts cost close to nothing relative to the revenue they generated. That is what made Stanley’s economics so attractive: enormous top-line growth on a marketing budget that barely moved.
Every element of the 2026 strategy is expensive. Arsenal, PSG, Juventus, Messi, and the Masters are not earned media. They are line items. Stanley has swapped a zero-cost demand engine for a purchased one, at exactly the moment its category stopped growing.
That is not necessarily wrong. Sponsorship is how you build a durable brand rather than a viral one, and Stanley clearly decided that a smaller, defensible business beats a larger, fragile one. But it means the marketing strategy people still study is no longer the marketing strategy Stanley runs. The famous playbook and the current playbook are different documents.
Frequently asked questions
What is Stanley’s target market in 2026? Historically tradesmen and outdoorsmen, then suburban women aged roughly 25 to 55 during the Quencher boom. As of 2026, Stanley is deliberately broadening back toward men through football and golf partnerships while retaining its female base through women’s sports and lifestyle collaborations.
How much revenue does Stanley make? Stanley is privately held under Pacific Market International, so figures are estimates. Reported sales rose from about $73 million in 2019 to roughly $750 million in 2023, with 2024 estimated near or above $800 million. US direct-to-consumer spend fell roughly 20% in 2025.
Who is Stanley’s biggest competitor? Owala, which overtook Stanley as America’s best-selling stainless steel water bottle in 2023. Yeti, Hydro Flask, and Simple Modern also compete directly.
Why did the Stanley Quencher go viral? A combination of an unexpected affiliate partnership with The Buy Guide, a shift to bold seasonal colors, deliberately limited product drops that created sellouts and resale premiums, and a wave of user-generated TikTok content that Stanley amplified rather than controlled.
Is Stanley still popular in 2026? Yes, but the category has cooled. Stanley retains roughly 30% of US direct-to-consumer drinkware spend per Consumer Edge, while overall sales have softened and the brand is shifting toward bags, sport, and international markets for growth.
Who is the CEO of Stanley? Matt Navarro is president and CEO. Terence Reilly, the president who engineered the viral turnaround, left in 2024 to lead Crocs’ HeyDude brand.
The Business Model Analyst Take
Stanley’s marketing strategy is taught as a masterclass in virality. It should be taught as a masterclass in something less flattering and more useful: what happens after.
The core insight was never the color, the scarcity, or the collaborations. It was that Stanley found a group of customers who wanted its product more than its existing customers did, and had the nerve to fire the old audience. Everything else was execution on top of that one act of courage.
But scarcity is a lever, not an engine. It amplifies demand that exists and does nothing when demand fades. Stanley pulled that lever so hard and so successfully that it saturated its own market, and the moment the cup was everywhere, the strategy that made it desirable became the strategy that made it ordinary. That is not a failure of execution. It is the built-in expiry date of the tactic, and any founder copying the Stanley playbook should price that in from day one.
The 2026 rebuild tells you what Stanley learned. Football clubs, Messi, the Masters, backpacks, and the Middle East are not the moves of a company that thinks lightning strikes twice. They are the moves of a company converting a cultural moment into an asset base before the moment fully evaporates. It is buying permanence with the profits of a fad, which is the single smartest thing a company in Stanley’s position can do.
Whether it works depends on a question nobody can answer yet. Crocs made the same transition and became a durable $4 billion business. Most viral brands do not. Stanley has maybe eighteen months of brand equity left to spend on the attempt, and it is spending it fast.