
What is Stanley’s business model? Stanley 1913 designs, manufactures and sells insulated food and beverage containers under the PMI WW Brands operating company, which sits alongside a supply chain firm, a marketing agency and a foodservice company inside Morgan Street Holdings. It makes money by selling a small number of tooled product shapes in a very large number of finishes, through a mix of owned direct-to-consumer storefronts in about twenty markets, wholesale accounts, and licensed collaborations. The economic engine is not invention. It is variance on an already-amortized tool.
Every profile of Stanley starts in the same place: a 40 ounce cup, a TikTok wave, a brand that went from roughly $73 million in revenue in 2019 to around $750 million in 2023. That story has been told to exhaustion, including by us in our Stanley marketing strategy breakdown of how manufactured scarcity did the work.
The business model question is different and almost nobody asks it. Not how did Stanley get hot, but what kind of company is this, structurally, and how does it convert a steel cylinder into a margin.
The answer starts with an ownership chart that is drawn wrong nearly everywhere, including in most of the coverage published this year.
The parent company is not who you think it is
The standard line is that Stanley is owned by HAVI, the supply chain group that has served McDonald’s since a 1974 handshake in Chicago. HAVI did acquire PMI Worldwide on September 1, 2021. That much is right.
What happened next is not in the coverage.
According to HAVI’s own corporate timeline, Pacific Market International was split apart in 2022. The global merchandising business went to tms, the group’s marketing and sourcing arm. The drinkware brand, Stanley 1913, was carved out and became its own operating company. In 2023 the group launched Morgan Street Holdings as a dedicated investment vehicle. In 2025 HAVI Global Services was itself renamed Morgan Street Holdings, and the HAVI name was narrowed to cover only the supply chain business.
So the current structure is this. Morgan Street Holdings, headquartered on North Morgan Street in Chicago and chaired by Russ Smyth, owns four operating companies: HAVI for supply chain, tms for marketing and promotions, Continental Services for workplace foodservice, and Stanley 1913.
| Operating company | What it does | Who pays it | How it gets paid |
|---|---|---|---|
| HAVI | Freight, warehousing, planning, waste and recycling | Restaurant and foodservice chains | Service contracts on volume |
| tms | Marketing, promotions, sourcing, merchandising | Brand and retail clients | Fees and sourced program margin |
| Continental Services | Workplace and hospitality food programs | Employers and venues | Service and program contracts |
| Stanley 1913 | Branded insulated drinkware and gear | Individual shoppers | Product margin at retail |
Three of the four sell throughput to businesses on contracts. One sells cups to people. Stanley is the only consumer-facing profit and loss statement in the entire group, and it is a sibling of HAVI rather than a division of it.
This is not a trivia correction. It explains most of what Stanley does.
What a supply chain parent optimizes for
The scale asymmetry is worth sitting with. Morgan Street describes itself as serving more than 300 customer brands with over 10,000 employees across more than 50 countries. HAVI alone reports about 7,500 employees, more than 75 distribution centers, roughly 1,000 trucks, over 20 markets and more than two million deliveries a year.
Stanley, against that, operates localized storefronts in roughly twenty markets and does not publish a single financial figure.
Notice also what HAVI’s services pages actually describe: freight management, distribution and warehousing, planning and analytics, waste and recycling. Stanley appears on the site only in the section listing the parent’s portfolio, never as a capability HAVI sells. The consumer brand is an asset of the family, not an extension of the service business.
A group built on moving other people’s products at contracted margins has a very particular reflex. It is excellent at throughput, purchase orders, forecasting, container flow and cost per unit shipped. It has essentially no institutional muscle for the thing consumer brands normally live on, which is developing new product architectures and absorbing the cost of the ones that fail.
Stanley’s own product chief, Graham Nearn, has described a normal brainstorm-to-prototype cycle in this category as running around three years. Stanley’s chief brand officer, Kate Ridley, described building five product lines in ten weeks in 2026. Those two statements describe different companies, and the gap between them is where the business model actually lives.
Because if you cannot do three-year development cycles at speed, and you are under pressure to show newness every quarter, you do the thing your parent’s DNA is good at. You place another purchase order.
How the revenue is actually assembled
Stanley publishes nothing, so the revenue architecture has to be read off the operating footprint. Four streams are visible.
Owned direct-to-consumer. Localized storefronts run in roughly twenty markets, split four in the Americas, seven in Europe and nine in Asia-Pacific. Consumer Edge estimates Stanley captures around 30 percent of US direct-to-consumer spending on bottles. DTC carries the best margin and, more importantly, carries the drop mechanic, because a timed release only works on a channel you control.
Wholesale. Target, Amazon, Dick’s Sporting Goods, Scheels, REI, Walmart and Nordstrom, among others. This is where volume lives and where margin is shared. It is also where retailer-exclusive colorways appear, which is a revenue stream disguised as an assortment decision: the retailer funds a guaranteed order in exchange for exclusivity, and Stanley gets a colorway underwritten before it is produced.
Collaborations. Messi, Caitlin Clark, Nelly Korda, Collin Morikawa, Arsenal, Paris Saint-Germain, Juventus, JENNIE, Post Malone, Olivia Rodrigo, Lainey Wilson, e.l.f., LoveShackFancy, Kacey Musgraves, KAROL G and FARM Rio, plus seven soccer tumblers timed to the World Cup. Read structurally, a collaboration is a colorway with a co-marketing budget attached and a price premium on top. The FARM Rio version sells at $65.00 against $55.00 for the core color. Same tool, same line, ten dollars more, and a partner brings the audience.
Accessories and replacement parts. Straws, lids, boots and brushes. Small in absolute terms and structurally the most interesting line in the catalog, because it is the only part of the business with a natural repeat cycle.
The pattern across all four is consistent. Stanley monetizes the same tooled object repeatedly by changing what is printed on it, who is standing next to it, and which channel it appears in. Almost nothing in the revenue architecture depends on making a new thing.
The mechanic: one tool, three hundred finishes
The Quencher is sold in 14, 20, 30, 40 and 64 ounce sizes. Five shapes.
We counted the finishes.
A community-maintained gallery that has tracked the 40 ounce Quencher since 2023 documents more than 300 distinct colorways and designs, including retired shades, retailer exclusives and collaborations. We pulled the full list in August 2026 and counted 328 entries, of which 302 carry a documented year of first release.
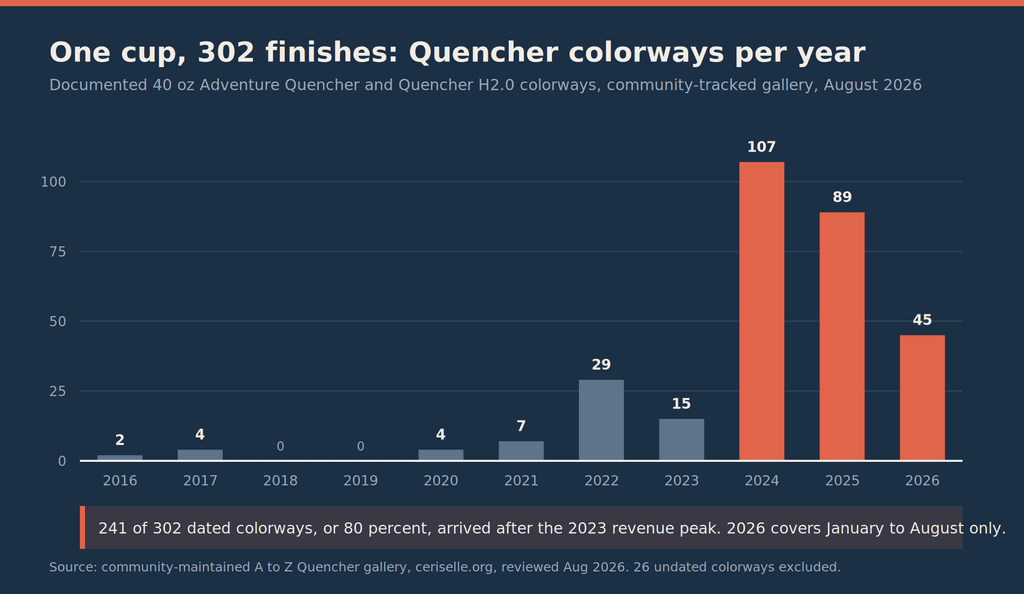
The distribution is the finding. Two colorways in 2016. Four in 2017. Seven in 2021. Then 29 in 2022, 107 in 2024, 89 in 2025, and 45 in the first eight months of 2026.
Add the last three years together and you get 241 colorways, which is 80 percent of every dated finish this cup has ever worn. All of it arrived after the 2023 revenue peak.
That is the sentence to sit with. Variety did not accelerate because demand was accelerating. Variety accelerated as demand decelerated. Consumer Edge data has Stanley’s US direct-to-consumer spending up more than 300 percent in 2022 and down about 20 percent in 2025, with 2026 running volatile. Over exactly that decline, the company roughly quadrupled the rate at which it introduced new versions of the same cup.
One honesty note on the data. The gallery records only 15 colorways in 2023, fewer than 2022, which is almost certainly under-documentation rather than a real pause, since 2023 was the peak mania year. Treat the shape of the curve as reliable and the individual level of any single year as approximate.
Why a color is cheap and a shape is not
The reason a company reaches for color instead of category is arithmetic, and the arithmetic is knowable even though Stanley discloses nothing.
Contract manufacturers of insulated steel drinkware publish their terms. In 2026 quotations, a custom color on an existing body requires no new tooling at all. It requires separate powder mixing, a production line cleaning, extra material for color adjustment and loss, and a minimum order that typically starts around 1,000 pieces per color. A plain Pantone change carries no plate charge whatsoever. Plate charges of roughly $50 to $600 appear only when the decoration changes, meaning printing, heat transfer or embossing.
A new shape is a different animal. New mold development generally requires a minimum around 10,000 pieces, plus tooling for the bottle body and separate injection tooling for the lid. A bespoke steel body mold runs roughly $2,500 to $5,500, with a full tooling package quoted between $15,000 and $40,000.
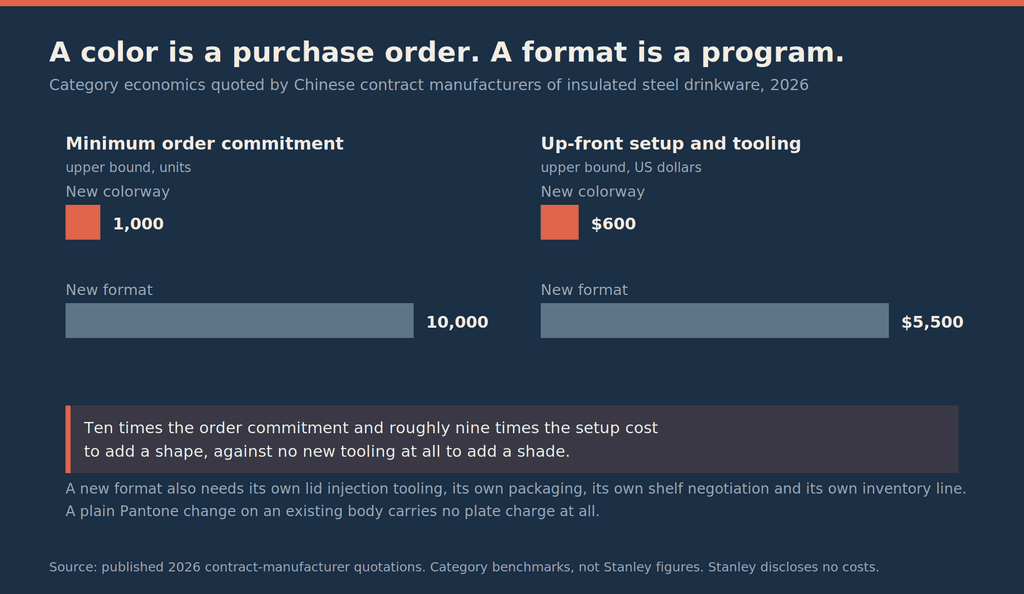
So the decision facing a merchandising team looks like this.
| New colorway | New format | |
|---|---|---|
| New tooling required | None | Body mold plus lid injection tooling |
| Setup cost | $0 to about $600 | Roughly $2,500 to $40,000 |
| Minimum order | About 1,000 units | About 10,000 units |
| Packaging | Usually existing | New |
| Retail shelf | Fits the existing facing | Needs its own negotiation |
| Inventory | Another line in an existing SKU family | A new SKU family |
| Failure mode | Markdown | Stranded tooling and dead inventory |
A color is a purchase order. A format is a program.
For a company whose parent is a logistics group, the left-hand column is the native language and the right-hand column is a foreign one. This is why the 2026 diversification push, meaning the Vitalize collection of backpacks, totes and shaker bottles launched in February, matters more than its revenue contribution suggests. It is the first serious attempt to operate in the right-hand column, and soft goods carry only a three year limited warranty against the lifetime coverage on the steel, which tells you how confident the company is in its own new categories.
Where the money actually sits
Take the arithmetic to the shelf.
Contract manufacturer teardowns published in 2026 put the factory-gate cost of a premium 18/8 stainless 40 ounce Stanley-type cup at roughly $5.20 to $6.50 EXW, meaning before freight, duty, packaging, warehousing and everything else. A comparable 30 ounce Yeti-type tumbler runs about $4.50 to $5.50.
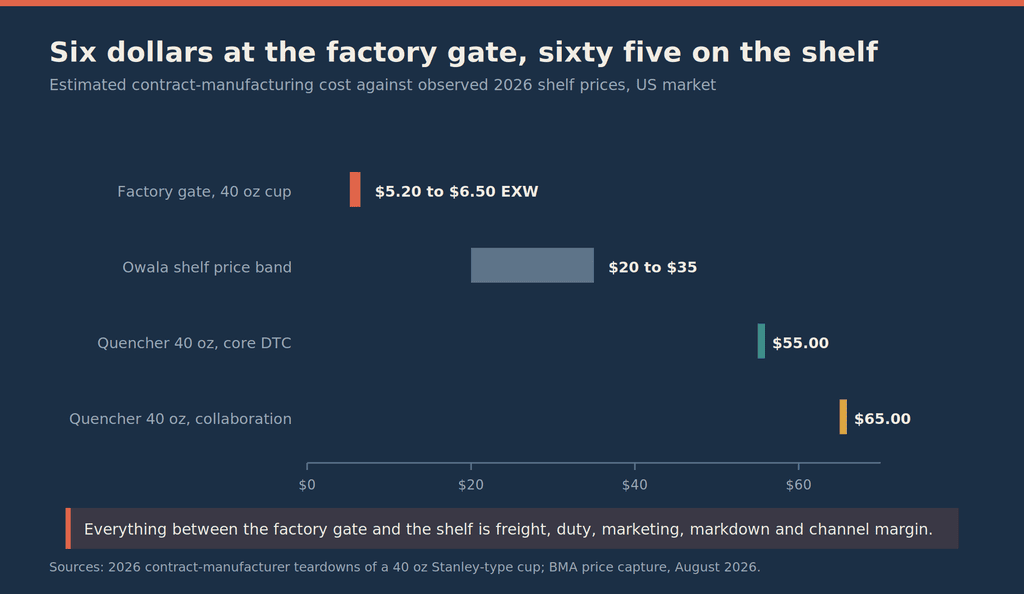
The core 40 ounce Quencher lists at $55.00 on Stanley’s US site. A collaboration version reaches $65.00. Owala, which took US stainless bottle leadership on lid design, sits in a $20 to $35 band.
Manufacturers advertise this gap aggressively. One 2026 supplier pitch tells prospective brands the arithmetic delivers “85%+ retail margins like Stanley or Yeti.”
It does not, and the proof is sitting in public filings.

Yeti is the only audited issuer in the category. Its FY2025 reported gross margin was 57.4 percent. Q1 2026 came in at 55.3 percent, dragged 280 basis points by tariffs. Q2 2026 adjusted gross margin reached 59.5 percent.
So roughly 26 points of margin disappear somewhere between the factory door and the income statement. That vanished 26 points is the entire business: inbound freight, Section 232 duties, packaging, warehousing, damaged goods, wholesale margin given to Target and Dick’s, discounting, returns, marketing, and the cost of maintaining a catalog wide enough to need a color gallery.
Which reframes the colorway strategy. Each new color is close to free at the factory. It is not close to free at the warehouse, on the shelf, or on the markdown rack. Stanley’s model spends nothing to create variety and pays for it later, in the least visible line items.
The factory problem nobody in the category shares
There is one more structural feature, and it separates Stanley from every competitor.
PMI holds equity in three manufacturing plants: PMI Joinease in China, and two in Brazil, in Rio de Janeiro and Manaus. It has manufactured in China since 2002, the same year it acquired the Stanley and Aladdin rights.
Yeti does not own factories. It rents capacity from contract manufacturers across Vietnam, the Philippines, Thailand, Mexico, Cambodia, Indonesia and Malaysia, and used that flexibility to cut its exposure to Chinese goods tariffs below 5 percent of cost of goods sold by the end of 2025.
Owning plants is normally a strength. In a tariff regime that reprices by proclamation, it is a liability with a specific shape: a contract can be renegotiated in a quarter, and a plant you hold equity in cannot be exited without writing down the asset. As of April 2026, Section 232 duties apply to the full customs value of covered steel, aluminum and copper derivative articles rather than only the metal content, at rates up to 50 percent.
The Brazilian plants serve South America. They are not a hedge for the US market.
There is also a quieter conflict in the model. PMI has long produced private label goods for select global retailers, meaning it manufactures the store brands of some of the same retailers that stock Stanley on the next shelf over. Whether that capability moved to tms in the 2022 merchandising split or stayed with the drinkware operating company is not disclosed anywhere we could find, and it is a boundary worth watching, because it determines whether Stanley’s own factory is arming its shelf competitors.
The brands you never see
PMI carries more than Stanley. Aladdin, founded in 1908, is the other century-old name in the portfolio. Migo, founded in 1999, is positioned for Asia-Pacific. Both are sold globally and neither generates meaningful English-language coverage.
This is a deliberate structure. A multi-brand vessel manufacturer can address premium, mid and value price points without contaminating the flagship, and can fill the same factory lines across all three. It is a very old industrial logic: build once, badge three times.
PMI also bought Formation Brands, a private label and gift-retail housewares business, which added San Francisco, Shenzhen and Hong Kong to a footprint that already ran through Seattle, Bentonville, Shanghai, Amsterdam, Manila and Rio de Janeiro. Bentonville is the detail worth pausing on. You open an office in Bentonville for exactly one reason, and it is not brand building.
Stanley itself is credited with more than 100 patents by its global president, Matt Navarro, while the corporate entity is recorded as having filed more than 250. Either figure describes real engineering. Neither figure is currently the thing generating revenue, which is a fair summary of the entire tension in this company.
The model on one page
| Building block | What it looks like at Stanley |
|---|---|
| Value proposition | A durable insulated vessel that also reads as a personal style object, backed by a lifetime warranty on the steel |
| Customer segments | Originally tradesmen and campers, then a hydration-led female buyer from 2020, now defined increasingly by occasion rather than demographic |
| Channels | Owned DTC in about twenty markets, wholesale, retailer exclusives, collaborations |
| Key resources | The Quencher tooling, the trademark, equity in three plants, roughly 250 filed patents |
| Key activities | Colorway development, drop scheduling, partnership sourcing, demand planning |
| Key partners | Contract and owned factories, big-box retailers, athletes and consumer brands, enterprise supply chain software |
| Cost structure | Steel and coating, freight and duty, warehousing and markdown, retailer margin, partnership fees |
| Revenue streams | Product margin at four price tiers, from marked-down mass retail up to collaboration pricing |
| Structural weakness | No replacement cycle on the core product and no consumable the warranty covers |
One line in that table is the whole company. Under key partners sits enterprise supply chain software, because Stanley runs its direct-to-consumer order management on Blue Yonder, the same class of planning system its sibling company sells to restaurant chains. A viral consumer brand that processes launches through industrial demand-planning infrastructure is not a startup that got lucky. It is a supply chain organization that acquired a customer base.
What breaks this model
Five things, roughly in order of how soon they bite.
Replacement demand that does not exist. The steel body carries a lifetime warranty and over ten million Quenchers had shipped by the end of 2023. A durable good sold to a saturated base has no natural repurchase cycle, which is why our Stanley SWOT analysis landed on the lid, seal and straw as the only consumables in the catalog and the only components the lifetime warranty excludes.
Catalog cost. Three hundred finishes is not free inventory. It is forecasting risk across hundreds of stock lines with different sell-through, and markdown is where that risk shows up.
Tariff exposure on owned capacity. See above. Yeti can move. Stanley owns.
Discovery in a text-first search environment. Ridley told Digiday in August 2026 that Stanley’s occasion marketing had been heavy on image and light on copy explaining use. Brand equity built in photographs does not index well when a growing share of adults ask a chatbot what cup to buy.
Second-mover economics in new categories. Backpacks, totes and shakers put Stanley into markets with incumbents who have three-year development cycles and their own amortized tooling. The color playbook does not transfer.
Frequently asked questions
Who owns Stanley 1913? Stanley 1913 operates as PMI WW Brands, LLC, an operating company of Morgan Street Holdings, a private holding group in Chicago. Morgan Street also owns HAVI, tms and Continental Services. HAVI acquired PMI Worldwide in September 2021, and PMI was split in 2022, with Stanley becoming a standalone operating company rather than a HAVI division.
How does Stanley make money? By selling insulated drinkware and, since 2024, soft goods, through owned direct-to-consumer storefronts in roughly twenty markets, wholesale accounts including Target, Amazon, Dick’s Sporting Goods, Scheels and REI, and licensed collaborations. It does not publish revenue, margin or segment data.
How much does a Stanley cup cost to make? Stanley does not disclose it. Contract manufacturers quoted roughly $5.20 to $6.50 EXW in 2026 for a comparable premium 18/8 stainless 40 ounce cup, before freight, duty, packaging and every downstream cost. That is a category benchmark, not a Stanley figure.
Why does Stanley release so many colors? Because a new color requires no new tooling and a minimum order around 1,000 pieces, while a new shape requires a body mold, separate lid injection tooling and a minimum order around 10,000. Color is the cheapest available form of newness.
How many Stanley Quencher colors are there? More than 300 documented finishes of the 40 ounce cup alone. Our August 2026 count found 328 catalogued colorways and designs, of which 302 carry a documented release year.
Is Stanley more profitable than Yeti? Unknowable from public data. Stanley publishes nothing. Yeti reported 57.4 percent gross margin for FY2025 and 59.5 percent adjusted in Q2 2026. Stanley’s owned factories and heavier promotional posture cut in different directions against those numbers.
Does Stanley manufacture its own products? Partly. PMI holds equity in three plants, one in China and two in Brazil, and has manufactured in China since 2002. This distinguishes it from Yeti, which uses contract manufacturers exclusively.
What is Stanley doing to diversify? Three declared levers: product, meaning the Vitalize collection of backpacks, totes and shakers launched in February 2026 plus stated ambitions in sport, lunch and wellness; consumer, meaning a reconquest of male buyers through sports partnerships; and geography, with Europe and Asia-Pacific growing faster than the US.
The Business Model Analyst Take
Stanley is not a drinkware brand that happens to be owned by a logistics group. It is a logistics group’s consumer asset that happens to sell drinkware, and reading it that way makes the strategy legible instead of baffling.
The company found something rare: a fully amortized tool with cultural permission to be reissued indefinitely. For four years it monetized variance rather than invention, and the returns were extraordinary because variance is nearly free at the factory gate. The 2024 to 2026 colorway acceleration was not a sign of creative confidence. It was a company doing more of the only cheap thing it knew how to do while its hero product’s demand curve rolled over.
The honest question for the next five years is whether the right-hand column of that cost table can be learned. Backpacks, coolers, lunch and sport all require a company to spend real money before it knows whether the market wants the thing, and to absorb the loss when it does not. That is a fundamentally different risk appetite than placing another powder-coat order against a mold that paid for itself in 2017.
Our read is that Stanley’s owners understand this, which is why the brand was carved out as a standalone operating company in 2022 rather than left inside a supply chain business. Standalone is what you do when you intend to build a consumer company rather than harvest a consumer asset.
The tell will be simple. If 2027 brings another hundred colorways and two new categories, the harvest is still running. If it brings forty colorways and six new categories, the model actually changed.
For the competitive picture on the other side of this category, see our Yeti target market analysis and the field map in Yeti competitors.