
Corporate AI investment more than doubled in 2025 and consumer value jumped 54% to $172 billion. The catch: almost none of that value is landing with the companies spending the most to create it.
Stanford’s Institute for Human-Centered AI just dropped its 2026 AI Index, the field’s most-cited annual scorecard, and the top line reads like a victory lap. Global corporate AI investment more than doubled. Adoption hit 88% of surveyed organizations. The value consumers pull from generative AI grew 54% in a single year to roughly $172 billion in the US alone.
Read past the headline numbers and a sharper story shows up. Enormous value is being created, but the people footing the bill are not the ones capturing it. For founders and operators, that gap is the whole ballgame.
The AI Index is an annual report from Stanford HAI that tracks, cleans, and visualizes data on artificial intelligence across investment, technical performance, adoption, labor, and policy. It is widely treated as the closest thing the industry has to a neutral, source-of-record dataset.
The numbers that matter
Here is the operator’s cheat sheet, pulled straight from the report’s Economy and Technical Performance chapters.
| Metric | 2026 AI Index figure |
|---|---|
| Growth in global corporate AI investment | More than doubled in 2025 |
| Growth in private AI investment | Up 127.5%, now 60% of the total |
| US lead over China in private AI investment | 23x larger |
| US consumer surplus from generative AI | $172B, up from $112B a year earlier |
| Organizations using AI | 88% (70% in at least one business function) |
| AI agent deployment across functions | Still in the single digits |
| Generative AI adoption in three years | 53%, faster than the PC or the internet |
| Employment, software developers ages 22 to 25 | Down nearly 20% from 2024 |
| Orgs expecting AI to cut headcount next year | One in three |
The money doubled, and it piled into one place
Private investment grew fastest, up 127.5%, and now makes up 60% of all AI funding. Generative AI led the surge with growth above 200%, capturing close to half of every private AI dollar. The number of newly funded AI companies rose 71%, and billion-dollar funding events nearly doubled.
Geographically, this is still an American story. US private AI investment ran 23 times larger than China’s, and in generative AI specifically, the US outspent China and Europe combined. The asterisk: China’s official private figures undercount the state, which the report estimates funneled around $184 billion into AI firms through government guidance funds between 2000 and 2023.
The uncomfortable counterweight to all this spending is the cost line. AI company revenue is climbing at historically fast rates, but compute costs are climbing right alongside it. Google alone reported more than $150 billion in capital expenditure in 2025. That is the structural problem we walked through when OpenAI’s leaked financials showed a $38 billion loss on $13 billion in revenue: revenue scale is real, but so is the meter, and the meter does not stop when you add users.
The value is real, mostly free, and not where you would guess
The most striking number in the report is consumer surplus. The value US consumers get from generative AI hit roughly $172 billion a year by early 2026, up from $112 billion twelve months earlier, with the median value per user tripling. Most of those tools are still free or close to it.
Sit with that. Tens of billions in new value, growing fast, and the model makers are largely not capturing it. It is flowing to users in the form of free tools, and to the companies disciplined enough to deploy AI well. Adoption backs this up: 88% of organizations now use AI, and generative AI shows up in at least one business function at 70% of them. But agents, the thing every vendor deck promises, are still deployed in the single digits across nearly every function. The hype is running well ahead of the install base.
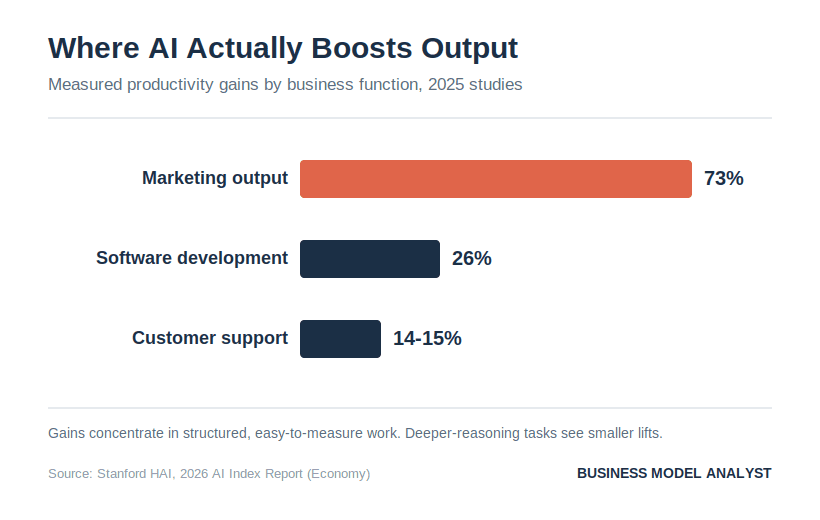
Where AI actually moves the needle is narrow and specific. The report pegs gains at 14% to 15% in customer support, 26% in software development, and 73% in marketing output. The pattern is consistent: AI pays off in structured, measurable work where you can see the output. It does much less for tasks that need deep reasoning. There is even an early warning buried in the data that heavy AI reliance may carry a long-term learning penalty, quietly slowing how fast people build skills.
The labor signal stopped being hypothetical
For two years the AI jobs conversation was mostly vibes. This report puts a number on it. Employment for software developers ages 22 to 25 has fallen nearly 20% since 2024. The damage is concentrated exactly where you would expect a labor-market shock to land first: hiring pipelines and the youngest workers in the most exposed jobs.
It is not a broad collapse yet. Large-scale job losses still have not shown up in aggregate employment data, and almost half of surveyed organizations expect little to no headcount change. But one in three expect AI to shrink their workforce over the coming year, with the deepest cuts anticipated in service operations, supply chain, and software engineering. The expectation gap is the tell: across nearly every function, the cuts companies anticipate outrun the ones already on the books.
The frontier converged, so the war is now about price
Here is where the macro data confirms the on-the-ground story. On the Chatbot Arena leaderboard, the top labs have bunched into a near-photo-finish. As of March 2026, Anthropic, xAI, Google, and OpenAI all sit within 25 Elo points of one another, with Alibaba and DeepSeek close behind.
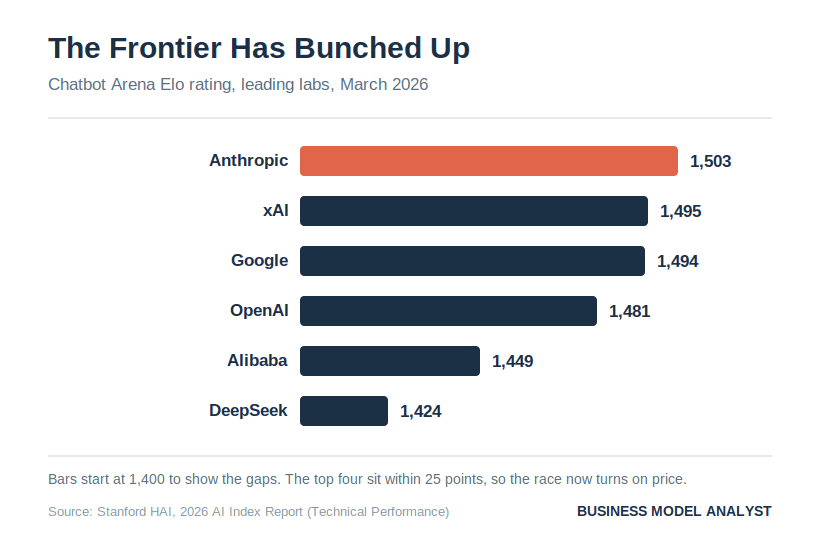
When the leading products become this interchangeable, the report notes competition shifts toward cost, reliability, and domain-specific performance. That is not a forecast. It is already happening. We have covered OpenAI weighing drastic token price cuts to pull customers from Anthropic, the enterprise token-bill explosion that sent finance teams scrambling, and big tech quietly rationing every token after the “tokenmaxxing” hangover. The 2026 AI Index is the neutral referee confirming what the headlines have been screaming: when capability commoditizes, price becomes the battlefield, and shared dominance over a commodity is not a moat. If you want the deeper teardown of how these revenue lines actually pull against each other, see our OpenAI business model breakdown.
What operators should do with this
| If you are… | The report’s signal | The move |
|---|---|---|
| Building on top of foundation models | Capability converged; price war underway | Stop marrying one vendor. Build for model portability and route cheap models to easy tasks |
| Deploying AI internally | Gains are real but narrow (support, code, marketing) | Aim AI at structured, measurable work first. Treat agents as experimental, not core |
| Pricing an AI product | Value is leaking to users, not capture | Compete on the thing customers cannot easily walk away from, not on raw model access |
| Planning headcount | Cuts hit junior and exposed roles first | Rethink your entry-level pipeline before the gap forces your hand |
| Raising capital | Investment doubled, but so did the burn | Investors now ask about unit economics, not just growth. Have the cost answer ready |
Frequently Asked Questions
What is the Stanford AI Index?
It is an annual report from Stanford’s Institute for Human-Centered AI that tracks and visualizes data on artificial intelligence across investment, performance, adoption, labor, and policy. It is widely used as a neutral reference dataset by researchers, executives, and journalists.
How much did AI investment grow in 2025?
Global corporate AI investment more than doubled. Private investment alone grew 127.5% and now accounts for about 60% of the total, with generative AI capturing close to half of all private AI funding.
Is AI actually taking jobs?
The data shows uneven, early effects rather than a broad collapse. Employment for software developers ages 22 to 25 fell nearly 20% from 2024, and one in three organizations expect AI to reduce their workforce over the next year, but aggregate employment has not dropped yet.
Where does AI deliver the biggest productivity gains?
In structured, measurable work. Studies in the report cite gains of 14% to 15% in customer support, 26% in software development, and 73% in marketing output, with smaller gains on tasks that require deeper reasoning.
Which AI company has the best model in 2026?
Performance has converged. As of March 2026, Anthropic, xAI, Google, and OpenAI all sit within 25 Elo points on the Chatbot Arena leaderboard, which the report says is pushing competition toward cost and reliability rather than raw capability.
The Business Model Analyst Take
The 2026 AI Index is being read as a story about momentum. We read it as a story about value capture, and the two are not the same.
2025 created a staggering amount of AI value. The problem for anyone in this market is that the value is leaking out of the businesses that spent the most to produce it. It is flowing to consumers through free tools, and to disciplined deployers who point AI at the few functions where it actually pays. The model makers, meanwhile, are burning record compute budgets to compete over products that the Arena data says are nearly indistinguishable.
That is the founder’s lesson hiding in a Stanford spreadsheet. Creating value with AI in 2026 is the easy part, and it is getting cheaper by the quarter. Capturing it is the entire game, and almost nobody at the frontier has solved it. Build the thing customers cannot walk away from, deploy AI where the numbers move, and treat any moat built purely on model access as already gone.