
The eye-popping sports valuations of 2026 mostly come from transactions where nobody bought a team. Owners are selling thin, passive, locked-up slices, and the press grosses those prices up into headline franchise values.
Lin Bin bought 1% of Stephen Ross’s Miami holding company in March at a valuation of $12.5 billion, the highest ever recorded in professional sports. Four months later the Seattle Seahawks, defending Super Bowl champions, sold outright for $9.61 billion. One owner described that auction as soft. The gap between those two numbers is the story: a sliver that carries no vote and cannot be resold for years now prices higher than an entire franchise with a trophy in the case.
What Happened
The New York Times ran a piece on August 15 asking whether sports valuations have entered mania territory. Tania Ganguli assembled the evidence anyone would assemble. Bob Iger and Joshua Kushner took control of the Lakers at $12.5 billion, ten months after Mark Walter bought the same team at $10 billion. The Seahawks changed hands in July at an NFL record. The Yankees took in $2.6 billion in a deal reported to value the club near $10 billion. Irwin Kishner of Herrick told the paper he sees no ceiling.
Line those transactions up and they look like the same event repeating. They are not. Iger and Kushner bought a team. The Khosla family bought a team. Apollo Sports Capital did something else entirely with the Yankees, and so did most of the buyers setting NFL records over the past twenty months.
Apollo’s Yankees agreement, announced August 11, runs primarily on debt with an equity component attached. The Steinbrenners keep control. Proceeds refinance existing borrowings and fund what Hal Steinbrenner called strategic opportunities. Sportico reported that the equity piece was expected to buy out existing limited partners, which means a portion of the money leaves through the back door to people cashing out rather than landing in the baseball operation. Nobody bought the Yankees. Forbes marked the club at $8.5 billion in March and Sportico at $9.4 billion. The Athletic’s Evan Drellich called the resulting figure a record valuation for an MLB team in a realized transaction.
Run the arithmetic MLB’s own rules force. A single private equity firm cannot hold more than 15% of a club. Against a $10 billion mark, that caps Apollo’s equity at roughly $1.5 billion, leaving a minimum of $1.1 billion of the celebrated $2.6 billion as borrowing. Report the whole number as a valuation event and you have described a refinancing as a sale.
The Backstory
NFL owners voted 31 to 1 in August 2024 to let approved funds buy in, with Cincinnati’s Mike Brown the lone holdout. The terms tell you what the league was selling. A fund takes no less than 3% and no more than 10%. It gets no decision-making power. It commits at least $2 billion of capital, holds each position a minimum of six years, and spreads across no more than six teams. Sovereign wealth funds and pensions cannot invest directly. Each club can carry up to 24 limited partners.
Eight firms cleared the vetting in four groups: Arctos, Ares, Sixth Street, and a consortium of Blackstone, Carlyle, CVC, Dynasty Equity and Ludis. Together they signalled around $12 billion of capital, roughly $500 million per team across the 24 clubs they can reach.
Then the marks started climbing, and the trades that set them started shrinking.
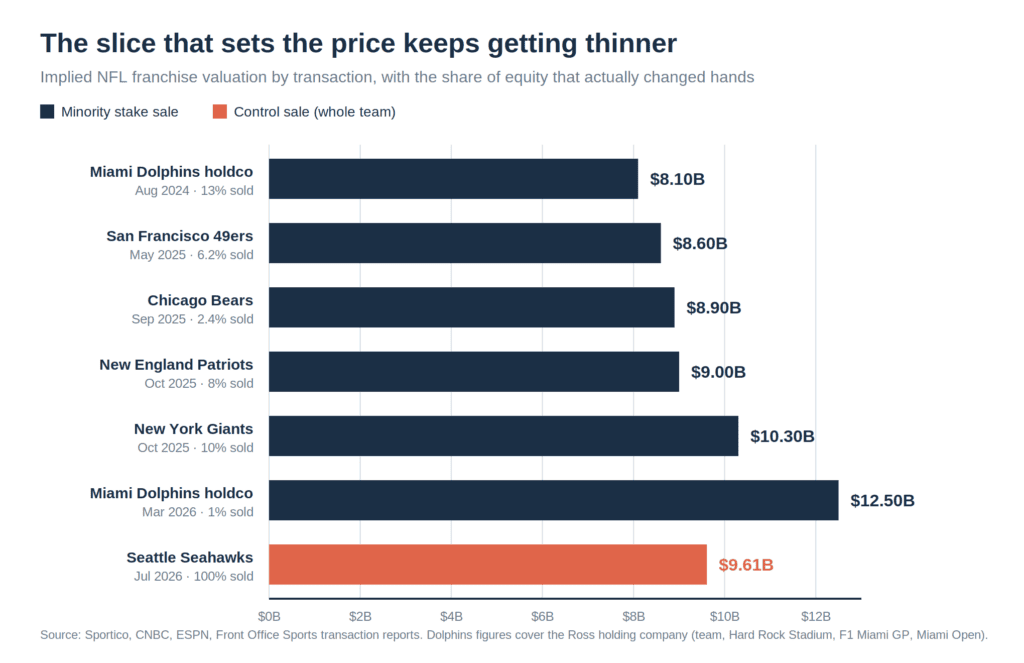
Ares took 10% of Ross’s Miami holding company in 2024 alongside Joe Tsai and Oliver Weisberg at 3%, pricing the group at $8.1 billion. The Yorks sold 6.2% of the 49ers at $8.6 billion in May 2025. The McCaskey and Ryan families traded about 2.35% of the Bears between themselves at $8.9 billion that September, a deal that skipped the full owner vote because both sides already owned in. Robert Kraft sold 8% of the Patriots to Sixth Street and Dean Metropoulos at a $9 billion pre-money mark in October. Julia Koch bought 10% of the Giants that same month at $10.3 billion.
Sportico now puts the average NFL franchise at $7.13 billion, up 20% from 2024.
The Plan
Owners want the money without the exit. Diane Gotua, who ran NBA global business strategy, told the Times that franchise buyers treat these as legacy assets and think about how they want to be remembered. Kishner said he would be surprised to see many primary owners sell majority stakes.
Take that seriously and the whole capital structure follows from it. If the people holding the most valuable private assets in North America refuse to sell, and their paper wealth compounds anyway, somebody has to build a way to turn that paper into cash without triggering a sale. That business now exists and has a name.
KKR paid $1.4 billion in February for Arctos, with up to $550 million more tied to performance. Arctos manages about $15 billion and holds positions in the Warriors, Jazz, Dodgers, Astros, Chargers, Devils and Bills. Read how the firm describes itself in KKR’s own SEC filing: it provides strategic growth capital and liquidity solutions to sports franchises. KKR folded it into a unit built around secondaries, a market that ran roughly $226 billion of volume in 2025, up 41%.
The largest holder of sports minority positions is now owned by a firm whose core skill is manufacturing liquidity for things that cannot be sold.
The Business Model Angle
Every valuation textbook applies two haircuts to a stake like Lin Bin’s. The discount for lack of control reflects that he decides nothing. The discount for lack of marketability reflects that he cannot sell on an exchange. The AICPA puts the combined range at 20% to 40% for minority interests. Taft’s sports practice notes that minority stakes in franchises often trade at a relative discount on the secondary market, with distressed limited partners selling below intrinsic value.
Lin Bin appears to have paid none of it. The $12.5 billion figure comes from grossing his 1% up by a hundred, which assumes his passive sliver is worth exactly one hundredth of the whole. Apply a 25% minority discount to that same purchase price and you would have to argue the Ross portfolio is worth $16.7 billion at control level. Nobody argues that. The simpler reading is that he paid full freight for something worth less than full freight, and the press converted his cheque into a franchise record.
Now compare the volumes. In 2024 roughly 13% of the Miami holding company traded to set an $8.1 billion mark, about $1.05 billion of equity changing hands. In March 2026, 1% traded to set $12.5 billion, about $125 million. The mark climbed 54% on roughly an eighth of the dollar volume.
That inversion runs through the entire cluster. The Dolphins mark sits 30% above the Seahawks control price struck four months later, for a club that last won a Super Bowl in 1974, against the reigning champion. The transactions bear no resemblance to each other and get quoted in the same sentence.
Leagues built this on purpose. Restricting funds to passive minority positions protected owner control, which was the point. It also created a security with no governance, no liquidity and no natural buyer, then let that security set the price of everything around it. Any owner who wants a higher mark on the family balance sheet can produce one by selling 1% to a willing billionaire. It costs him nothing he was using.
The Risk
Herrick, Kishner’s own firm, published the problem last year. A limited partner’s stake grows more valuable on paper while converting it to cash stays hard, because few buyers want minority positions. Full value arrives when a control sale triggers tag-along rights, sometimes drag-along rights, with limited partners typically holding a 30-day window to decide.
Every mark in the chart above converts to cash through the one event the owners say they will not do.
The first NFL institutional positions, Arctos into Buffalo and Ares into Miami, came free of their six-year locks around December 2030. Whoever wants out then sells to another fund, to the controlling owner, or waits for a control sale. Only the third path validates the price on the books.
The counterargument deserves a hearing. Sports revenue keeps growing on schedule, and the NBA’s eleven-year media package worth roughly $77 billion is contracted money rather than a projection. Legal betting opened a revenue line that did not exist a decade ago. Kushner’s Thrive Eternal bought the Lakers on a thesis that live events resist AI disruption. None of that is fantasy.
And marks do not always ratchet. The Yorks sold 3.2% of the 49ers to Pete Briger in October 2025 at the same $8.6 billion they got in May. Two trades, six months apart, flat.
The honest caveat on Miami cuts the same way. That $12.5 billion covers Ross’s holding company, which owns Hard Rock Stadium, the Formula 1 Miami Grand Prix and a piece of the Miami Open alongside the football team. Comparing it to a team-only price for Seattle overstates the gap. The trouble is that ESPN, Bloomberg and the wire services all reported it as the highest valuation in professional sports without the asterisk, and comp ladders get built from headlines.
Quick Questions
Did the Yankees really get valued at $10 billion? A financing transaction produced that figure. Apollo supplied credit plus an undisclosed minority equity piece, part of which buys out existing limited partners. MLB caps a single firm at 15%, so most of the $2.6 billion is debt.
Why would anyone pay full price for 1% and no vote? Access, status and a bet that the mark keeps rising. Lin Bin called it a wonderful investment and learning opportunity. Buying at a discount requires a seller who needs the money, and these sellers do not.
Are minority stakes really pricing above control? In the NFL right now, several are. The Dolphins holding company at $12.5 billion and the Giants at $10.3 billion both sit above the $9.61 billion Seattle cleared for a whole team, though the Miami figure bundles a stadium and a Grand Prix.
What breaks this? A control sale that clears well below the standing minority marks. The Seahawks came close, and one owner already called that market soft.
The Business Model Analyst Take
Sports franchises look like a bubble because the prices keep setting records. Look at what the buyers get and a plainer machine appears. Owners who will not sell need cash, funds with committed capital need somewhere to put it, and leagues wrote rules that let both happen without anyone giving up a vote. The valuations are exhaust from that arrangement.
Any asset class where the marks come from 1% trades, and the marks only convert through a transaction the holders have ruled out, is running on faith in the next buyer. That works while the next buyer keeps showing up. KKR spent $1.4 billion buying the firm that would have to organize things if he stops.
Watch the 2030 unlock, and watch the next control sale. Those are the only two events that pay in cash.