
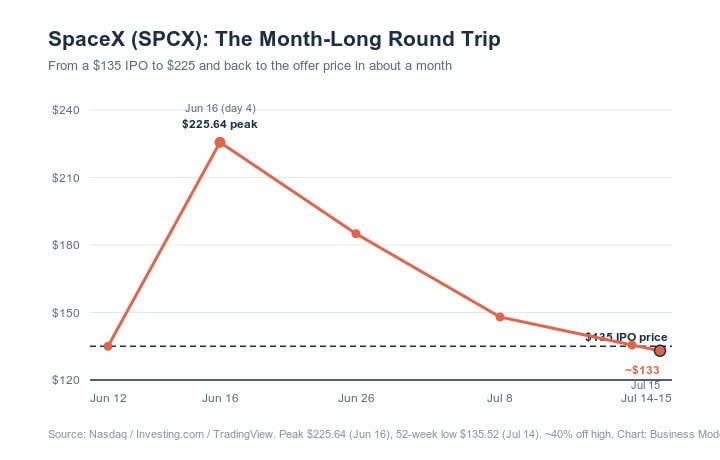
SpaceX priced the biggest IPO in history at $135 a share on June 12. On Wednesday, roughly a month later, the stock dipped below that number, touching the low $133s before clawing back to hover near $135 again. The round trip is complete, and it arrives one day before Starship is set to fly for the first time since the company went public.
The headline writes itself: the most hyped debut in years has given back everything. But the more useful question for anyone watching this stock, or planning their own listing behind it, is why. And the honest answer is that only a sliver of this move is a verdict on Elon Musk. The rest is plumbing.
What actually happened
SPCX opened its public life hot. Indications pointed to a first trade near $169, and within four trading days the stock hit an all-time high of $225.64 on June 16, briefly handing SpaceX a valuation that brushed up against Amazon and Microsoft territory. Then it bled. Almost every week since that peak, the stock has traded lower. By July 14 it set a 52-week low of $135.52, and on July 15 it slipped under the $135 offer price outright before recovering.
That is a drop of roughly 40% from the high in about a month, with the market capitalization now sitting near $1.81 trillion. For a stock that was supposed to be the cleanest debut in recent memory, this is a fast unwind. We flagged the early version of this slide when the average open-market buyer was already back to breakeven; the difference now is that the reference point is no longer the peak, it is the IPO price itself.
The 4% float is doing most of the work
Here is the fact that reframes the whole story: only about 4% of SpaceX’s total shares are actually trading on the Nasdaq. That is a tiny float. Layer an immense, constant flood of attention on top of a small pool of tradable shares, and you get exactly what we have seen: violent swings in both directions on relatively modest volume.
The stock’s beta sits near 5.79, and its daily volatility runs above 5%. Those are not the numbers of a market calmly repricing a business. They are the numbers of a thin, news-whipped instrument where a handful of large orders can move the tape several dollars. So when a headline says the market is “sobering up on Musk’s vision,” read it with a raised eyebrow. You cannot cleanly read investor sentiment off a book this thin. Any narrative built on a 4% float is built on sand.
That does not mean nothing real is happening. It means the signal-to-noise ratio is terrible, and the people confidently declaring what SPCX “means” are mostly narrating noise.
Nobody can actually value this company
The clearest evidence that this is a story problem, not a price-discovery success, is the analyst spread. Twelve-month targets on SPCX currently run from a low of $62 to a high of $800, with an average around $242. Read that again. The bull and the bear are not disagreeing at the margin, they are living in different universes, one pricing a $62 stock and the other a $800 stock. Raymond James is modeling more than 470% upside. One MoffettNathanson analyst has openly called SpaceX a difficult company to value.
That dispersion is the tell. It exists because the valuation was never anchored to current performance. SpaceX lost $4.3 billion in the first quarter on $4.7 billion of revenue, while its bankers pitch revenue forecasts running into the hundreds of billions by 2030 and trillions by 2040. For context we used at listing, Meta booked more than $56 billion in a single quarter and carries a comparable valuation. When we walked through the skeptics’ case before the debut, Morningstar pegged fair value near $780 billion, less than half the offer-price valuation, and Michael Burry warned any pop would run on “hype and technicals.” A month of trading has not resolved that argument. It has just moved it onto a live ticker.
The bonds are wobbling too
The equity is not the only thing under pressure. The bonds SpaceX sold in the wake of its IPO have also weakened, part of a broader deflation across tech assets over the past month. That matters because it removes one of the easy counterarguments. If only the stock were sliding, you could wave it away as float mechanics and retail churn. When the debt weakens alongside it, that is a cleaner signal that institutional appetite for the whole SpaceX capital structure has cooled, not just the meme-adjacent equity.
Why this is a bellwether, not just a Musk story
This is the part founders and operators should actually care about. SpaceX’s debut set the table for the next wave of trillion-dollar-adjacent listings, and both Anthropic and OpenAI have filed confidentially to go public. Neither has set a date. Both are watching SPCX like a hawk, because it is the live experiment in whether public markets will pay up for an unprofitable, narrative-driven moonshot at an enormous valuation.
We already flagged that the same concentration wave heading for Anthropic and OpenAI employees runs through this exact dynamic. And the broader tape is not encouraging: about a third of the companies that went public in the second quarter are now trading below their offer price, a pattern we covered in the AI deal and IPO concentration breakdown. If the marquee name of the cohort round-trips to its IPO price inside a month, that reprices the risk on every listing lined up behind it.
Thursday’s Starship flight is a loaded catalyst
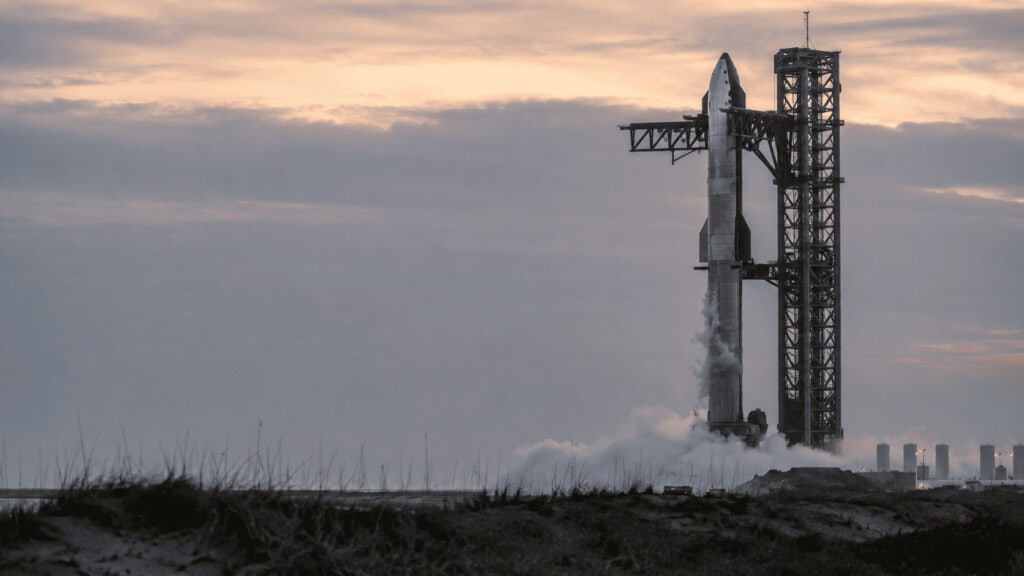
The timing is not subtle. On Thursday, SpaceX will test-launch Starship for the first time since the IPO, its 13th test flight and the first since a booster failure in May. The FAA has cleared the mishap probe, so the flight is a go.
Here is the trap. SpaceX does not plan to recover either the booster or the upper stage. Both are set to simulate a landing in the Gulf of Mexico, which means both will end in an explosion no matter what, even on a nominal flight. That is by design, the essence of the company’s “fly, fail, fix” philosophy. But a stock now trading on optics and a retail-heavy shareholder base do not always parse “planned explosion” and “failure” correctly. A textbook test flight could still look like a fireball on the evening news, and a genuinely bad day could get shrugged off as routine. On a 4% float, that interpretation gap is a volatility engine.
What to watch
The real tell over the next few sessions is not whether SPCX closes above or below $135 on any given day. It is whether the swings compress. Sustained tightening of the daily range would suggest the float is finding real hands and price discovery is maturing. Continued five-dollar lurches on headlines mean the stock is still a sentiment casino. Watch the bonds as the cleaner institutional signal, and treat the Starship reaction as a read on retail psychology more than on engineering.
The Business Model Analyst Take
The “SpaceX falls below its IPO price” headline is technically true and mostly a mirage. It was breached intraday and recovered the same session, so anyone framing it as a permanent break is already stale. The durable story is quieter and more important: a company floated 4% of itself, let a flood of attention do price discovery on a thimble of shares, and is now discovering that a valuation built entirely on narrative has no floor when the narrative wobbles. The $62-to-$800 analyst spread is not a bug in the coverage, it is the honest admission that there is no agreed way to value this yet.
For founders reading the tea leaves before their own raise or listing: the lesson from SpaceX is not “the market turned on Musk.” It is that a thin float plus a story-only valuation equals extreme fragility in both directions. You can engineer a euphoric debut by selling almost nothing into red-hot demand. What you cannot engineer is durable value on day 300. That gets earned in the financials, and the financials are exactly what this stock does not yet have to stand on. Anthropic and OpenAI should take notes, because they are next in line to run the same experiment.