
SpaceX’s first earnings report as a public company showed a rocket maker spending like a hyperscaler on a mid-cap’s revenue base. The market repriced the story between the closing bell and the after-hours print.
SpaceX reported second-quarter revenue of $7.8 billion on Tuesday, up 92% from a year earlier, in its first quarterly report since going public. The number that moved the stock was underneath the headline: capital expenditures hit $18.4 billion for the quarter, up from $2.8 billion a year ago. That is 2.36 times the revenue the company took in. Shares closed up more than 9% on the growth, then fell more than 8% after hours once the spending and the call sank in. The revenue and the capex got priced on two different clocks.
The tell was in the timing
On Tuesday, SpaceX stock closed up more than 9%. By the end of the after-hours session, it was down more than 8%. Same company, same day, same release. What changed in those few hours was which number investors were staring at.
During the regular session they saw revenue up 92%. After the analyst call, they saw an $18.4 billion capex bill, a company still losing money, and a CEO promising to launch data centers into orbit in 2027. The market spent the day pricing the growth and the evening pricing the burn. If you want the single cleanest read on how a public SpaceX is going to trade, that intraday reversal is it.
What happened
The SpaceX business model now reports in three segments, and the second-quarter release showed all three growing while only one of them earned anything.
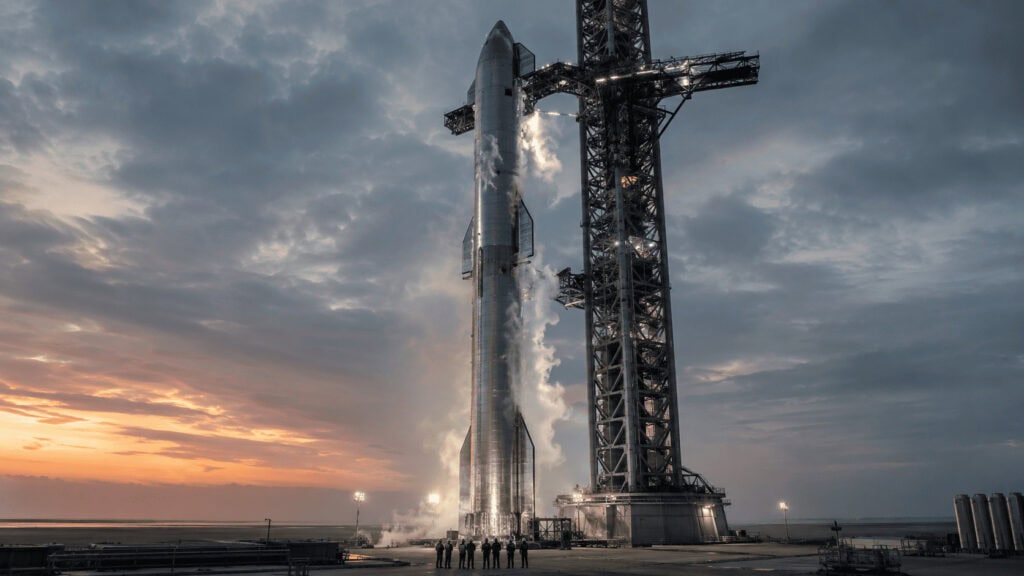
Connectivity, which is Starlink, stayed the anchor. Revenue came in at $4.3 billion, up 66% year over year, and subscribers doubled to 12 million. It was the only segment posting an operating profit. The AI segment, built on the February acquisition of xAI, more than tripled its revenue to $2.6 billion, which the company credited to new cloud service agreements. It is still under development and still burning. That leaves roughly $900 million of the quarter’s revenue for the Space business itself, the rockets that put the SpaceX name on the map.
Losses narrowed from the prior quarter, but the capex line did the opposite of narrow. And the mature Space unit kept landing the kind of contracts that don’t show up in a single quarter’s revenue: a $1.6 billion launch order from the Space Force in late July, on top of roughly $6.5 billion in national-security satellite deals earlier this year.
“Though I’ve been in this business for 24 years, I could not be more excited for the months ahead,” President Gwynne Shotwell told analysts. “It really feels like we’re just getting started all over again.”
The backstory
This is the first time anyone outside the cap table has seen the machine run. SpaceX priced its IPO at $135 a share in June, the largest offering in market history. The stock ran above $225 within days, then reversed. In recent weeks it slid below the IPO price and shed more than $1 trillion from the peak, a fall we tracked when the company aborted a Starship V3 test flight with the stock already underwater.
For years the pitch was simple: Starlink is a real, growing, subscription business, and everything else is the moonshot it pays for. As a private company, SpaceX could let that story run on its own timeline. The IPO handed the story a public clock. Tuesday was the first time the clock and the income statement met in the same room, and the room did not love what it saw.
The plan
Elon Musk used his first investor call to make the targets bigger, not smaller. He told analysts SpaceX could reach $1 trillion in revenue by 2030, pulling the goal forward a year from a previous 2031 projection. He said Starlink could deliver the majority of the world’s internet within a decade. And he committed to launching data centers in space starting in 2027.
The addressable-market math in the securities filings is its own genre. SpaceX pegged its total addressable market at $28.5 trillion, with roughly $26.5 trillion of that in AI. For reference, the entire U.S. economy is estimated at a little over $30 trillion. The company is telling investors its serviceable opportunity is nearly the size of the country it operates in.
Musk has a long record of naming targets his companies didn’t hit on schedule, and an equally long record of using those targets to drag an organization toward them. Investors have learned to hold both facts at once.
The business model angle
Here is the part the rocket footage hides, and the number no other outlet is putting next to its peers.
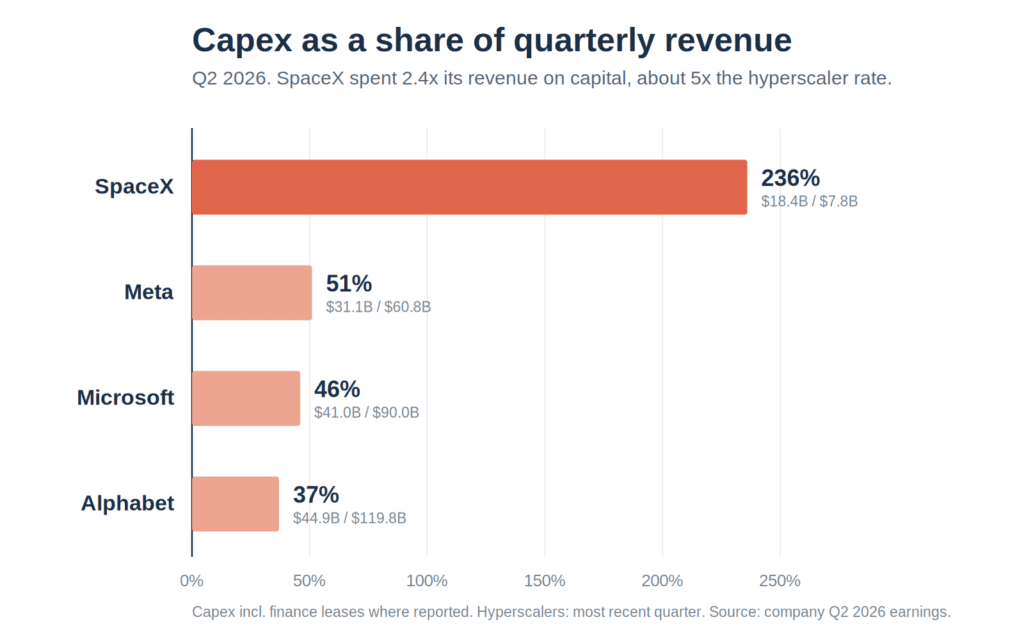
At $18.4 billion of capex on $7.8 billion of revenue, SpaceX spent 2.36 times its revenue on capital in a single quarter. Run that same ratio for the companies people actually call capital-intensive this earnings season and the gap is not close.
Alphabet spent $44.9 billion on $119.8 billion of revenue, a ratio of 0.38. Meta spent $31.1 billion on $60.8 billion, a ratio of 0.51. Microsoft spent $41 billion including finance leases on $90 billion, a ratio of 0.46. SpaceX is running capital intensity roughly five times the hyperscaler norm, on a revenue base a fraction of their size.
That reframes the whole quarter. The story is not “profitable core funds a frontier bet,” which is the frame the IPO ran on. The story is that SpaceX’s capital spending has decoupled from its revenue entirely. A year ago the company spent $2.8 billion in the quarter. This quarter it spent $18.4 billion, a 557% jump, while revenue grew 92%. Spending is now accelerating at six times the rate of the thing that is supposed to justify it.
And the spend is not spread evenly. Go back to the last disclosure with a segment breakdown: in the first quarter, the AI segment consumed $7.7 billion of capex against $818 million of its own revenue, roughly nine times its top line, while running a $2.46 billion operating loss. Connectivity, the only segment that earns, spent $1.33 billion. So the capex bill is overwhelmingly feeding the division that loses the most money, financed by the division that makes it. That is a defensible strategy for a private company with a patient cap table. It is a harder sell to a public market that just watched Alphabet get marked down for spending more cash than its core threw off, and that has spent this entire quarter repricing the most profitable software businesses on earth into capital-intensive infrastructure businesses.
The uncomfortable comparison: Alphabet, Meta, and Microsoft are pouring utility-scale capital into AI on top of businesses that print tens of billions in operating profit every quarter. SpaceX is matching their capital intensity and then some, with one profitable segment and a consolidated net loss.
The risk
Three risks stack up, and they compound.
The first is the growth math. SpaceX is annualizing around $31 billion in revenue. Getting to $1 trillion by 2030 means roughly 32 times growth in about four and a half years, a sustained compound rate north of 100% a year, every year, while the company is still losing money and pulling the target date forward. Ambitious targets are Musk’s tool of choice, but a public shareholder cannot spend a target.
The second is depreciation. Capital spent today becomes a depreciation charge tomorrow. $18.4 billion in a quarter, feeding hardware and data centers, turns into years of expense running through the income statement. If revenue does not grow into the buildout fast enough, that expense compresses margins for years. This is the same trap the market is already pricing into the hyperscalers, and SpaceX is carrying a heavier version of it. Whether the company is consistently profitable is still a live question, and the capex line is making it harder, not easier.
The third is supply. The Q2 print is also the starter’s gun on the staggered lockup that expands SpaceX’s tradable float. The first sell window opens two days after the report, and the unlock is triggered by this earnings event rather than the calendar. More shares hit the market into a stock that just fell after hours, with no passive index bid to absorb them. A disappointing print is a bad moment for supply to arrive.
None of this touches whether Starship works or whether orbital data centers are a good idea. It is narrower than that. A company priced on the future has little to fall back on when the present keeps spending faster than it earns.
Quick questions
How much did SpaceX make in Q2 2026? Revenue was $7.8 billion, up 92% year over year. The company narrowed its losses from the prior quarter but did not turn a consolidated profit.
Why did SpaceX stock fall if revenue beat? Revenue growth pushed the stock up more than 9% during the regular session. After the earnings call, capital expenditures of $18.4 billion and a still-unprofitable bottom line pushed shares down more than 8% after hours. The market priced the growth first and the spending second.
Which part of SpaceX actually makes money? Only the Connectivity segment, which is Starlink, posted an operating profit. It generated $4.3 billion in revenue with subscribers doubling to 12 million. The AI segment and the core Space business did not earn an operating profit in the quarter.
Is SpaceX really spending more than it earns? Yes. Capex of $18.4 billion was 2.36 times the quarter’s $7.8 billion in revenue. By comparison, Alphabet, Meta, and Microsoft each spent between 0.38 and 0.51 times their revenue on capital in their most recent quarters.
What is the $1 trillion revenue target? Musk told investors SpaceX could reach $1 trillion in annual revenue by 2030, a year earlier than a previous 2031 projection. It would require the company to grow revenue roughly 32 times from its current run rate.
The Business Model Analyst Take
Every founder who has ever raised on a vision should study Tuesday’s tape, because it is a live demonstration of what happens when a private story meets a public balance sheet. For years, SpaceX ran the best version of the cross-subsidy playbook: a real cash engine in Starlink, a spectacular narrative in Mars and AI, and no quarterly scoreboard forcing the two to reconcile. The IPO installed the scoreboard.
The lesson is not that spending is bad. The hyperscalers are spending too, and the market tolerates it because the money comes off businesses that gush operating profit. The lesson is about ratio and legibility. When your capital spending is five times the intensity of the companies famous for capital spending, and it lands on the segment that loses the most money, you are asking the market to underwrite a story with the size of the number itself. That works right up until it doesn’t, and the moment it stops working is visible in the gap between a nine percent close and an eight percent after-hours drop.
Starlink still pays the bills. Starship, Mars, and data centers in orbit still sell the story. What changed on Tuesday is that everyone can now see the invoice, quarterly, in public, forever. The number that matters is no longer the vision. It is the ratio of what you spend to what you earn, and for one afternoon the market did the division out loud.