The float triples this week. And a $175.50 trigger buried in the lockup filing shows exactly what SpaceX expected the stock to do.
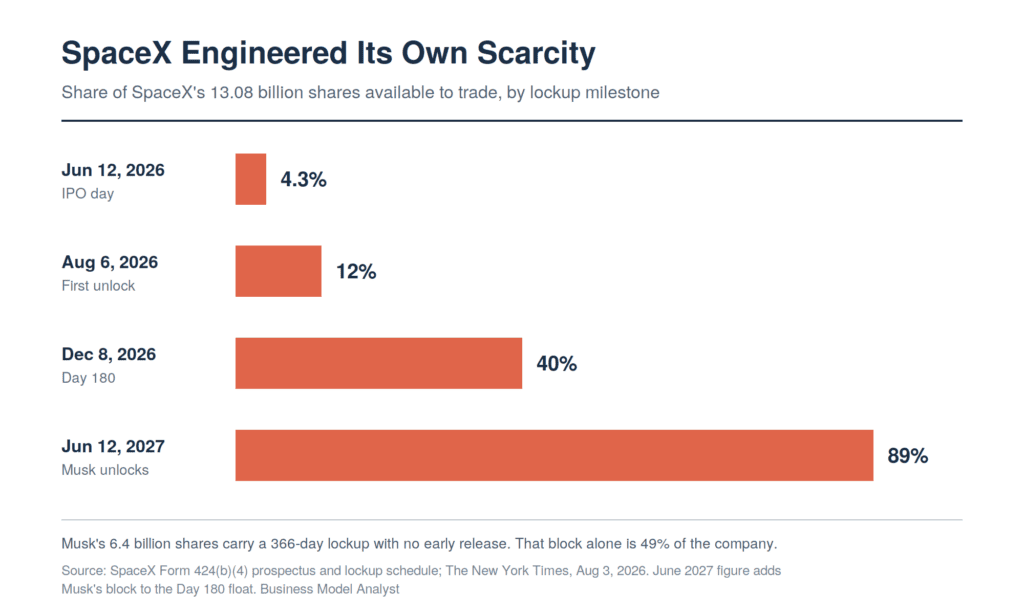
The short version: SpaceX raised $85.7 billion in June while releasing 4.3% of its shares to the public market. That sliver set a price for the whole company. On Thursday, roughly 911 million more shares become sellable, tripling the tradable supply two days after SpaceX reports earnings for the first time. The lockup schedule contains a clause that would have released 456 million extra shares had the stock traded above $175.50. It sits near $105 instead. The structure was built for a rally that never arrived.
Somewhere in a private Facebook group, a former SpaceX engineer is asking strangers whether to sell. He has more of his net worth in one stock than he wants. The replies tell him to hold and borrow against the shares instead.
About 1,200 people sit in that group. One member put their combined holdings at over a billion dollars. On Thursday morning, all of them can trade for the first time.
What Happened
SpaceX priced its IPO at $135 per share on June 11, 2026, and listed the next day under SPCX. The company sold 555.6 million shares and raised $85.7 billion, the largest initial public offering ever completed. Those shares represented 4.25% of the 13.08 billion outstanding.
The stock closed its first day at $161. Four days later it touched $225.64, valuing SpaceX near $2.66 trillion and turning Elon Musk into the first person on earth worth more than a trillion dollars.
Then it fell. SpaceX now trades near $105, roughly 53% below that peak and about 22% under the price public investors paid in June. Market value sits at $1.428 trillion. Musk is back to a reported $684 billion.
On Tuesday after the close, SpaceX reports quarterly results as a public company for the first time. Analysts expect revenue near $6.88 billion and a loss of about 23 cents per share. Management has issued no formal guidance, so the market is working entirely from sell-side models. Options traders are pricing a move of roughly 13% on the print.
Two days later, the first lockup tranche expires and about 911 million shares become eligible to sell.
The Backstory
Lockups exist to stop insiders from dumping stock into a young market. The standard version runs 180 days and expires on a single date. SpaceX wrote something more elaborate.
The company staggered its releases across roughly ten months and tied several of them to earnings dates rather than the calendar. The first window opens after the Q2 report. Another 7% releases at each of the 70, 90, 105, 120 and 135-day marks. After Q3 results in the fall, a further 28% unlocks, including the largest single tranche of 1.3 billion shares. Whatever remains frees up at day 180, around December 8.
Musk sits outside all of it. His 6.4 billion shares carry a 366-day lockup with no early-release provisions of any kind. He cannot sell the bulk of his stake until June 12, 2027. His control does not depend on selling anyway: Class B shares carry ten votes each, which gives him about 79% of the voting power on roughly 42% of the equity.
The Plan
Read the tranche structure as a document about expectations rather than a schedule, and one clause stands out.
The first release window carries a price condition. If SpaceX traded above $175.50 for five consecutive days, an additional 455.8 million shares would have unlocked alongside the base tranche. That provision only fires on the way up. Bankers and management wrote a mechanism that lets insiders sell more when the stock is strong, which is the polite way to manage supply: you meet demand at high prices instead of feeding a decline.
At $105, the clause is dormant. What remains is the base path, and the base path was designed as the floor case.
The same logic runs through the whole structure. Staggering releases spreads supply so no single date drops a wall of stock on the market. Reuters Breakingviews described the design as turning one large wave into several smaller ones. That works when buyers keep showing up between the waves. When they stop, a staggered lockup converts a single bad day into a rolling series of them stretching to next summer.
The Business Model Angle
The interesting thing about SpaceX’s $2 trillion moment is that no one ever paid $2 trillion for SpaceX.
Buyers paid for 4.25% of it. Public markets price the marginal share, and multiplying that marginal share by 13.08 billion produces a number that describes what the last buyer paid, not what the asset would clear at if it went on sale. With a float that thin, a modest amount of capital moves the print a long way. Retail flows, thematic ETFs and hedge funds all crowded into a supply that could not expand to meet them. Scarcity did most of the work on the way up.
Scarcity works in both directions. The 34% short interest that S3 Partners reports, worth roughly $25 billion, is a percentage of a tiny denominator. SpaceX is the eighth most shorted stock in the United States and the most shorted over the past 30 days. Some of that is a bearish view on the business. Some is a bet that a thin float mechanically unwinds when supply arrives.
Underneath the mechanics sits an income statement the public has never seen in full. SpaceX lost $4.9 billion in 2025 on $18.7 billion of revenue and another $4.28 billion in the first quarter of 2026. The SpaceX business model now runs three segments, and only one of them makes money. Connectivity, which is Starlink, produced $3.26 billion of revenue and $1.19 billion of operating income in Q1. The AI segment, built on the xAI merger in February, generated $818 million of revenue against a $2.46 billion operating loss while consuming $7.7 billion of capital expenditure in a single quarter. Space spent $1.05 billion. Connectivity spent $1.33 billion.
One division earns. Two spend, and the larger of the two spent nine times its own revenue in three months.
The company that filed for this IPO in May was already telling that story, as our breakdown of the filing laid out at the time, and the banks pitching a $3.4 trillion revenue forecast in June built their case on markets that do not exist yet. What changed is the audience. Private investors accepted the narrative because they had no daily price to argue with. Public investors get one every 6.5 hours.
The Risk
The supply arriving Thursday has no natural buyer waiting for it.
S&P Dow Jones Indices said on June 4 that it would not relax its inclusion rules for SpaceX. Membership requires GAAP profitability and twelve months of seasoning. SpaceX meets neither. Index funds are the largest mechanical, price-insensitive buyers in the market, and they are the usual absorbers of newly floated shares. SpaceX has locked itself out of that bid until it turns a profit, which means the entire tranche schedule releases into discretionary demand only.
That is the part missing from most coverage of Thursday. Patrick Corrigan of Notre Dame notes that lockup expirations produce an average 1.5% price decline. Jay Ritter at the University of Florida points out that a small float magnifies any swing. Both are true and both understate the situation, because the average lockup expiry lands on a stock that index funds can buy.
Three more pressures compound it. Starlink’s average revenue per user fell from $86 a month to $66 over the past year, and management expects further decline as it expands into lower-priced international markets, which means subscriber growth of 105% is doing more work than it appears. SpaceX trades near 49 times expected revenue. And Morgan Stanley’s Adam Jonas, whose bank underwrote the offering, holds a $300 target while conceding the stock could reach $100, attributing the gap to sentiment rather than any change in the business.
Matt Kennedy at Renaissance Capital placed SpaceX in the bottom third of 2026 US IPOs that raised at least $50 million. His summary of the setup: “Nobody wants to catch a falling knife.”
Quick Questions
Does the lockup expiry force insiders to sell? No. Eligibility is not obligation. Employees can hold, and commenters in those Facebook groups are already advising each other to borrow against shares rather than sell. Watch Form 4 filings in the days after August 6 for what insiders do rather than what they can do.
Why does SpaceX report earnings before the unlock instead of after? The filing ties the release window to the Q2 report. Insiders get audited numbers before the sell window opens, which is defensible from a disclosure standpoint and unusual as a design choice. Most companies keep the two events apart.
Is Musk selling? He cannot, on the bulk of his stake, until June 2027. His block has no early-release provision.
Does the December unlock matter more than this one? Yes. Thursday moves the float from about 4% to about 12%. Day 180 takes it near 40%. The August tranche is the test, not the event.
Is this a SpaceX problem or an IPO problem? Both. Anthropic and OpenAI are candidates to go public in the next twelve months, and every banker pitching them is now watching what a 4% float does when it stops being 4%.
The Business Model Analyst Take
SpaceX ran a strategy plenty of founders will recognize at smaller scale: restrict supply, let scarcity set the price, then release inventory into the demand that scarcity created. It works when demand holds. The design assumes it.
The tell is that $175.50 clause. Someone wrote a provision to release more stock into strength and left the base case to handle weakness. Companies do that when they have modeled the upside carefully and treated the downside as a formality. SpaceX is now running the formality.
Founders raising on a narrow slice of their cap table should take the specific lesson rather than the general one. A high valuation on 4% of your equity is a price for 4% of your equity. It tells you what one buyer would pay for a small position with no alternative supply. It does not tell you what your company is worth, and treating it as though it does builds a cost basis into your next round, your option strikes and your team’s expectations that the business may not support. SpaceX’s core business is real and growing: Starlink’s 10.3 million subscribers across 164 countries and its move toward retail mobile represent a genuine consumer utility with recurring revenue. The $60 billion Cursor acquisition bought real capability. None of that is what is being repriced this week.
What is being repriced is the difference between a number the market discovered on 4% of the shares and a number it will have to defend on 40%.
Thursday is the first payment on that difference.