
The largest acquisition of a venture-backed startup in history is all stock, and it only works because SpaceX just went public
SpaceX has agreed to buy Anysphere, the company behind AI coding tool Cursor, for $60 billion in an all-stock deal. It is the biggest acquisition of a venture-backed startup ever, nearly double Google’s $32 billion purchase of Wiz. The catch: the deal is funded entirely with SpaceX shares it could only print after its own record IPO. It closes in Q3 2026.
A rocket company is buying a code editor with stock it minted four days earlier. That sentence makes no sense until you add two facts most headlines skipped: SpaceX merged with Elon Musk’s AI venture xAI in February, and it just pulled off the largest IPO in history. Strip those out and this looks absurd. Put them back and it looks like the most aggressive use of fresh equity we have seen in years.
What Happened
On June 16, 2026, SpaceX exercised an option to acquire Anysphere, Cursor’s parent, in an all-stock transaction valuing the startup at $60 billion. Every share of Cursor stock converts into SpaceX Class A common stock, with the exchange ratio set by the volume-weighted average price of SpaceX shares over the seven trading days before close. The companies expect to finalize in the third quarter of 2026, pending regulatory approval.
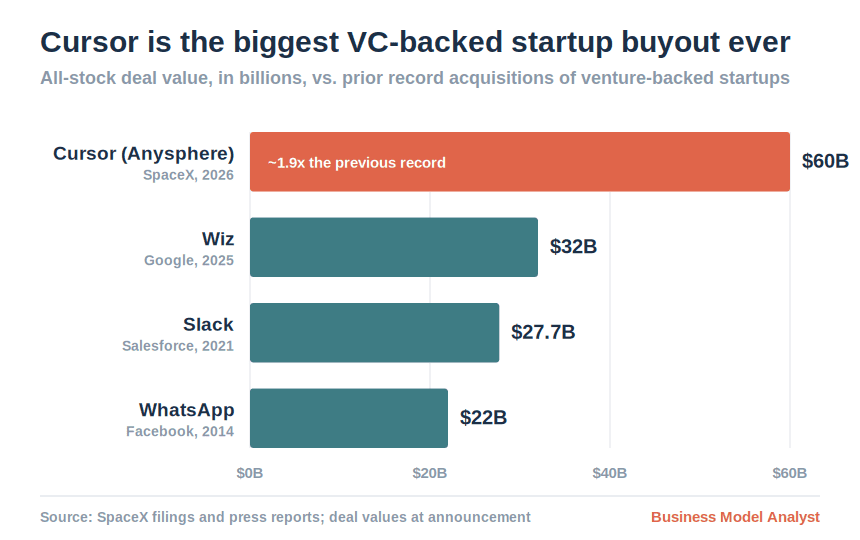
The number breaks the record. The previous high for a venture-backed startup acquisition was Google’s $32 billion deal for security firm Wiz in 2025. At $60 billion, this is roughly 1.9 times that.
| Deal at a glance | Detail |
|---|---|
| Buyer | SpaceX (post xAI merger, post IPO) |
| Target | Anysphere, maker of Cursor |
| Value | $60 billion |
| Structure | All stock, SpaceX Class A shares |
| Announced | June 16, 2026 |
| Expected close | Q3 2026, pending regulatory approval |
| Prior record | Google buys Wiz, $32 billion, 2025 |
The Backstory
This did not come out of nowhere. In April, the two sides signed a partnership that handed SpaceX an option: buy Cursor outright for $60 billion later in the year, or pay $10 billion for a collaboration if it walked away. June 16 was SpaceX pulling the trigger on the full buyout.
Cursor’s rise is the part that makes the price defensible to its backers. Founded in 2022, Anysphere hit $2 billion in annualized revenue by February 2026, which made it the fastest-growing business software company on record. Its November 2025 Series D raised $2.3 billion at a $29.3 billion valuation. In roughly seven months, the agreed price doubled.
The cofounders and early investors come out enormous. Forbes pegs each of the four cofounders near $2.7 billion at close. Andreessen Horowitz’s stake of around 10% translates to roughly $6 billion, and Thrive Capital’s position near 7% to about $4.2 billion. Nvidia and Google were also on the cap table.
The Plan
SpaceX is not buying Cursor to launch rockets. It is buying distribution and revenue for its AI arm. After the xAI merger, SpaceX owns Grok but trails Microsoft, Anthropic, and Google in the one enterprise AI market already generating real money: AI coding tools. Cursor is annualized at about $4 billion in revenue, roughly $2.6 billion of it from enterprise customers. That revenue lands on SpaceX’s top line, and Cursor gets folded into a company with its own compute and its own frontier model.
Worth noting who else wanted in. Microsoft examined a Cursor acquisition and passed without a formal bid. Cursor rebuffed two separate approaches from OpenAI. SpaceX won by offering something the others could not match cleanly: newly public stock at a sky-high valuation.
The Business Model Angle
Here is the part the size record hides. Cursor was growing fast and bleeding leverage at the same time. Per Ramp corporate spending data, its market share fell from roughly 41% in June 2025 to about 26% by May 2026, even as revenue climbed. That is the signature of a margin trap. Cursor’s product sits on top of frontier models from Anthropic and OpenAI, which means it pays model rent to the same companies whose tools increasingly compete with it. Grow the top line, hand a chunk of every dollar to your suppliers, and watch newer entrants undercut you.
SpaceX solves that with vertical integration. Owning xAI means Cursor can run on Grok and on SpaceX compute instead of renting from rivals. This is the same playbook Musk ran at Tesla: own the expensive input rather than buy it from someone who can squeeze you. For founders, the lesson is sharper than the headline number. A reseller business with no control over its core input is a tenant, not an owner, no matter how fast it grows. The exit valuation rewarded the growth. The strategic logic rewarded escaping the rent.
The financing model matters just as much. SpaceX could only do this because its record Nasdaq debut handed it a freshly liquid, richly valued currency. An all-stock megadeal is a way to spend a high share price without touching cash. The IPO was not just a liquidity event. It was a war chest denominated in equity.
The Risk
The bull case and the bear case share the same root: this is all SpaceX stock. If you think SpaceX is fairly valued at north of $2 trillion, $60 billion in shares is a reasonable price for a category-leading AI revenue stream. If you think the valuation is a narrative premium, then SpaceX is buying real revenue with possibly overpriced paper, and Cursor’s investors are the ones cashing the better end of the trade.
The deeper question is what xAI actually becomes. Skeptics, including short seller Jim Chanos, argue xAI is drifting from building frontier models toward selling raw compute, a commodity neocloud business the market values far lower than breakthrough tech. We covered that argument in detail in our breakdown of the SpaceX IPO skeptics. The financials give the bears ammunition: xAI lost $6.4 billion last year on $3.2 billion in revenue. Buying $4 billion of Cursor revenue helps the story, but it does not make the combined AI unit profitable.
There is also integration risk hiding in the plumbing. Reuters reported that SpaceX’s compute agreements carry 90-day termination clauses, which means the captive infrastructure thesis depends on choices SpaceX has not finalized. And the deal is not closed. Regulatory approval still stands between the announcement and the record.
| By the numbers | Figure |
|---|---|
| Deal value | $60 billion |
| Cursor annualized revenue | ~$4 billion (~$2.6B enterprise) |
| Implied revenue multiple | ~15x |
| Nov 2025 valuation | $29.3 billion |
| Market share, Jun 2025 to May 2026 | ~41% to ~26% (Ramp) |
| xAI last-year result | $6.4B loss on $3.2B revenue |
Quick Questions
How much is SpaceX paying for Cursor?
$60 billion, entirely in SpaceX Class A stock. It is the largest acquisition of a venture-backed startup ever, about 1.9 times the prior record set by Google’s $32 billion Wiz deal.
Why is a rocket company buying an AI coding tool?
SpaceX merged with Elon Musk’s AI venture xAI in February 2026. The Cursor deal gives that AI arm a leading position in enterprise AI coding, where it had been trailing Microsoft, Anthropic, and Google.
Is the deal final?
No. It was announced June 16, 2026, and is expected to close in the third quarter of 2026, subject to regulatory approval.
How is the price set since SpaceX shares move?
Each Cursor share converts to SpaceX Class A stock using the volume-weighted average price of SpaceX shares over the seven trading days before the deal closes.
What does Cursor get out of it?
Access to xAI’s Grok model and SpaceX compute, which lets it stop paying model rent to Anthropic and OpenAI, the rivals it has been built on top of.
The Business Model Analyst Take
The $60 billion record is the headline, but it is the least interesting number here. Two things make this deal worth studying. First, it is a textbook escape from a margin trap. Cursor was a fast-growing tenant paying rent to its own competitors, and slipping market share showed the squeeze was already on. Selling to a buyer that owns a frontier model and compute is how a reseller buys its way into ownership. Second, it is a masterclass in equity as a weapon. SpaceX could not have done this in cash, and it did not need to. A record IPO turned its share price into acquisition currency, and it spent that currency within a week.
The thing we would watch is whether the strategic logic survives contact with the income statement. Owning the input only pays off if Grok is genuinely competitive and SpaceX commits its compute to Cursor rather than renting it out to the highest bidder. If xAI keeps drifting toward commodity neocloud, this becomes an expensive revenue purchase dressed up as vertical integration. The record will stand either way. Whether it was smart depends entirely on what xAI decides to be. For the full picture of how the rockets, Starlink, and AI fit together, our SpaceX business model breakdown lays out the machinery underneath the story.
Reporting from CNBC, Reuters, Quartz, and Forbes. Deal terms per SpaceX’s filing.