
The brands were never the problem. Smucker’s slow, shelf-stable operating model could not run a fast, perishable, convenience-store business, and folding Hostess into its systems broke the very machine that made the acquisition worth buying.
In November 2023, J.M. Smucker closed a roughly $5 billion deal for Hostess, the maker of Twinkies, Ding Dongs and Donettes, and CEO Mark Smucker described biting into a Twinkie as tasting “like growth.” Less than three years later, Smucker has taken three separate impairment charges on the business totaling nearly $3 billion, its snack division has posted six straight quarters of falling sales, and activist investor Elliott Investment Management has taken two board seats. The headline is a $5 billion bet gone wrong. The real story is why it went wrong, and it is not the one most people assume.
Yes, the sweet-snack category is shrinking. But the deeper failure is structural: Smucker bought a company whose operating model was the opposite of its own, then integrated away the exact capabilities that made Hostess valuable. This is the business-model lesson every acquirer keeps having to relearn.
What Happened
Smucker’s Sweet Baked Snacks division, which houses Hostess, has now declined for six consecutive quarters and fallen well short of the projections Smucker made at the time of the deal. Over the past year the company has recorded three impairment charges tied to Hostess adding up to nearly $3 billion, an admission that a large slice of the $5 billion it paid no longer reflects what the business is worth. Smucker shares are down roughly 14% since the deal was announced in September 2023.
The financial reckoning peaked in the fiscal third quarter ended January 31, 2026, when Smucker booked a $962 million impairment on the Sweet Baked Snacks unit and Hostess trademark and reported a net loss of $6.79 per share. On the same day, it announced an agreement with Elliott that handed the hedge fund two board seats and an information-sharing arrangement. President and COO John Brase departed that February. Sweet Baked Snacks margins had fallen to roughly 5%, the weakest of any Smucker segment, and analysts began openly floating a divestiture as the cleanest fix.
The Backstory
When Smucker signed the deal in September 2023, the logic looked airtight. Hostess had grown net sales at a 14% compound annual rate over the prior three years, more than double its peers. The pandemic had supercharged snacking, with Smucker citing that around 70% of consumers ate at least two snacks a day. The acquisition opened a $65 billion snacking market and beat out rival suitors, most notably General Mills. Smucker paid $30 per share in cash plus a fraction of a Smucker share, and about 3,000 Hostess employees joined the company.
Then the macro turned. U.S. snack unit sales are down about 4% over four years, and sweet snacks specifically have dropped roughly 17%, according to NIQ data. GLP-1 weight-loss drugs and the “Make America Healthy Again” movement pulled consumers away from ultraprocessed indulgences. As BNP Paribas analyst Max Gumport put it, ultraprocessed food with no protein is doing badly, and the Twinkie sits at the center of that. Those headwinds are real. They are also not what separates this deal from a merely disappointing one.
The Business Model Angle
Here is the part the “snacking slowed” narrative misses. Hostess and Smucker are not the same kind of business wearing different labels. They run on opposite operating models, and Smucker tried to merge them anyway.
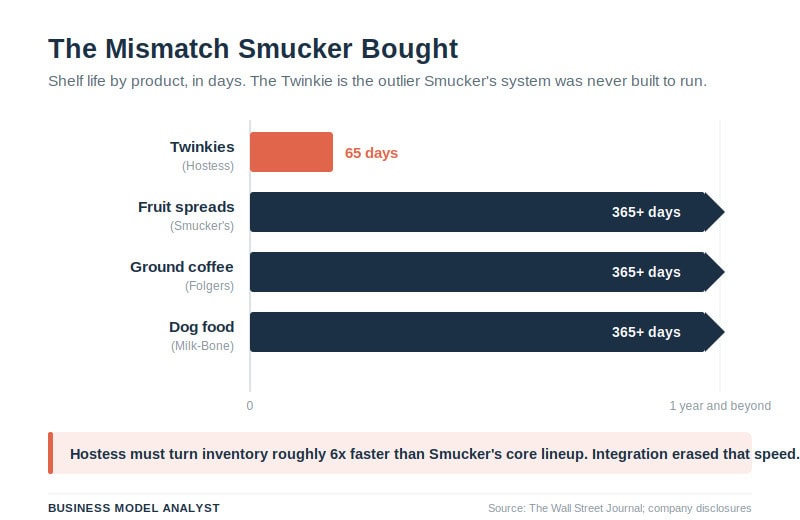
A Twinkie has a shelf life of about 65 days. Smucker’s core products, fruit spreads, canned coffee and dog food, last a year or more. That single number cascades into everything. Hostess had to turn inventory roughly six times faster, deliver on tighter cycles, and absorb far higher spoilage risk. Before the deal, Hostess ran its own Direct-To-Warehouse systems that controlled every step from a retailer’s order to production to shipping, and it stayed nimble: if a store ran short, employees could call a plant and divert a truckload of CupCakes on the fly. When Smucker folded Hostess into its slower systems built for shelf-stable goods, orders started arriving late and incomplete, and that agility disappeared.
The channel was the second mismatch. Smucker lives in the supermarket center aisle with Jif, Folgers and Meow Mix. Roughly 40% of Hostess sales happen in convenience stores, a different customer, a different buying rhythm, a different route to market. Smucker then split the Hostess sales team, separating the people who sold to grocery from those who sold to convenience, which made total demand harder to forecast. Hostess lost shelf space and display slots to competitors, and new-product rollouts, the lifeblood of a snack brand, slowed sharply. TD Cowen analyst Rob Moskow flagged exactly this: it was an entirely different route to market that Smucker was not prepared for.
Strip it down and the thesis is simple. Smucker paid $5 billion for brands, but a snack brand’s value lives inside its distribution and innovation engine, not just its logo. By imposing its own operating model on a business that required the reverse, Smucker degraded the engine and, with it, the asset. The nearly $3 billion writedown is the price of that lesson.
The Plan
To its credit, Smucker has stopped pretending nothing is wrong. Executives have delivered internal mea culpas, and the company has been rebuilding since 2024. It refreshed the Hostess logo and packaging, launched a marketing push aimed at millennials and Gen Z, and rolled out $1 donut and cake packs. It cut the Hostess lineup by 25% to concentrate on core brands like Donettes and CupCakes, added mini formats to sell “permissible indulgence,” reintroduced Suzy Qs and launched Fritter Rings. It closed an Indianapolis plant for about $30 million in annual savings and shed the smaller brands it inherited, selling Voortman cookies and Cloverhill pastries.
The early signals are mixed but improving. Donettes sales rose 13% in the latest quarter on more breakfast-time buying, and in June the sweet baked snacks division posted its first year-over-year profit increase since the deal. Sales declines are moderating. Smucker frames the goal plainly: stabilize first, and top-line growth later.
The Risk
The unresolved question is whether Smucker should own this business at all. With Elliott on the board, a track record of pushing divestitures, and Sweet Baked Snacks margins the thinnest in the portfolio, a sale of Hostess is a live possibility rather than a fringe scenario. If Smucker keeps it, the turnaround depends on repairing distribution and re-accelerating innovation inside a corporate structure that arguably caused the damage. If it sells, it likely does so at a steep loss to the $5 billion it paid, crystallizing the writedowns. Either path is expensive. The category headwinds, GLP-1s and the shift away from ultraprocessed snacks, are not going away, which caps how much upside even a clean operational fix can deliver.
Quick Questions
How much did Smucker pay for Hostess and when?
Roughly $5 billion (about $5.6 billion including debt), with the deal announced in September 2023 and closed on November 7, 2023.
How much has Smucker written off?
Nearly $3 billion across three impairment charges over the past year, including a $962 million charge in the quarter ended January 31, 2026.
Was it just the acquisition that hurt?
No. The whole packaged-food category is soft, with U.S. sweet-snack unit sales down about 17%. But Smucker’s integration missteps, on distribution, demand forecasting and innovation speed, turned an industry slowdown into a company-specific collapse.
Is Smucker going to sell Hostess?
No decision has been announced, but with Elliott on the board and the segment’s margins the weakest in the portfolio, analysts increasingly treat a divestiture as plausible.
The Business Model Analyst Take
The tidy version of this story is that Smucker had bad timing, buying a sugary-snack maker right as GLP-1s and the wellness wave hit. That version lets the acquirer off the hook, and it is wrong. Plenty of the damage was self-inflicted, and it traces to a single misjudgment: Smucker treated Hostess as a portfolio of brands to be absorbed, when Hostess was really an operating model, fast, perishable, convenience-led, innovation-driven, that happened to have brands attached.
In consumer packaged goods, M&A due diligence obsesses over brand equity, category growth and synergy math. The Hostess deal is a reminder that the harder question is capability compatibility: can the acquirer’s operating system actually run the target’s business without breaking it? Smucker’s answer, in hindsight, was no. The “synergy” of shared systems and a merged sales force was precisely what destroyed value, because it swapped a purpose-built machine for a general-purpose one. The counterintuitive move, and the one activist pressure may now force, is to run an acquired business on its own logic rather than the parent’s, or to not buy it at all. Nearly $3 billion says that lesson is not cheap. The brands were never the problem. The machine was.
Reporting drawn from The Wall Street Journal’s coverage of J.M. Smucker and Hostess, plus J.M. Smucker earnings disclosures, NIQ and BNP Paribas category data, and analyst commentary from TD Cowen and BNP Paribas.