
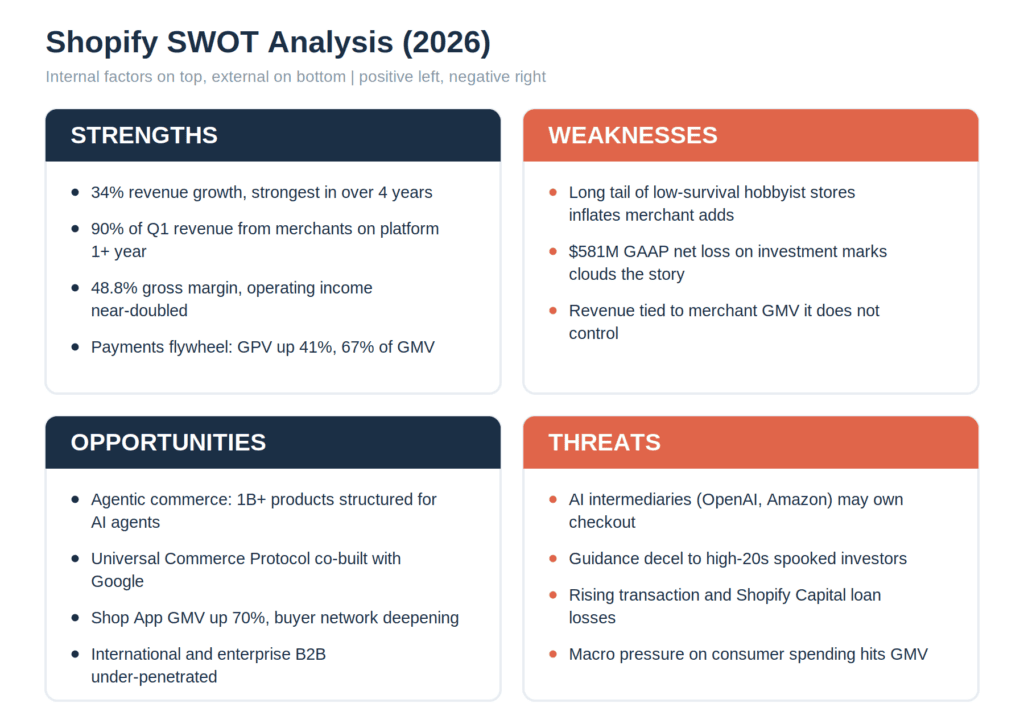
A SWOT analysis maps a company’s internal Strengths and Weaknesses against its external Opportunities and Threats. For Shopify, the 2026 picture shows a business growing 34% a year with fat cash flow, now fighting to stay the indispensable supplier to AI shopping agents rather than a backend they route around. This analysis breaks down all four quadrants using Shopify’s most recent financial results.
Shopify entered 2026 running faster than it had in four years. Revenue grew 34% to $3.17 billion in the first quarter, merchants pushed more than $100 billion through the platform in a single quarter, and operating income nearly doubled. Then management guided the next quarter down to high-twenties growth, and the stock fell 13.5% on the print. That gap between operating strength and market anxiety frames the whole SWOT.
Shopify sells commerce infrastructure to independent brands: online stores, payments, point-of-sale, capital, and a growing stack of AI tools. It earns money two ways, through recurring subscriptions and through merchant solutions that scale with how much its sellers actually sell. Understanding that second engine explains most of what follows. For the full mechanics, see our breakdown of the Shopify business model.
Shopify Financial Snapshot (Q1 2026)
Before the four quadrants, here is the scoreboard. Every figure below comes from Shopify’s Q1 2026 results for the quarter ended March 31, 2026.
| Metric | Q1 2026 | Change YoY |
|---|---|---|
| Total revenue | $3.17 billion | +34% |
| Merchant solutions revenue | $2.42 billion | +39% |
| Subscription solutions revenue | $750 million | +21% |
| Gross merchandise volume (GMV) | $100.7 billion | +35% |
| Gross profit | $1.55 billion (48.8% margin) | +32% |
| Operating income | $382 million | near-doubled |
| Free cash flow | $476 million (15% margin) | up |
| GAAP net result | $581 million loss | investment marks |
| Monthly recurring revenue | $212 million | up from $182M |
The one line that needs a footnote: the $581 million net loss came from a $1.08 billion loss on equity and other investments, not from operations. Strip that out and net income landed near $360 million. Hold that thought for the Weaknesses section, because it cuts both ways.
Strengths
Growth reaccelerated instead of fading. Most software companies at Shopify’s scale decelerate. Shopify did the opposite. Its 34% revenue growth was the fastest quarterly rate in more than four years, and it came from every direction: geographies, merchant sizes, and channels. President Harley Finkelstein noted that nearly 90% of Q1 revenue came from merchants who had been on the platform for over a year. That retention profile is the real moat. Shopify does not depend on a firehose of new signups to hit its numbers.
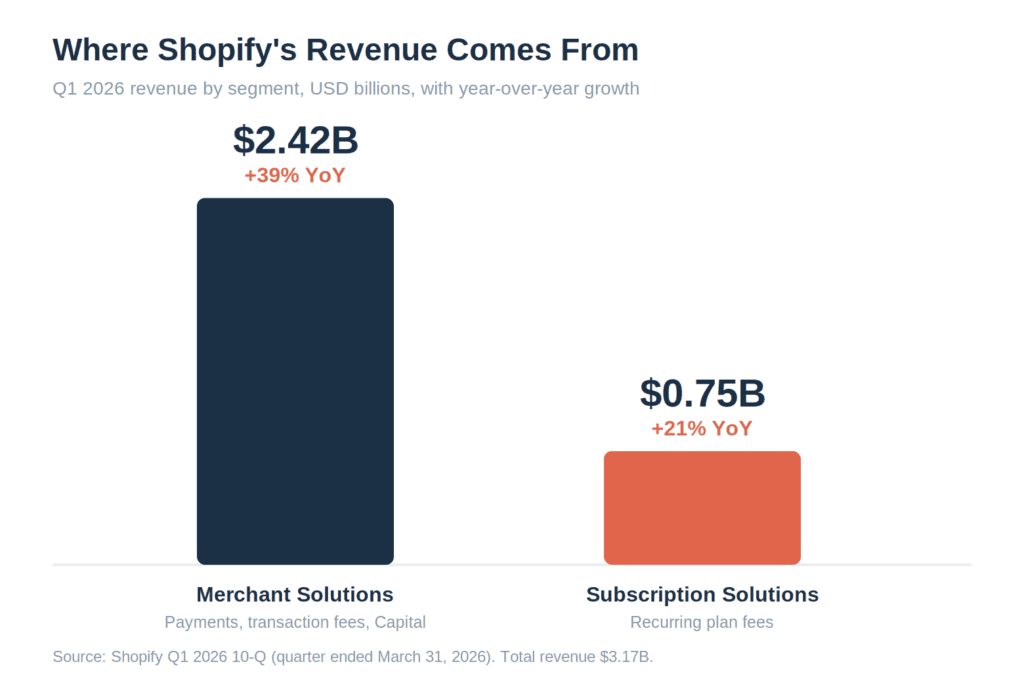
The merchant-solutions flywheel does the heavy lifting. Merchant solutions revenue grew 39% to $2.42 billion, its strongest showing in over four years, while subscriptions grew 21% to $750 million.
Payments sit at the center of that flywheel. Gross payments volume reached $67 billion in Q1, up 41%, and now covers 67% of all GMV, up from 60% two years earlier. Each additional point of payment penetration at this scale adds roughly $1 billion in annual payment volume. Shop Pay alone processed $35 billion, up 59%.
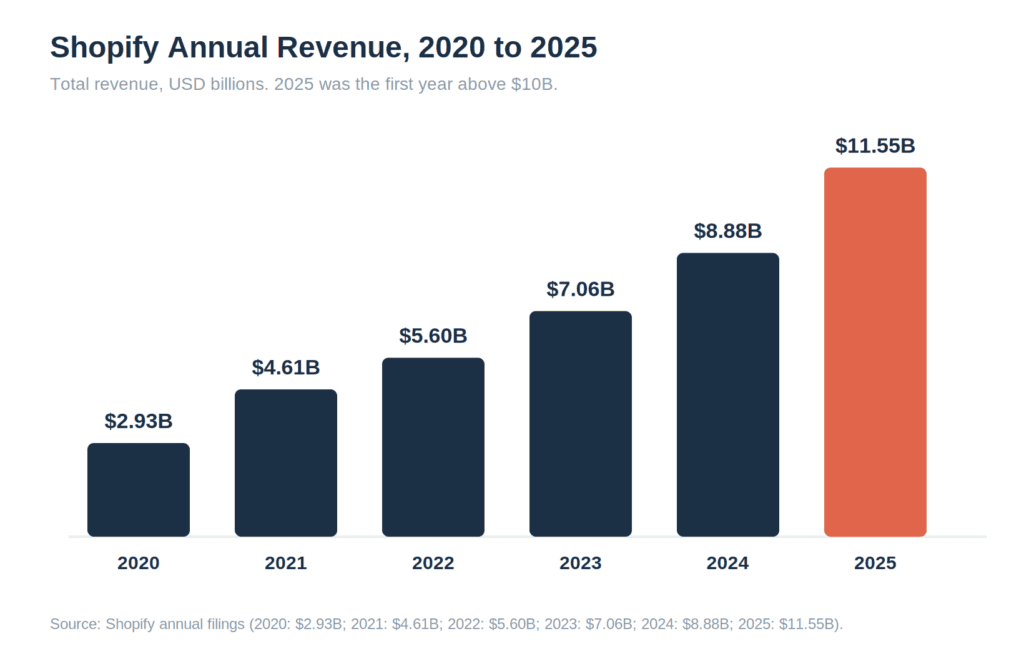
Scale compounds into pricing power. Shopify’s annual revenue crossed $10 billion for the first time in 2025 and has quadrupled since 2020.
Real operating leverage, not just top-line. Operating income nearly doubled to $382 million and free cash flow held a 15% margin. Management is keeping headcount flat while AI writes more than half of Shopify’s internal code. That combination, rising revenue against a fixed cost base, is what turns growth into cash.
Weaknesses
The long tail inflates the merchant count. Shopify powers millions of stores, and a large share are hobbyist or low-survival businesses that churn quietly. Gross merchant additions always look better than the durable base beneath them. The 90%-from-existing-cohorts figure is a strength, and it also signals dependence on a maturing base rather than blockbuster new-merchant economics.
GAAP optics stay noisy. The $581 million net loss was an investment mark-to-market artifact, not an operating failure. It complicates the equity story anyway. Shopify holds large stakes in companies like Affirm and Global-E, and every swing in those positions lands on the income statement, inviting volatility on each earnings print and giving skeptics an easy headline.
Revenue rides GMV the company does not control. As merchant solutions becomes the growth engine, Shopify’s revenue increasingly tracks how much its merchants sell. That works beautifully in a strong consumer economy. In a downturn, GMV softens, payment volume softens, and Shopify Capital loan losses rise at the same moment. The model concentrates macro risk rather than hedging it.
Opportunities
Agentic commerce is the next platform layer. AI agents placed roughly 20% of global online orders during the 2025 holiday window, worth about $262 billion. Shopify spent the past year rewriting its stack for that shift and has structured more than 1 billion products with clean attributes, real-time pricing, and accurate inventory so AI agents can surface them. Whoever supplies the cleanest catalog and checkout API to the agents wins, and Shopify is building to be that supplier. Our piece on how Shopify gamed AI chatbot rankings shows how aggressively the company is playing this game.
Owning the standard, not just a seat at the table. Shopify is co-developing the Universal Commerce Protocol with Google, with Amazon on the tech council. A shared open standard for agentic commerce lets Shopify sit at the center of the new plumbing instead of getting disintermediated by it.
The Shop App is becoming a destination. Shop App GMV grew 70% year over year. A consumer-facing surface that Shopify owns end to end gives it a demand channel independent of Google and Meta, plus first-party buyer data that its merchants alone cannot assemble.
International and enterprise remain underbuilt. Shopify still skews toward US small and mid-sized merchants. Europe and Asia-Pacific led Q1 growth, and Shopify Plus keeps moving upmarket into B2B and enterprise. Both lanes have years of runway.
Threats
The disintermediation paradox is the real danger. External AI agents that own product discovery and checkout threaten every retailer’s grip on the customer relationship and ad revenue. Shopify and Amazon have already restricted external agent activity inside their ecosystems for exactly this reason. Shopify gains from AI-driven demand and risks losing the transaction and the data that sit on top of it. This, not Amazon-the-marketplace, is the threat that matters.
Amazon plus OpenAI moved first on consumers. When OpenAI removed Instant Checkout and Amazon committed heavy investment, Forrester declared the pair might have won consumer agentic commerce. Shopify’s counter, launching Agentic Storefronts so every merchant’s products surface inside ChatGPT, is credible and unproven at scale.
The market prices perfection. Q2 guidance of high-twenties growth, down from 34%, was enough to drop the stock double digits despite a broad beat. Shares had already lost 21% for the year before the print. Any stumble gets punished hard.
Credit and macro exposure. Shopify flagged rising transaction and loan losses. Shopify Capital juices merchant growth and imports credit risk in the same motion. A weaker consumer hits GMV, payments, and lending together.
SWOT Summary Table
| Quadrant | Key Points |
|---|---|
| Strengths | 34% revenue growth; 90% of revenue from established merchants; 48.8% gross margin; payments at 67% of GMV; real operating leverage |
| Weaknesses | Long tail of low-survival stores; noisy GAAP losses from investment marks; revenue tied to merchant GMV it cannot control |
| Opportunities | Agentic commerce and 1B+ structured products; Universal Commerce Protocol with Google; Shop App up 70%; international and B2B runway |
| Threats | AI intermediaries owning checkout; Amazon plus OpenAI on consumers; perfection-priced stock; rising loan losses and macro risk |
Information Gain: The One Question That Decides Shopify’s Next Five Years
Most SWOT write-ups on Shopify make two lazy calls, and both mislead.
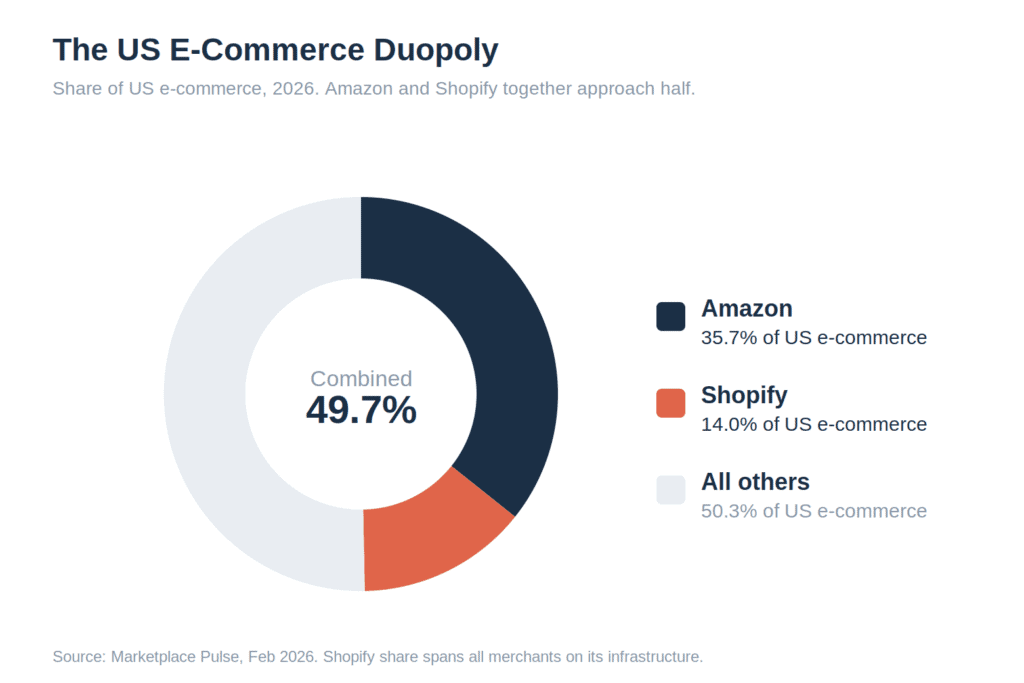
The first is treating “competition from Amazon” as the headline threat. Amazon is a marketplace. Shopify is infrastructure for brands that want to escape marketplaces and own their customers. The two are closer to complementary than zero-sum. Data backs this up: Amazon holds 35.7% of US e-commerce and Shopify about 14%, and the sharper competitive story of 2026 is not the split between them. It is whether AI intermediaries flatten the storefront into an API call and capture the buyer relationship on top of both.
The second lazy call is reading the GAAP net loss as financial weakness. It is a mark-to-market swing on Shopify’s investment book. The operating business generates cash at a 15% free cash flow margin. Anyone framing the $581 million loss as evidence of a broken model is reading the wrong line.
Strip both errors away and one question decides everything in the Opportunities and Threats columns. Does Shopify become the indispensable supplier to AI shopping agents, or a commoditized backend they route around? Its 1 billion structured products, its payments penetration, and the Universal Commerce Protocol are all bets on the first outcome. If Shopify wins that bet, the Threats column shrinks to macro noise. If it loses, the storefront becomes a low-margin utility and the whole valuation resets.
Shopify SWOT Analysis FAQ
Is Shopify profitable in 2026? On an operating basis, yes. Q1 2026 operating income reached $382 million and free cash flow was $476 million at a 15% margin. The reported $581 million net loss came from investment mark-downs, not operations. Excluding those, net income was around $360 million.
What is Shopify’s biggest competitive threat? AI intermediaries such as OpenAI and Amazon that could own product discovery and checkout, cutting Shopify off from the customer relationship and data. This matters more than competition from any single marketplace.
How much of US e-commerce does Shopify control? Roughly 14% of US e-commerce flows through Shopify’s infrastructure, per Marketplace Pulse. Combined with Amazon’s 35.7%, the two account for nearly half of all US online sales.
What is Shopify’s biggest strength? Revenue durability. Nearly 90% of quarterly revenue comes from merchants who have been on the platform for over a year, paired with a payments flywheel that now covers 67% of GMV.
What is the bull case versus the bear case? The bull case: Shopify becomes the default supplier to AI shopping agents and its cash generation compounds. The bear case: AI intermediaries commoditize the storefront and growth decelerates faster than the market expects. This is analysis, not investment advice.
The Business Model Analyst Take
Shopify is a rare thing: a company growing 34% at $12 billion in revenue while throwing off cash. The Strengths and Weaknesses columns are close to settled. What decides the next five years lives entirely in the tension between the Opportunities and Threats columns, and it reduces to one bet on agentic commerce.
Shopify has read the shift early. It restructured its stack, structured a billion products for AI agents, and pushed to co-own the industry standard rather than wait for one to be imposed. That is the correct move. It is also unproven, and the incumbents it is racing have deeper consumer distribution. For merchants and investors reading this SWOT, the takeaway is simple. Watch payment penetration and agent adoption, not the quarterly GAAP headline. Those two numbers will tell you whether Shopify stays the platform or becomes the plumbing.
For a related teardown of a payments-and-commerce rival, see our Square business model analysis.