
Regulators stopped taxing the value of Shein’s parcels and started taxing the variety inside them, which is the one thing Shein cannot cut
Shein told IPO investors this week that the tariff damage flattening its US business could spread to Europe, its largest market. The company is right to worry, but the reason is not the rate. The US, the EU and France have all shifted from taxing what a parcel is worth to taxing how many different things are in it. Shein’s entire model is built on maximizing how many different things are in it.
For three years Shein said the duty-free loophole had nothing to do with its success. The story was the supply chain: small batches of 100 units, thousands of new styles a day, an algorithm that read demand instead of forecasting it. The loophole was incidental. Then the loophole closed, and Shein’s own prospectus now says the removal of the US de minimis exemption hurt sales and slowed growth. The company argued the case for years and then wrote the rebuttal itself, in a document lawyers had to sign.
What Happened
In filings ahead of its Hong Kong listing, Shein disclosed that from May 2025 it passed most of the additional tariff burden to shoppers through higher prices, and that the increases weighed on US net revenues for the rest of the year. US revenue fell more than 3% from 2024 to 2025. In the most recent first quarter it fell 14.3%, to $2.04 billion from $2.38 billion.
The company then said Europe could go the same way. It is too early to assess fully, the filing said, but EU trends could broadly match or exceed what happened in the US. Europe generated $14.8 billion in 2025, 35.4% of total revenue, making it Shein’s biggest market by a wide margin. A Shein spokesperson declined to comment.
The rest of the numbers are the ones investors will price. Revenue reached $41.85 billion in 2025, up about 8% from $38.75 billion, on 273 million annual active customers and 1.078 billion fulfilled orders. Net profit fell 38.7%, to $2.064 billion from $3.365 billion. In the first quarter of 2026 Shein swung to a $99 million net loss against a $395 million profit a year earlier, including a $328 million non-cash fair-value charge on convertible preferred shares. Revenue for that quarter barely moved, up 1.1% to $9.05 billion.
To offset the slowdown, Shein is pushing brand enablement services, which let designers and brands rent its supply chain. That line grew about 40% in 2025 and still accounts for roughly 1% of sales.

The Backstory
De minimis was never mainly a duty subsidy. It was a paperwork subsidy. Under the old US rule, shipments under $800 could be released from manifest with minimal data, no formal entry, no 10-digit tariff classification, no broker, no bond. The duty saving was real. The administrative saving was structural, because it scaled with the number of distinct products, and Shein ships more distinct products than anyone.
That regime ended in stages. The US suspended de minimis for China in May 2025 and for all origins in August 2025. Then the ground moved again. On February 20, 2026 the Supreme Court held in Learning Resources v. Trump that the International Emergency Economic Powers Act does not authorize the president to impose tariffs, and collection of all IEEPA tariffs stopped on February 24. A same-day executive order re-based the de minimis suspension on separate authority so it survived, and CBP codified it in interim final rules in June 2026. A temporary 10% Section 122 surcharge covered the gap until it expired by operation of law on July 24, 2026, replaced the same minute by a new Section 301 forced-labor duty of 10% or 12.5% covering 60 trading partners, with China at 12.5%.
Read that sequence against Shein’s own disclosure. The prospectus describes China-origin goods facing tariffs of 10% to 87.5%, up from a prior range of 0% to 62.5%. The top of that range was built on an authority the Supreme Court voided in the middle of the very quarter Shein reported. The emergency layer on Chinese goods went from the IEEPA stack to 10% to 12.5%. The rate came down. US revenue kept falling.
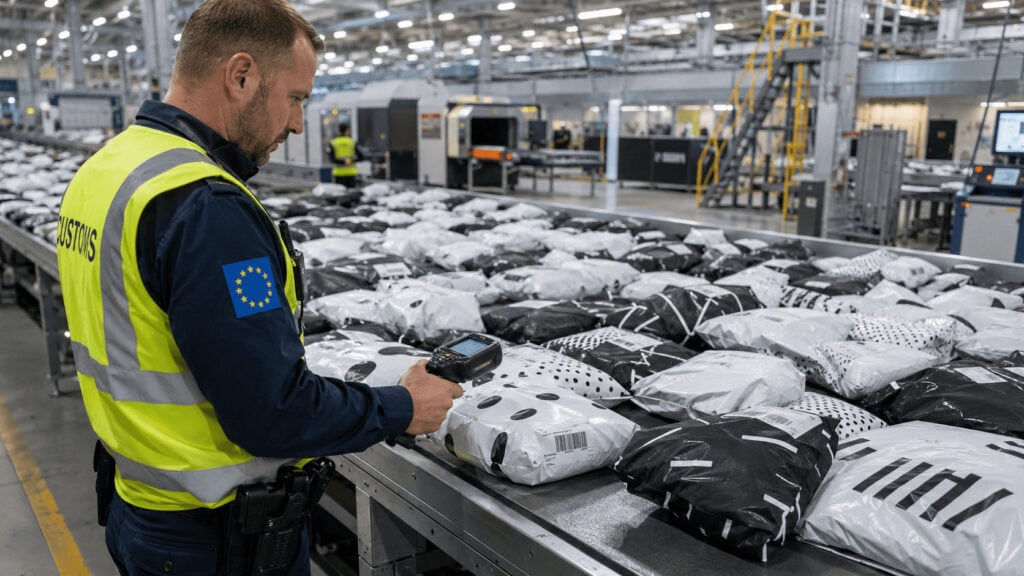
Europe is running the same play with a different instrument. On July 1, 2026 the EU suspended its 150 euro duty-free threshold and replaced it with a flat 3 euro customs duty, charged per tariff heading per parcel rather than per parcel or per item, in force until July 2028. The EU Council’s own worked example is blunt: ten pairs of identical socks incur 3 euros, five wool and five cotton incur 6 euros. France went further, adopting an ultra-fast-fashion law on June 29, 2026 that adds a per-garment environmental penalty, capped at half the item’s pre-tax price, with the ministry citing 9 euros on a pair of jeans in 2026 rising above 17 euros by 2030.
The Plan
Shein’s stated response is the one every platform in this position reaches for. Raise prices to recover the duty. Push higher-margin categories, which is why beauty and home have been gaining share of the mix. Grow brand enablement, where Shein rents out the supply chain instead of owning the inventory risk. Move fulfillment closer to the customer so parcels stop crossing borders one at a time. Raise IPO money at a $40 billion to $50 billion target valuation, with Goldman Sachs, Morgan Stanley and JPMorgan as joint sponsors, and spend it on technology, marketing and international expansion.
Local fulfillment is the serious item on that list, and it is also the one that changes the company. The EU’s own design rewards it: parcels handled through an in-bloc warehouse face a much lighter charge than parcels flown direct to the door. Shipping from a European warehouse is the rational answer to a per-heading border fee.
It is also the end of the model. Shein’s advantage was never speed alone. It was that speed came with no inventory risk, because nothing was committed until demand was observed. A batch of 100 units is a hypothesis. Forward-deploying stock into European warehouses converts hypotheses into commitments, at which point Shein is running the same working-capital problem as Zara and H&M, with worse brand pricing power and a longer supply line.
The Business Model Angle
Here is the arithmetic nobody in the coverage has run.
Shein’s gross margin went up through the tariff shock. It was 60.2% in 2023, 64.5% in 2024, and 67.9% in 2025. Net margin went the other way, from 8.7% to 4.9%. Apply those margins to the revenue line and gross profit grew from roughly $25.0 billion to roughly $28.4 billion, up 13.7%. Net income fell $1.3 billion. Everything sitting between gross profit and net income therefore grew from about $21.6 billion to about $26.4 billion, an increase of roughly $4.7 billion, or 21.8%, against revenue growth of 8.0%.
Costs below the gross profit line grew about 2.7 times faster than revenue.
That is the whole story in one ratio. A duty that lands in cost of goods crushes gross margin. Shein’s gross margin expanded. Some of that is genuine mix, because beauty and home carry better margins and the test-and-reorder model produces less clearance markdown, and that steelman deserves to stay on the table. But it also means the wound is not in the cost of the garment. It is in the cost of getting the garment across a border, one classification at a time, plus the marketing needed to defend a price point Shein no longer owns.
Now put a number on the European version. Shein’s 2025 net revenue divided by fulfilled orders gives an average order of $38.82. At 3 euros, or about $3.52, per tariff heading, a single-category order carries an effective duty of 9.1%. A basket with a top, a pair of leggings, a phone case and a lipstick carries four headings, or about $14.08, which is 36.3% of that average order. Five headings takes it past 45%.
The fee is flat in euros and therefore regressive in two directions at once. It punishes cheap baskets, and it punishes varied ones. Shein’s baskets are both.
That is the shift worth naming. A value-based tariff scales with what you sell. A classification-based fee scales with your assortment. Shein produces somewhere between 6,000 and 10,000 new styles a day and monetizes discovery, not repeat purchase of a known item. Its customers order roughly four times a year and spend about $153 across those orders. The browsing basket, the mixed cart, the impulse add-on, these are not side effects of the model. They are the model. Europe has now attached a fee to each additional category in the cart, and France has attached one to each garment.
You cannot cost-engineer your way out of a tax on your differentiator. You can only stop differentiating.
The Risk
The bear case is straightforward and Shein has already lived it once. The US is the proof of concept: revenue down 14.3% in a quarter, share of group revenue down from 29.4% in 2023 to 22.5%, and a price increase that did not come back to buy the customer back. Reference prices are sticky in one direction. Quietly walking a price down does not recover a shopper who left when it went up.
There is a real counterargument, and it is currently winning. Strip the US out of the first quarter and the rest of the world grew. Non-US revenue went from roughly $6.57 billion to roughly $7.01 billion, up about 6.7%, while the group grew 1.1%. Europe carried the quarter. Platforms have also proved adaptable: local warehousing and semi-managed seller models sidestep the per-parcel charge, and the fee is small in absolute terms. Shein may take share from European incumbents even while its own margin compresses.
The timing is the problem. That first quarter ended before any of the European measures existed. The EU fee started July 1, 2026. The French law was adopted June 29. The first quarter is the last clean read on the European business, and it is the read investors are being asked to buy at $40 billion to $50 billion.
Two more risks sit under the surface. Shein disclosed a US Federal Trade Commission investigation of unspecified scope with the possibility of significant fines. And more than 90% of 2025 net revenue came from goods held in central warehouses in China, which is the concentration that makes every one of these border measures bite at the same time rather than one market at a time.
There is also a question the prospectus does not answer. Since the Supreme Court ruling, CBP has been processing court-ordered IEEPA refunds. Capri Holdings collected $49 million through July 31. e.l.f. Beauty recognized about $50 million. Shein’s filing quantifies the harm from tariffs in detail. It is worth asking what, if anything, sits on the other side of that ledger, and who was the importer of record when those duties were paid.
Quick Questions
Did the Supreme Court ruling bring de minimis back? No. The Court held that IEEPA does not authorize tariffs. It did not address the suspension of the de minimis exemption. An executive order the same day moved the suspension onto different authority, and CBP codified it in June 2026. Separate legislation ends the exemption by statute in July 2027 regardless.
Are Shein’s US tariffs higher or lower than when it raised prices? The emergency layer is lower. The IEEPA tariffs stopped on February 24, 2026, a 10% Section 122 surcharge ran until July 24, and a Section 301 forced-labor duty of 12.5% on China took over the same day. Section 301 duties from earlier rounds and normal apparel duties still apply on top.
How does the EU’s 3 euro fee actually work? It replaced the 150 euro duty-free threshold on July 1, 2026 and is charged per tariff heading per parcel, not per parcel and not per item. Ten identical items in one heading pay once. Four different categories pay four times. It runs to July 2028.
Is Europe really Shein’s biggest market? Yes. Europe generated $14.8 billion in 2025, 35.4% of revenue. The US was 22.5% of first-quarter revenue, down from 29.4% of annual revenue in 2023.
What is brand enablement? Shein renting its supply chain and product infrastructure to outside designers and brands. It grew about 40% in 2025 and is about 1% of sales, so it is a direction rather than an offset.
The Business Model Analyst Take
Shein spent three years insisting the duty-free loophole was not the business. In the narrow sense it was telling the truth. The supply chain is real, the test-and-reorder machine is real, and the gross margin expanding from 60.2% to 67.9% through a trade war is not the signature of a company that only knew how to dodge customs.
The mistake was assuming the exemption was a discount. It was a permission. Duty-free entry was what made it economically sane to ship 1.078 billion parcels containing a near-infinite spread of tiny, cheap, unrelated items. Every regime that replaced it charges by the classification, the garment, or the entry. Each one prices assortment breadth directly.
That is a harder problem than a tariff, because a tariff is a number you can pass through and Shein already did, at a cost of 14.3% of its US revenue. A tax on variety is a tax on the product itself. The only compliant response is to sell fewer distinct things, in bigger batches, from local inventory, which is a description of a conventional apparel retailer.
For founders, the transferable lesson has nothing to do with fashion. Check whether your unit economics depend on a rule that was written for someone else. De minimis was designed for tourists mailing souvenirs home, not for a $42 billion company shipping three million parcels a day. When a business grows large enough to become the reason a rule gets rewritten, the rule gets rewritten around the business, and the rewrite targets the exact thing that made the business unusual. That is not a tail risk. That is the base case for anyone whose moat is an exemption.
The IPO is being marketed on a first quarter that ended before Europe changed the rules. Buyers are pricing the last clean quarter of a model that no longer exists.