
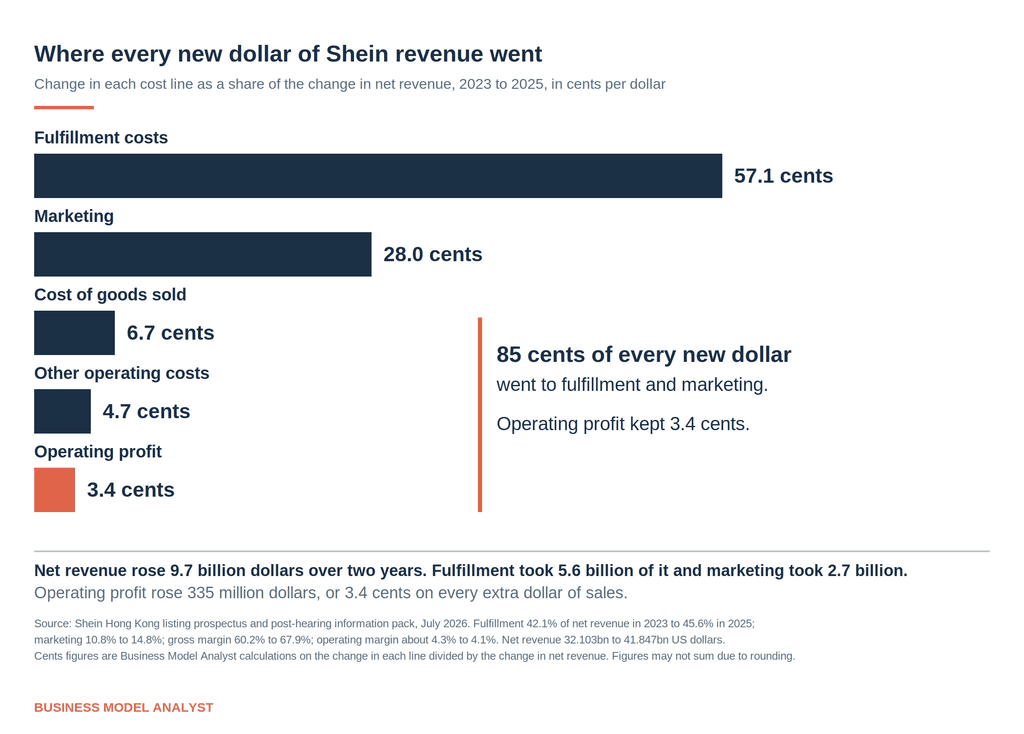
Shein raised $1.74 billion in Hong Kong at the midpoint of its range. Between 2023 and 2025, fulfillment and marketing absorbed 85 cents of every extra dollar of revenue it booked.
Shein priced its Hong Kong listing on August 31 at HK$48.56 a share, the midpoint of its marketed range, raising HK$13.60 billion, or about $1.74 billion, at a valuation near $26.5 billion. Shares begin trading September 1 under code 00625. The prospectus holds a number the price range does not. Net revenue grew $9.744 billion between 2023 and 2025. Fulfillment costs took $5.6 billion of that increase and marketing took $2.7 billion. Operating profit kept $335 million, which works out to 3.4 cents on every extra dollar of sales.
Buyers got one useful piece of evidence this week, and it came from a credit-card panel rather than the filing. Shein dropped off the list of top Google advertisers in December. US card spending on Shein fell. Shein restored its advertising budget in the second quarter and the spending came back, according to M Science analyst Vinci Zhang. The Wall Street Journal reads that sequence as a sign Shein can keep winning customers at higher prices as long as it keeps paying for them. That reading is fair. It also describes a company that rents its demand by the quarter.
What Happened
Shein offered roughly 280 million Class B shares. The Hong Kong public tranche was covered 5.63 times and the international tranche 2.59 times, a thin book for a deal this size on that exchange. Goldman Sachs, Morgan Stanley and JPMorgan sponsored the listing. Cornerstone investors committed about $383 million, led by existing backers Boyu Capital, Tiger Global and General Atlantic, with Tencent, Greenwoods, Taikang Life and UBS Asset Management joining.
The company told the exchange most of the proceeds go to technology, brand awareness and global presence.
Shein guided to first-half revenue growth broadly matching the 1.1% it reported for the first quarter, with the operating margin declining a little from there.
The Backstory
Shein failed in New York in 2023 and in London in 2025 before Beijing steered it to Hong Kong. Our earlier piece on Shein’s Hong Kong listing covered how far the mark fell and why the profit collapse, rather than the market, caused it. In July the company published audited financials for the first time. The picture: revenue of $32.103 billion in 2023, $38.748 billion in 2024 and $41.847 billion in 2025, with net income falling from $3.365 billion to $2.064 billion in the final year.
Two policy changes landed on top of that. Washington ended duty-free treatment for low-value parcels, and Brussels replaced the 150 euro threshold with a flat 3 euro charge levied per tariff heading per parcel from July 1. We covered the second one in detail in Shein Says Europe Is Next. First-quarter US revenue fell 14.3% to $2.04 billion.
The Plan
Shein wants to attract new customers and expand its category range. Both goals cost money on the same two lines that already absorb most of what the company earns.
The one genuine shift is the marketplace. Service revenue reached 14.3% of first-quarter 2026 revenue, up from 2.7% in 2023, and the Shein Xcelerator programme now rents the supply chain to outside brands. Twenty brands had joined by the end of 2025, generating about $580 million between them. Against $41.8 billion of group revenue, that is a rounding item with an interesting slope.
The Everlane acquisition, at about $80 million, sits in the same category. Real, small, and under US review that Shein initiated itself.
The Business Model Angle
Shein’s gross margin improved over the two years, from 60.2% to 67.9%. The company charges more per item and clears less of its stock at a discount. Everything downstream went the other way.
Fulfillment costs rose from 42.1% of net revenue in 2023 to 45.6% in 2025, and hit 47.7% in the first quarter of 2026. Marketing sat at 10.8% and 10.7% in 2023 and 2024, jumped to 14.8% in 2025, and reached 15.8% in the first quarter. Add the two lines together and they moved from 52.9% of revenue to 60.4%, then to 63.5%. That 7.5-point shift over two years is close to double the entire 2025 operating margin of 4.1%.
Divide 2025 by the 1.078 billion orders Shein fulfilled, and the model fits on one line.
| Per fulfilled order, 2025 | Amount |
|---|---|
| Net revenue | $38.82 |
| Gross profit at 67.9% | $26.36 |
| Less fulfillment at 45.6% | ($17.70) |
| Less marketing at 14.8% | ($5.75) |
| Remaining before other operating costs | $2.91 |
| Operating profit at 4.1% | $1.59 |
Shipping the parcel and buying the click that ordered it consume $23.45 of the $26.36 of gross profit sitting inside a $38.82 order. The 273 million active customers Shein reports bought 3.95 times each last year at $153 apiece. At 14.8% of revenue, Shein spent about $22.70 on marketing per active customer to get that.
None of this describes a company without a moat. The supply chain is real. Momentum Works reported that Chinese suppliers prefer Shein to Temu because it pays on time. Small-batch test-and-reorder still works. The moat sits on the cost side of the order, and the two lines that determine whether an order earns anything sit on the other side.
The Risk
Four arguments cut against the reading above, and one cuts against the bull case.
Duties inflate the fulfillment line without being a Shein cost failure. Shein passes most of the increase to shoppers, which raises revenue and the fulfillment line together. Strip the duty effect out and the operating story looks less like cost inflation and more like a tax on the whole category, one that Temu, Primark and H&M face in some form too.
The marketplace changes the mix. Service revenue at 14.3% of the first quarter carries different economics from first-party goods, and a company at 30% service revenue in three years would have a different cost curve than the one drawn here.
The 2024 base flatters nothing. Operating margin ran about 4.3% in 2023, dropped to 2.5% in 2024 and recovered to 4.1% in 2025. Measuring 2023 against 2025 skips the trough. A reader who prefers the 2024 to 2025 comparison gets a better incremental number.
The preferred overhang clears at listing. Shein committed up to about $3.5 billion in cash and shares to holders of its Series pre-D, D and D plus preferred stock, whose contracts triggered when the IPO priced below what they paid. The package runs to as much as $2.2 billion of cash under conversion adjustment protections at the bottom of the range, plus roughly $1.33 billion of separate payments and 19.6 million shares issued at no cost. Shein funds it from its own resources against a cash position near $14.8 billion at the end of March. Set that against a raise of $1.74 billion, which is roughly one year of 2025 operating profit, and the arithmetic is uncomfortable. The offsetting point is real: those rights terminate on completion, the $328 million non-cash charge that pushed Shein to a $99 million first-quarter loss goes with them, and 2026 earnings will look better without a single operational change.
Against the bull case, the growth left is in the cheapest markets. Rest of world reached $16.9 billion, or 40.5% of 2025 revenue, growing 15%. Those are the markets where JD.com, PDD’s Temu and Shopee compete hardest and where order values run lowest, which points the marketing line up rather than down.
Quick Questions
What did Shein actually price at? HK$48.56 per share, the midpoint of a HK$47.60 to HK$49.50 range, raising HK$13.60 billion or about $1.74 billion, valuing the company near $26.5 billion.
Is 13 times earnings cheap? It sits between Inditex at 29 times and PDD at 9 times. The multiple is not the open question. The durability of the earnings underneath it is, given that operating profit fell 26% in the first quarter to $258 million.
Why does the incremental figure matter more than the margin? The 4.1% margin averages a decade of orders written under old rules. The 3.4 cents measures what Shein kept from the growth it added after those rules changed. Investors buy the second number.
Does the marketing spend buy anything durable? Shein does not disclose repeat-purchase economics by cohort. The credit-card evidence points the other way: spending tracked the advertising budget down and back up within two quarters.
What should a reader watch first? The fulfillment and marketing lines in the first interim report as a listed company. If they hold at 63.5% of revenue while Europe absorbs a full period of the new parcel duty, the model has stabilised at a lower margin. If they keep climbing, growth is costing more than it returns.
The Business Model Analyst Take
Average margin describes the business you built. Incremental margin describes the business you are building. Shein’s average operating margin of 4.1% covers years of orders written when a parcel crossed the US border free and a click cost less. Its incremental margin over the past two years is 3.4 cents on the dollar, and the two lines eating the difference are the two lines its stated growth plan requires it to increase.
The transferable test for a founder is cheap to run and unpleasant to read. Take your revenue two years ago and your revenue now. Take each major cost line at both dates. Divide the change in each cost by the change in revenue. If your customer acquisition and delivery costs are eating more of the increment than they did of the base, you are buying growth rather than earning it, and the price goes up each year you keep buying.
The second test is harder. Turn the marketing off for a quarter and see what stays. Shein ran that experiment by accident in December and the answer arrived on a credit-card panel. Every business that acquires customers through paid channels is running the same experiment without measuring it. Knowing the answer before an investor finds it in your filing is worth more than the margin you are protecting by not looking.