
The market isn’t afraid AI will disrupt ServiceNow. It’s repricing what ServiceNow is becoming: a company trading its pristine software margins for an AI-native model that runs on someone else’s cloud.
The quick version: ServiceNow just posted another record quarter, raised its full-year forecast for the second time this year, and crossed $1 billion in AI contract value. The stock still trades around $111, roughly 43% below its high. CEO Bill McDermott says the market got it wrong and lumped a platform company in with vulnerable SaaS names out of “fear.” The more useful read is that the market got the direction right and the label wrong. This is not a fear trade. It is a business model in transition, and the transition changes the two things investors pay the most for: the quality of the growth and the shape of the margins.
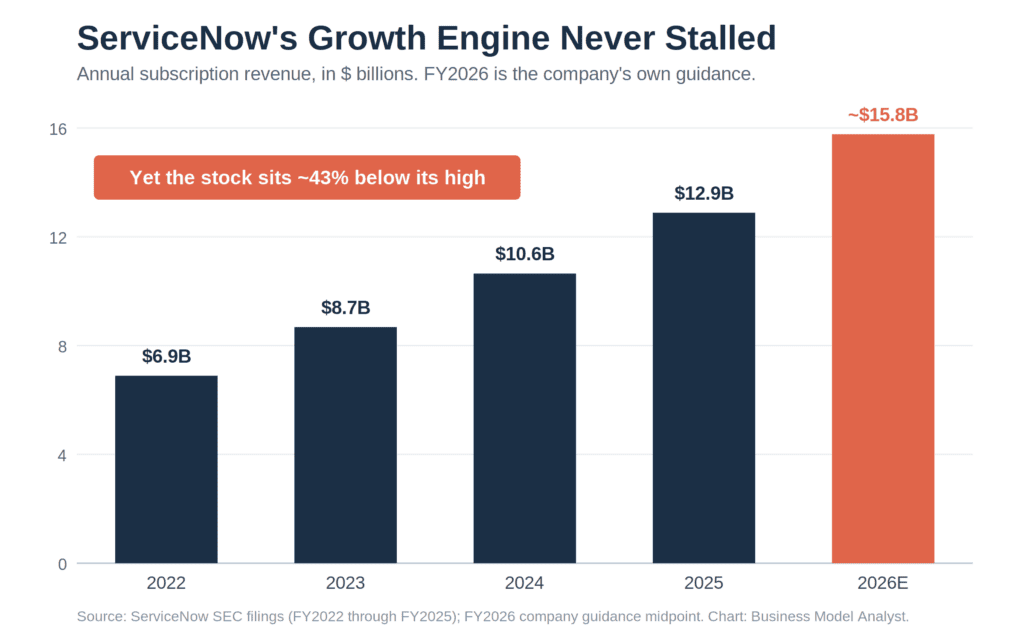
Here is a stat that should not compute. A company grows subscription revenue almost fivefold in four years, never posts a down quarter, keeps a 98% renewal rate, and beats its own guidance again. And the stock gets cut nearly in half. Either the market is broken, or it is pricing something the growth number does not show. It is the second one.
What Happened
ServiceNow reported second-quarter 2026 results on July 22. Subscription revenue hit $3.88 billion, up 24.5% year over year and 23% in constant currency, which was 150 basis points above the high end of its own guidance. Adjusted earnings came in at $0.90 a share against a $0.86 consensus. AI annual contract value crossed $1 billion. The renewal rate held at 98%. Management raised full-year subscription guidance to roughly $15.77 billion, the second increase of the year.
By almost any scorecard, that is a clean beat-and-raise. The stock fell 6.47% that day to close at $95.46 before clawing back some ground in later sessions to the $111 area McDermott referenced in his Friday interview with the Wall Street Journal. Zoom out and the damage is bigger: the shares sit around 43% below their 52-week high and down sharply on the year, even after a December 2025 five-for-one stock split reset the nominal price into the low hundreds.
Two numbers in the release explain the market’s shrug better than the headline beat. The Q3 subscription guide of $3.975 billion to $3.980 billion landed just under the roughly $4 billion Wall Street wanted. And ServiceNow flagged near-term gross margin pressure tied to rising AI usage. Those are the tells.
The Backstory
ServiceNow built one of the best businesses in software by doing something unglamorous extremely well. It sits on top of a company’s tangle of legacy systems and routes the work between them: IT tickets, HR requests, customer service, security operations. McDermott calls it the “control tower.” The classic pitch is that ServiceNow does not rip out your old systems, so it is easy to buy and hard to remove. That stickiness is why the renewal rate lives near 98% and why this looked like a textbook SaaS business model compounding machine.
The engine ran on seat-based pricing. Most of ServiceNow’s core products are billed per user, so revenue grew as customers added people and modules. High gross margins, predictable renewals, expanding contracts. That is the subscription business model at its most profitable, and for a decade the market paid a premium multiple for it.
Then generative AI arrived and put a question mark over the whole seat-based logic. If AI agents do the work a seat used to represent, does the seat count keep growing, or does it flatten? That question is what dragged down software valuations across the board, and ServiceNow got caught in the downdraft.
The Plan
McDermott’s answer is to run straight at the disruption rather than defend against it. ServiceNow has spent aggressively to reposition from a workflow-automation vendor into what it now brands the “AI control tower for business reinvention.” The acquisition list tells the story: Element AI in 2020, co-founded by Turing Award winner Yoshua Bengio; agentic-AI firm Moveworks for $2.85 billion; identity-security company Veza for around $1 billion; and cyber-exposure specialist Armis for $7.75 billion, its largest deal ever, which closed in April 2026.
The strategy is coherent. As AI agents multiply the number of identities and endpoints inside a company, someone has to govern and secure all of it. ServiceNow wants to be that layer, which is why it pushed hard into cybersecurity. It is also re-pricing itself, rolling out a new AI-native pricing model on July 1, 2026 that leans on consumption and outcomes rather than pure headcount. On the surface, that is exactly the bold, VC-style long-term bet the WSJ piece celebrated.
The Business Model Angle
Here is where McDermott’s “the market misunderstood us” framing starts to leak. He is right that ServiceNow is not a fragile point solution about to be vaporized. He is wrong that the derating is just fear. The market is pricing two concrete, unsentimental things.
First, the quality of the growth. That new July 1 pricing model triggered a wave of early renewals as customers locked in ahead of the change. Analysts at Jefferies and KeyBanc flagged that some of ServiceNow’s booking strength was pulled forward, meaning cRPO the company banked this quarter may be borrowed from next quarter. The soft Q3 guide is consistent with exactly that. When a company’s forward bookings look strong partly because it yanked demand forward, the strong number is worth less. This is the classic trap covered in BMA’s own breakdown of the hidden metrics for SaaS business models: the headline growth rate can look great while the underlying signal quietly degrades.
Second, and bigger, the shape of the margins. ServiceNow’s old seat-based software carried roughly 81% subscription gross margins because serving one more user costs almost nothing. AI is different. Every AI query runs on expensive hyperscaler compute that ServiceNow has to pay for, and management openly said gross margins face near-term pressure as AI adoption and hyperscaler partnerships scale. That is a structural shift, not a blip. A dollar of AI-native, consumption-linked revenue is worth less than a dollar of old seat-based revenue because it drags a fatter cost of goods behind it.
What is cRPO? Current remaining performance obligations. It is the contracted revenue a company expects to recognize over the next 12 months. Investors treat it as a cleaner leading indicator than reported revenue, which is why a pricing change that pulls renewals forward and inflates cRPO makes the metric harder to trust.
Put those together and the derating makes sense. The market is not saying ServiceNow will shrink. It is saying that an AI-native ServiceNow, with slightly lower-quality near-term bookings and structurally lower gross margins, does not deserve the same premium multiple as the pristine seat-based ServiceNow of 2023. That is a repricing of the model, not a panic about its survival.
The Risk
The bull case is genuinely strong, which is why this is a debate and not a verdict. AI ACV crossed $1 billion and net-new AI bookings accelerated more than 40% quarter over quarter. The control-tower position sitting astride a company’s legacy systems is a real moat, and the cybersecurity land grab gives ServiceNow a second large growth vector while security spending climbs. If the AI-native model scales and margins recover as McDermott promises, today’s price looks like a gift.
But the risks are just as concrete. There is enterprise “do it yourself” risk, dramatized this year when Starbucks talked up building AI in-house rather than buying it. There is integration risk in swallowing $12 billion of acquisitions in eighteen months from a company that insists it “never set out to buy revenue,” even as it paid roughly 22 times ARR for Armis. And there is the near-term margin drag that will keep showing up in the numbers before any recovery does. The market tends to sell first and re-underwrite later.
Quick Questions
Is ServiceNow in trouble? No. It is growing subscription revenue above 20% with a 98% renewal rate. The stock fell because the multiple compressed, not because the business did.
So why did the stock drop so much? A mix of pulled-forward bookings from the July pricing change, a soft next-quarter guide, and structurally lower margins as revenue shifts from seat-based software toward consumption-based AI.
Is McDermott right that the market misjudged the company? Half right. ServiceNow is not a fragile SaaS point solution. But calling a legitimate repricing of its margin structure “fear” is a CEO defending his stock, not a full explanation.
Does the AI strategy actually make sense? Strategically, yes. It moves ServiceNow toward where enterprise AI value is heading. The open question is whether it can do that while keeping software-like profitability.
The Business Model Analyst Take
The WSJ framed this as a story about brave CEOs thinking like venture capitalists. The real story is quieter and more important for anyone who builds or values a software company: what happens to a great SaaS business when it bolts an AI engine onto a seat-based model.
The answer, at least in the transition, is that it trades margin certainty for growth optionality. ServiceNow is deliberately swapping a pristine, high-margin, predictable revenue stream for a bigger but messier one that runs on rented compute and gets priced on consumption. That can absolutely be the right call. It is also, unavoidably, worth a lower multiple until the new model proves it can hold the old margins. Wall Street is not confused about ServiceNow. It is simply refusing to pay 2023 prices for a 2026 business model. McDermott may well be proven right over five years. Over the next four quarters, the market is asking a fair question, and “vision has to supersede fear” is not an answer to it.
Sources: ServiceNow Q2 2026 results and SEC filings; The Wall Street Journal, “How ServiceNow’s CEO Weighs Long-Term Bets” (Aug. 3, 2026); company acquisition announcements for Armis, Veza, Moveworks and Element AI; analyst notes from Jefferies and KeyBanc as reported.