
For twenty years ServiceNow grew by building every new product itself and selling it to a customer it already had. In eighteen months it spent $11.8 billion buying products instead, and the receipt is a balance sheet that flipped from $8.6 billion of net cash to net debt.
ServiceNow sells workflow software to about 8,400 large organizations, including more than 85% of the Fortune 500. It will collect roughly $15.77 billion of subscription revenue in 2026, renews 98% of its contracts, and has told investors it intends to double again to more than $30 billion by 2030. Almost every write-up of the company stops there, at a platform business with an unusually loyal customer list.
That description is now out of date, and the place it breaks is not the income statement. It is the cash flow statement.
Definition Box: the ServiceNow business model
What it sells: subscriptions to a single cloud platform that sits above an enterprise’s existing systems and routes work across them, sold department by department (IT service management, IT operations, security and risk, HR, customer service, application development, CRM).
Who pays: a narrow set of very large organizations. Roughly a quarter of ServiceNow’s customers carry close to nine tenths of its contract value.
How the meter runs: historically a per-seat license for “fulfillers,” the employees who do work in the system, multiplied by a platform edition and added up across product lines. Since 2025, increasingly a consumption charge for AI usage instead.
Where growth comes from: not new logos. Customers renew at 98% on roughly three-year contracts and buy more product lines at each renewal. ServiceNow says 91% of its 2025 net new annual contract value came from deals containing five or more products.
What changed in 2026: the company began buying the products it cross-sells rather than building them, funded by its first meaningful borrowing, and began metering AI rather than licensing it.
How ServiceNow actually charges
The price card has three layers that multiply against each other, which is why contract values climb without any single price rising much.
| Layer | What it is | How it scales |
|---|---|---|
| Fulfiller seats | Licensed users who create, own or resolve work in the platform. Requesters and approvers are bundled at no seat cost. | Per user, per month. Independent licensing advisers put small deployments around $100 to $200 and large volume bands around $38 to $90. |
| Product lines | ITSM, ITOM, ITAM, security operations, HR, CSM and the rest, each a separate subscription line. | Each line is priced against the same fulfiller population, so adding a department multiplies the bill. |
| Platform edition | The tier the whole account sits on, historically Standard, Professional or Enterprise. | An uplift applied across the entire fulfiller count. |
| AI consumption | Since 2025, “assists,” a usage unit drawn from a contracted monthly pool with overage above it. | Metered. ServiceNow’s own June 2026 guidance sets an agentic execution using up to four tools at 25 assists, five to eight tools at 50, and nine to twenty at 150. |
ServiceNow does not publish a rate card, so the per-seat figures above come from licensing advisory firms rather than the company. The structure, though, is the point. A customer that adds a second department does not pay a second small subscription. It pays the fulfiller rate again, multiplied by the same edition uplift, on the same platform it has already standardized on.
That is the engine. Everything else in the model exists to keep it turning.
The customer base is small, rich, and quietly disclosed
ServiceNow’s last clean disclosure of its core customer cohort came in the fourth quarter of 2024, when it reported 2,109 customers with more than $1 million in annual contract value, up 12% year over year. Its quarterly investor materials put the average contract for that group at $5.0 million.
Multiply those and the cohort held roughly $10.5 billion of contract value. ServiceNow recognized $10,646 million of subscription revenue that same year.
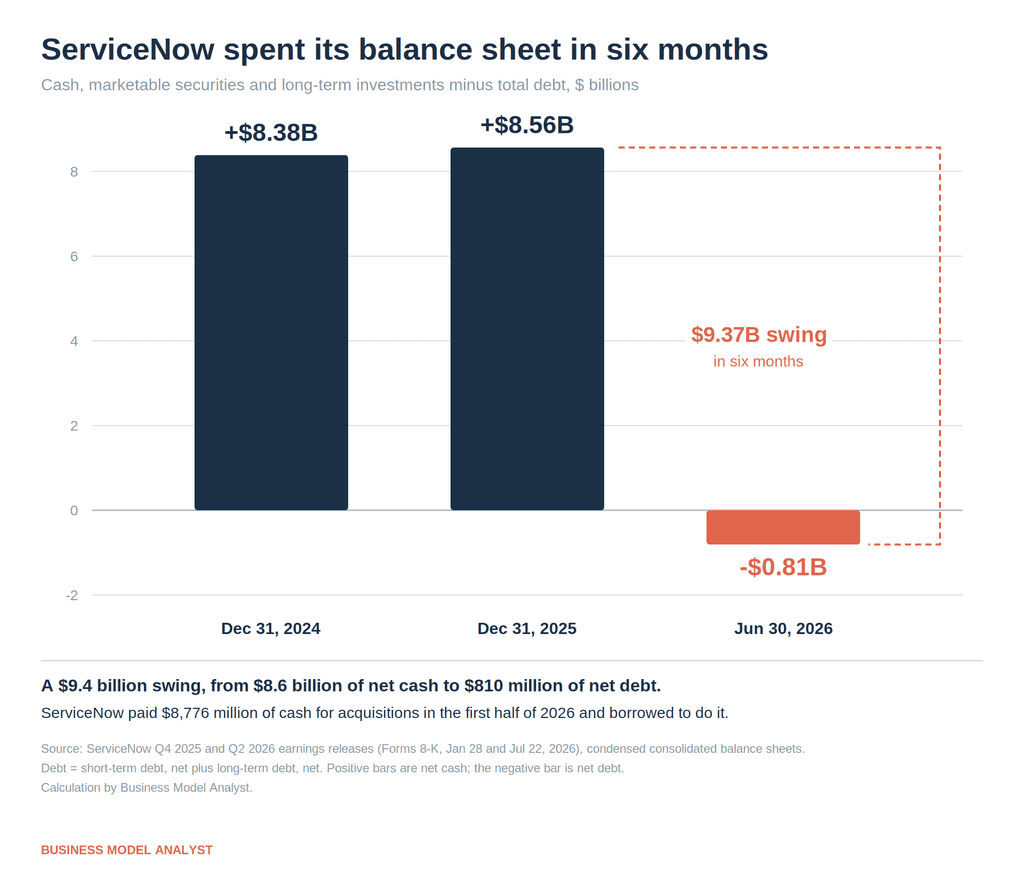
The two figures are different measures, and year-end contract value normally runs ahead of the revenue recognized during that year in a business growing 20%. Even allowing for that, the arithmetic is stark. Assume the remaining 6,291 customers average somewhere between $100,000 and $250,000 each and the $1 million cohort accounts for 87% to 94% of the entire contract base while making up 25% of the customer list.
Three quarters of ServiceNow’s customers are, financially speaking, decoration.
Then the disclosure moved. ServiceNow reported the $1 million tier for the last time in the fourth quarter of 2024, at which point its growth had slowed to 12%. The headline metric became customers above $5 million, which was growing about 21%. As that tier matured, the releases began leaning on customers above $20 million, then above $50 million, both growing more than 30%. The reported growth rate of “customers” turns out to depend heavily on which threshold the company chooses to print.
The expansion engine
What ServiceNow does have is the best renewal profile in enterprise software. The 10-K reports a 98% renewal rate for each of 2023, 2024 and 2025, on subscription arrangements that typically run three years. The single quarterly wobble is instructive: the rate printed 97% in the third quarter of 2025, and ServiceNow noted it would have been 98% excluding the closure of a large US federal agency. The customer did not leave. It ceased to exist.
Retention on its own does not produce 20% growth. Cross-sell does. ServiceNow told its May 2026 analyst day that 91% of 2025 net new annual contract value came from deals containing five or more products, and that customers who had bought its Now Assist AI products expanded their contract value by an average of three times at renewal. It now runs twelve product lines above $100 million in contract value, with security and risk crossing $1 billion in 2025 and CRM crossing $1.8 billion.
The model, stated plainly: acquire a large customer once, then spend the next decade selling it additional departments at renewal. The sales motion is closer to renegotiation than to hunting.
That works for exactly as long as ServiceNow has new things to put in front of the same buyer.
What changed, part one: the growth is now purchased
In 2024 ServiceNow spent $113 million of cash on acquisitions. In the first half of 2026 it spent $8,776 million.
| Deal | Announced | Price | Status |
|---|---|---|---|
| Moveworks | March 2025 | $2.85 billion ($2.61bn cash, $0.24bn stock) | Closed December 15, 2025 |
| Veza | December 2, 2025 | About $1.2 billion, substantially cash | Closed March 2, 2026 |
| Armis | December 23, 2025 | $7.75 billion cash | Closed April 2026 |
Armis is the largest acquisition in ServiceNow’s history by a wide margin, roughly three times the next biggest, and the company said openly that it would fund the deal through a combination of cash on hand and debt. It did. The first half of 2026 financing activity shows $3,944 million of senior notes issued net of costs, a $3,991 million term loan drawn and $4,000 million repaid, and a commercial paper program that issued $3,534 million and repaid $1,472 million. A company that had carried a static $1.49 billion of long-term debt for two years now runs short-term paper.
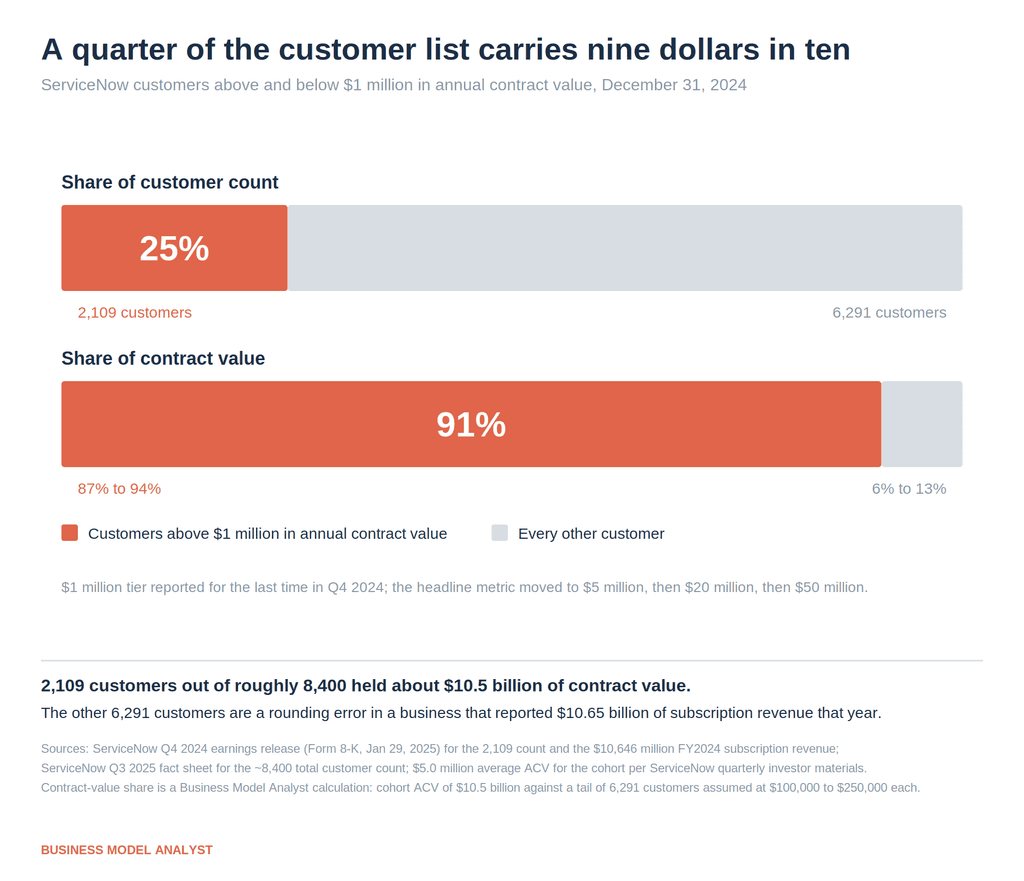
Cash, marketable securities and long-term investments came to $10,055 million at the end of 2025 against $1,491 million of debt, a net cash position of $8,564 million. Six months later liquid assets were $6,707 million and total debt was $7,517 million. Net debt of $810 million. A $9.37 billion swing in two quarters.
The same shift shows up in what ServiceNow now owns. Goodwill and acquired intangibles were $1,482 million at the end of 2024, 15% of shareholders’ equity. At June 30, 2026 they were $13,618 million against equity of $12,516 million. Purchased assets now exceed the entire book value of the company.
There is a reason to do this, and it is visible in the guidance. ServiceNow’s third-quarter 2026 outlook calls for 20% constant-currency subscription growth including roughly 175 basis points of contribution from Armis, which puts the underlying rate near 18.25%. Full-year 2025 grew 20.5% in constant currency including about 100 basis points from Moveworks, an underlying rate near 19.5%. The organic line is drifting down. The acquisitions are what hold the headline in place.
What changed, part two: the meter
The second break with the old model got far less attention. At its May 2026 analyst day ServiceNow disclosed that more than half of its net new business is no longer priced per seat.
In April 2026 the company retired its long-standing ITSM tiers, Standard, Professional, Pro Plus and Enterprise, and replaced them with three AI-native tiers. Now Assist, which had been sold as the Pro Plus upsell at a reported 50% to 60% uplift on the base license, was folded into every tier. In its place sits the assists pool, a consumption allowance with overage charges above it. ServiceNow told investors the new bundles should deliver an average price lift of 20% to 30%.
Read the two changes together and they describe one decision. ServiceNow bills against the number of people who work in its system. If AI does what its customers hope, that number stops growing. So the company added a second meter that runs on machine activity rather than headcount, and it did so before it had to.
AI contract value crossed $1 billion in the second quarter of 2026, up from $600 million at the end of 2025. Management raised the 2026 target to $1.5 billion and expects AI to be more than 30% of total contract value by 2030. On a $30 billion subscription base that implies about $9 billion of AI contract value, roughly nine times today’s level in four and a half years.
What the model costs to run
The quiet story of 2026 is that ServiceNow raised its revenue guidance and cut every profitability line in the same year.
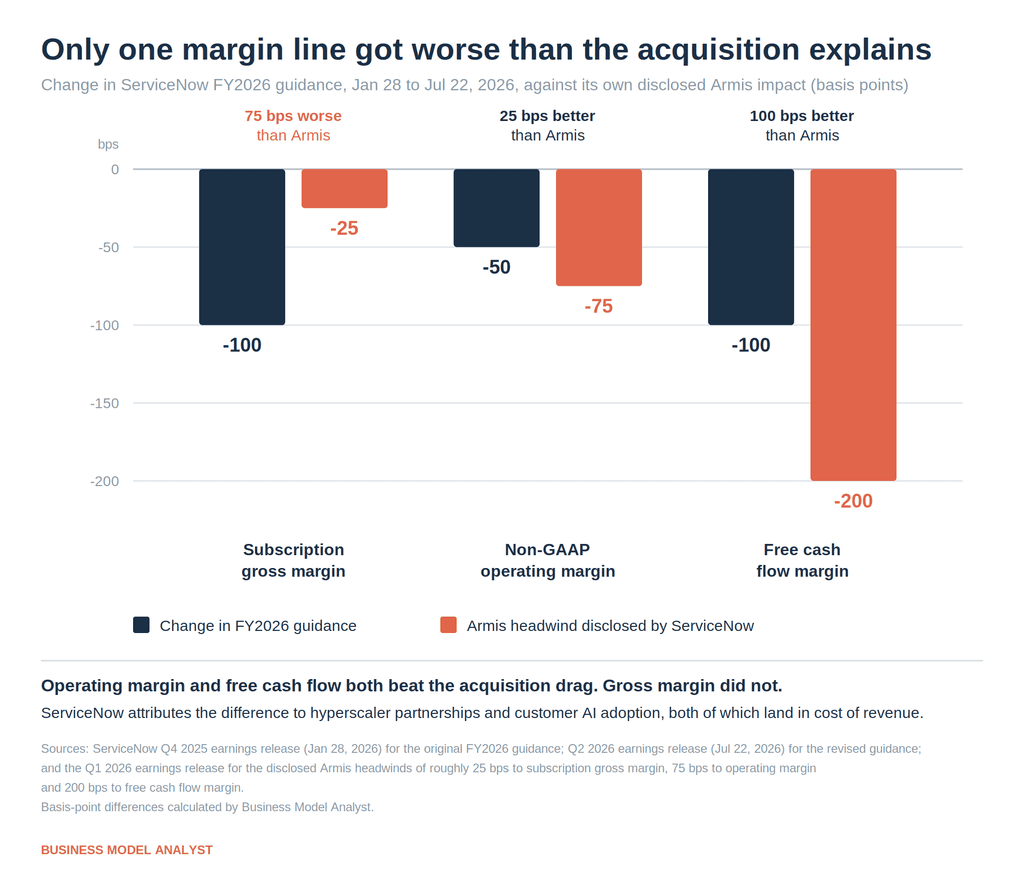
Two of the three lines actually came in ahead of the acquisition drag the company had told investors to expect. Operating margin absorbed a disclosed 75 basis point Armis headwind and only fell 50. Free cash flow absorbed 200 and only fell 100.
Gross margin is the exception. It fell 100 basis points against a disclosed Armis impact of 25. ServiceNow names the cause itself in the release: more customers using its hyperscaler partnerships, and an acceleration of customer AI adoption. Both land in cost of revenue. The CFO has argued that AI reasoning is under 10% of ServiceNow’s cost to serve and that Now Assist gross margins stay above 80%. The guidance walk is the first place that claim meets a number moving the other way, and it is worth watching each quarter rather than resolving now.
One further cost line rarely gets mentioned. ServiceNow’s professional services business loses money on purpose. It brought in $110 million of revenue in the second quarter of 2026, 2.8% of the total, at a gross loss of $29 million. Implementation is done by Accenture, Deloitte, NTT DATA and the rest of the partner channel; ServiceNow keeps the subscription and lets the integrators keep the labor. That is the opposite of the legacy enterprise software model, where services were a profit center.
Where the profits actually come from
Strip the second quarter of 2026 down and something odd appears. Income from operations was $162 million, a 4% GAAP operating margin. Interest income added $70 million and other income added $206 million, largely a $273 million unrealized gain on strategic investments. Pre-tax income was $438 million.
That means 63% of ServiceNow’s pre-tax income for the quarter came from its investment portfolio rather than its software. A year earlier the split was 76% operations, 24% everything else.
The portfolio is not incidental. Strategic investments went from $472 million at the end of 2024 to $1,542 million a year later to $2,073 million at June 2026, built with $1,056 million of purchases in 2025 alone. ServiceNow has quietly assembled a $2 billion venture book, and in the most recent quarter it out-earned the operating business.
Non-GAAP net income for the quarter was $930 million against GAAP net income of $298 million. The largest single reconciling item is stock compensation, $655 million, or 16.4% of revenue.
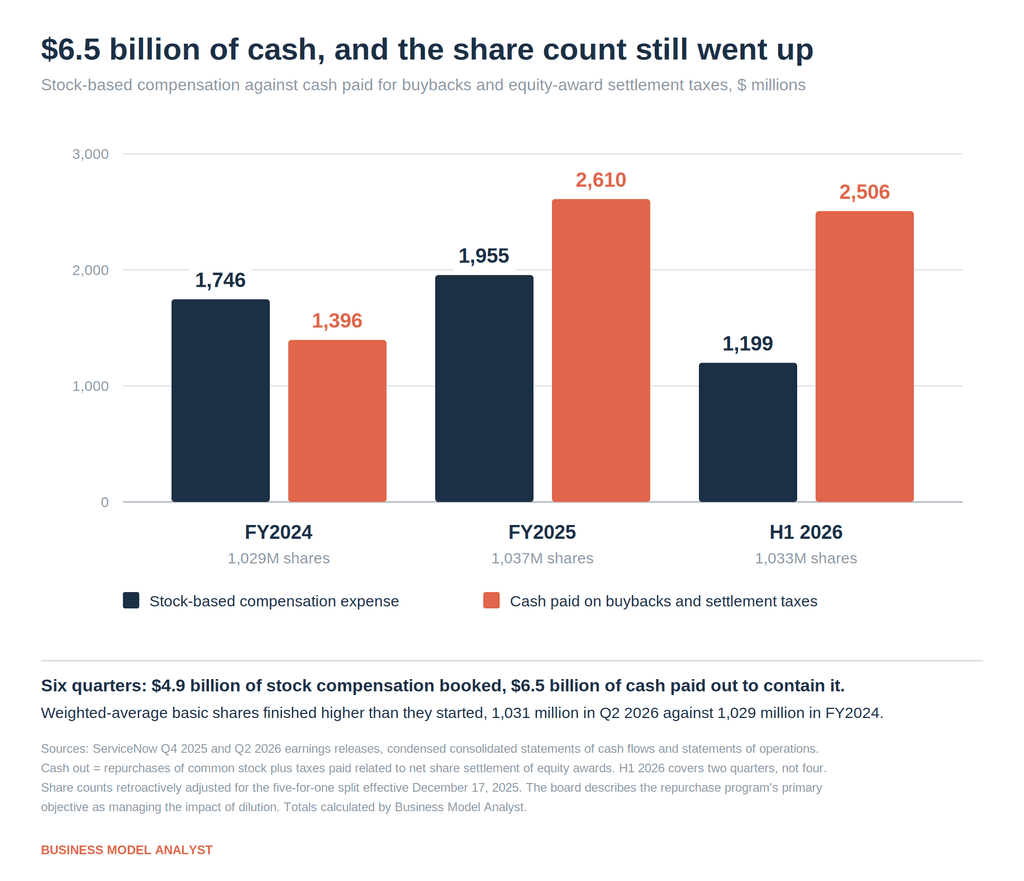
Across the six quarters from the start of 2024 to June 2026, ServiceNow booked $4.9 billion of stock compensation and paid out $6.5 billion of cash on buybacks and equity settlement taxes. Weighted-average basic shares went from 1,029 million in 2024 to 1,031 million in the second quarter of 2026. The board’s own language describes the repurchase program’s primary objective as managing the impact of dilution, which is an unusually honest way of saying the buyback is not a return of capital. It is a cost of employment paid twice, once in the expense line and again in cash.
To its credit, ServiceNow has committed publicly to getting stock compensation below 10% of revenue by 2029. From 14.7% in 2025, that is a real reduction and a rare thing to put in writing.
Information gain: what the filings show that the coverage does not
| Finding | Figure | Where it comes from |
|---|---|---|
| Balance sheet reversal | $8,564m net cash to $810m net debt in six months, a $9.37bn swing | Q4 2025 and Q2 2026 balance sheets |
| Acquisition step change | $113m of acquisition cash in FY2024, $8,776m in H1 2026 alone | Cash flow statements |
| Purchased assets exceed book value | Goodwill plus intangibles $13,618m against equity of $12,516m | June 30, 2026 balance sheet |
| Organic growth is decelerating | Q3 2026 guided at 20% constant currency including ~175 bps of Armis, so roughly 18.25% underlying | Q1 and Q2 2026 releases |
| Customer concentration | 25% of customers, 87% to 94% of contract value | Q4 2024 release, Q3 2025 fact sheet |
| The disclosure ladder | $1m tier retired at +12% growth, replaced by $5m, then $20m, then $50m tiers growing 20% to 30% | Quarterly releases, 2020 to 2026 |
| Only gross margin missed | -100 bps against a disclosed -25 bps Armis headwind | Guidance comparison, Jan vs Jul 2026 |
| Profit source inversion | 63% of Q2 2026 pre-tax income was non-operating, against 24% a year earlier | Q2 2026 statement of operations |
| The dilution treadmill | $6.5bn of cash over six quarters, share count up 0.2% | Cash flow statements |
| Backlog duration is flat | cRPO as a share of total RPO held at 45.5% to 46.1% across eight quarters | Quarterly releases |
That last one deserves a note. Bill McDermott attributed the second quarter’s $29 billion RPO to “longer customer commitments.” Total RPO and current RPO both grew 21% in that quarter, and the ratio between them has not moved in two years. Duration did extend during 2025, when RPO grew 29% against cRPO at 24.5%. It stopped in 2026. The book got bigger, not longer.
The risk
The bear case is not that ServiceNow is a bad business. It clears the Rule of 56, converts a third of revenue to free cash flow, and holds a customer list most software companies would trade their roadmap for.
The risk is that the two changes of 2026 are the same admission. A company whose organic growth rate is easing, whose billing unit is tied to headcount its customers are trying to reduce, and whose product roadmap could not fill the gap fast enough, spent $11.8 billion and its entire net cash position buying market adjacency in cybersecurity, a category where it has no history and where Palo Alto Networks, CrowdStrike and Microsoft all got there first. The market has been pricing that risk loudly. The shares traded at $194.73 last September and $81.24 in April, and sat near $137 in late August 2026.
The counterargument is straightforward and worth taking seriously. Security is the one category where ServiceNow’s configuration management database is a genuine advantage rather than a talking point, because knowing what every asset is and who can reach it is exactly the problem Armis and Veza solve. Buying a $1 billion-scale security business at eight times revenue while the whole cohort trades higher is not obviously bad capital allocation for a company that renews 98% of its customers and can put those products in front of 8,400 existing accounts without hiring a single new salesperson. Distribution is the scarce asset, and ServiceNow already owns it.
Both readings fit the same facts. The number to watch is the underlying growth rate once Armis laps into the base in 2027, because that is when the acquisitions stop flattering the headline and the organic engine has to answer for itself.
Frequently asked questions
How does ServiceNow make money? Almost entirely from subscriptions, $12,883 million of the $13,278 million it earned in 2025. It licenses seats to the employees who do work inside the platform, multiplies that by a platform edition and by each product line the customer subscribes to, and since 2025 also charges for AI usage on a consumption basis.
Is ServiceNow profitable? Yes, though the two profit measures diverge sharply. In 2025 GAAP net income was $1,748 million and non-GAAP net income was $3,669 million, a gap driven mostly by $1,955 million of stock compensation. Free cash flow was $4,636 million on a 35% margin.
Who are ServiceNow’s customers? About 8,400 organizations, including more than 85% of the Fortune 500, plus heavy public sector exposure. Nearly all 50 US states use the platform. The revenue is highly concentrated: 658 customers carried more than $5 million in contract value as of June 2026.
What is ServiceNow’s renewal rate? 98% in each of 2023, 2024 and 2025, on contracts that typically run three years.
Why did ServiceNow start acquiring companies? Publicly, to build a security and AI governance stack. Structurally, because its organic growth rate is easing and its model depends on having new products to sell into an installed base it already owns. Buying is faster than building.
What is ServiceNow’s revenue target? More than $30 billion in subscription revenue by 2030, with upside to $32 billion, and roughly 30% of contract value coming from AI products.
The Business Model Analyst Take
ServiceNow built one of the best businesses in enterprise software on a simple rule: own the customer relationship, then keep finding things to sell into it. The 98% renewal rate is not the moat. The moat is that ServiceNow gets to try again, at every renewal, against a buyer who has already standardized on its data model, with 91% of new dollars arriving in deals that bundle five or more products.
What 2026 shows is that the rule outlived the method. For two decades ServiceNow filled its own shelf. Now it borrows to buy the inventory, and the balance sheet went from $8.6 billion of net cash to net debt in the time it takes to close two deals. That is not a company in trouble. It is a company that has decided its roadmap is slower than its ambition and has chosen the faster option, with the honest cost showing up in goodwill, gross margin and interest expense rather than in the headline growth rate.
The interesting question is not whether ServiceNow can hit $30 billion. It is whether the answer to a slowing organic engine is more products or a different meter. The company is betting on both at once, and only one of them is cheap.
For the wider category mechanics, see the SaaS business model explainer. For a direct competitor running the same land-and-expand playbook on a different data model, see the Salesforce business model. For another software franchise repricing an installed base rather than growing one, see the Intuit business model.