
The proposed rule raises size thresholds by a median of roughly 10x across the industries that actually sell to the federal government. The pot of money those firms compete for is fixed by statute.
The Small Business Administration published a proposed rule on August 20 that would rewrite the definition of “small business” for the entire US economy. It collapses 978 size standards into 338, removes the ceiling that capped revenue-based thresholds at $47 million, and adds a productivity escalator on top of inflation for the first time in the agency’s history. By SBA’s own count, 114,541 firms become small and fewer than 200 stop being small. The headline number the agency leads with is a 1.8% increase in the small business population. Measured in federal contract dollars, the change is about 22 times larger than that.
Adam Hay runs a freight brokerage in Fort Thomas, Kentucky, doing roughly $3 million a year. He has never won a federal contract. Under the proposal, his industry’s threshold goes from $20 million to $259 million, and the Times reports SBA expects 835 more companies to join his pool. Hay’s read, quoted in that story, is that raising the ceiling makes his problem worse. He is right about the direction and probably understating the magnitude, because the firms joining his pool are not startups. They are seasoned contractors who already win federal work at scale, and they are bringing about $71 billion of it with them.
What Happened
SBA published RIN 3245-AI67 at 91 FR 53741 on August 20, 2026, alongside a companion white paper laying out a revised size standards methodology. Administrator Kelly Loeffler signed it. Comments close September 21, a 30-day window for a 44-page rule that touches every industry code in the country. As of August 27, the docket had 323 comments.
The mechanics of the change matter more than the headline thresholds:
- Consolidation. The current 978 six-digit NAICS standards plus 18 subindustry exceptions collapse into 338 standards set at the 4- and 5-digit level. Every exception disappears, including the Information Technology Value Added Reseller carve-out.
- Measure switch. Receipts-based standards drop from 496 to 129. Employee-based standards rise from 478 to 208. The entire construction sector converts from dollars to headcount.
- New analytical frame. SBA retires its seven-factor model and replaces it with a single “average market size” measure built from three inputs: national industry size, the number of distinct geographic markets, and an adjustment for net imports. The agency says this tracks the statute’s requirement that a small business be one “not dominant in its field of operations,” and it borrows the market-definition logic from the DOJ and FTC merger guidelines.
- No ceiling. The old methodology capped revenue standards at $47 million and headcount standards at 1,500 employees. The new formula has a floor and no roof. That is how Direct Property and Casualty Insurance Carriers arrive at $842 million in receipts, an 18x jump from the old cap.
- A one-way ratchet. SBA declines to lower any standard, including in the 45 industries where its own analysis said a reduction was warranted.
Here is what that produces in the industries with real federal contracting volume:
| NAICS | Industry | Current | Proposed | Multiple |
|---|---|---|---|---|
| 811310 | Machinery and equipment repair | $12.5M | $393M | 31.4x |
| 5415 | IT and computer services | $34M | $531M | 15.6x |
| 4885 | Freight transportation arrangement | $20M | $259M | 12.9x |
| 721110 | Hotels and motels | $40M | $503M | 12.6x |
| 518210 | Computing infrastructure and hosting | $40M | $402M | 10.1x |
| 541330 | Engineering services | $25.5M | $252M | 9.9x |
| 4881 | Support activities for air transportation | $40M | $285M | 7.1x |
| 561612 | Security guards and patrol | $29M | $186M | 6.4x |
| 562910 | Remediation services | $25M | $113M | 4.5x |
| 5622 | Waste treatment and disposal | $47M | $178M | 3.8x |
| 561210 | Facilities support services | $47M | $156M | 3.3x |
Median multiple across those eleven: 9.9x. Mean: 10.7x.
The Backstory
Congress told SBA in the Small Business Jobs Act of 2010 to review every size standard on a five-year cycle. The first review finished in 2016, the second in 2023. Both were housekeeping. In the second review SBA looked at 1,037 standards, raised 436, and found that 492 arguably deserved a cut. It cut none of them, citing the pandemic.
That precedent is the load-bearing part of the current proposal. SBA has now declined to reduce a size standard twice, and this rule makes the refusal explicit policy rather than a one-off accommodation. Add the new productivity adjustment and the arithmetic becomes a treadmill. Take BLS nonfarm business labor productivity at its long-run rate of 2.1% a year and pair it with inflation somewhere between the Fed’s 2% target and the 3.4% CPI-U print from July. The escalator runs 4.1% to 5.5% annually, which compounds to a 22% to 31% increase in every dollar-denominated threshold over one five-year review, with zero change in any industry’s structure. At the midpoint, the definition of small doubles about every 15 years on autopilot and can never move the other way.
The lending side moved first. SBA doubled the cumulative 7(a) plus 504 borrowing limit from $5 million to $10 million effective July 4, decoupling the two programs so a borrower can carry $5 million of each. The individual 7(a) cap did not change and remains $5 million, a detail some coverage has blurred. Anyone modeling an acquisition against the SBA 7(a) program should treat the $10 million figure as a combined-balance ceiling, not a bigger single loan.
The Plan
SBA frames the rule around a “benefit cliff,” a term it borrows from a Naval Postgraduate School study. The argument is that firms approaching a size standard turn down work, split entities, or sell rather than lose eligibility. Push the cliff out and those firms keep growing. The agency backs this with Girth and Brown’s 2018 tracking of 977 federal suppliers from 2005 to 2014, which found that surviving contractors roughly doubled their contract activity while relying less on set-asides over time.
The cliff is real. Contractors have been complaining about it in House Small Business Committee hearings for years, and both the Republican chair and the Democratic ranking member have said the standards need fixing.
The problem is what SBA left out of the cost-benefit analysis. OMB determined the rule is not a significant regulatory action. The only benefit SBA put an actual dollar figure on is the time contracting officers save reading a shorter rulebook: 5 hours and 50 minutes at $37.64 an hour, or $219.57 per reader, across roughly 37,600 contracting officers. That totals about $8.3 million. Meanwhile the rule reclassifies $71 billion of existing federal contracts. The monetized benefit is about one eight-thousandth of one percent of the transfer it sits on top of.
The Business Model Angle
Two things happen at once here, and only one of them is expansion.
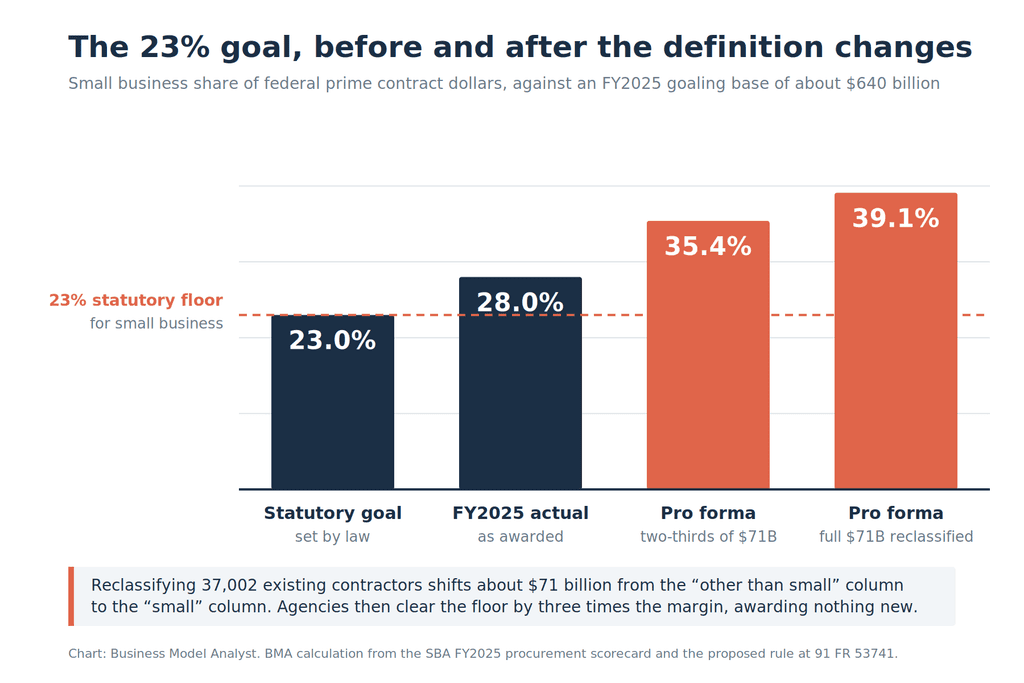
The pot does not grow. The statute sets a floor of 23% of federal prime contract dollars for small business. In FY2025 the government cleared it, awarding $179 billion in prime contracts, which SBA reported as nearly 28% of the goaling base. That implies a base of roughly $640 billion. The 23% floor on that base is $147 billion, so agencies finished the year with about $32 billion of cushion above the legal minimum.
Now reclassify the 37,002 firms that already hold $71 billion of FY2025 contracts. Those contracts sit in the base already. Moving them from the “other than small” column to the “small” column takes achievement from 28.0% to 39.1%, and the cushion above the floor from $32 billion to $103 billion. Haircut the $71 billion by a third to account for dollars outside the goaling base and it still lands at 35.4%.
Nobody awards a single new contract. Agencies wake up three times further above the floor than they went to sleep. Every contracting officer who was creating set-asides at the margin to stay on the right side of the scorecard now has room not to.
That is the dilution, and it explains why the two framings of this rule differ by so much. Counted in firms, the change is 1.8%. Counted in the contract dollars those firms already command, it is 39.7%. Ratio: 22 to 1. SBA chose the first number for its press release.
The measure switch reprices vertical integration. Commercial and institutional building construction goes from a $45 million receipts test to a 600-employee test. Run the math yourself. At 600 employees, a construction manager who subcontracts nearly everything and books $1 million of revenue per head is a $600 million business and still small. A contractor who employs his own trades at $150,000 per head hits the same 600 employees at $90 million and stops being small at a sixth the revenue. Under the old receipts test, both hit the wall at $45 million.
The rule quietly rewards the asset-light, pass-through, labor-outsourcing model over the vertically integrated one. It also cuts the other way at the top end. Removing the ITVAR exception moves value-added resellers from a 150-employee test to a $531 million receipts test. A reseller with 400 employees and $200 million of mostly hardware pass-through becomes small. A lean reseller with 80 employees and $600 million of pass-through stops being small. Same rule, opposite outcomes, decided by how you buy your labor.
For anyone underwriting an acquisition, this is the sleeper. Size status now travels with headcount in whole sectors, which means a bolt-on that adds crews can cost the platform its eligibility while a bolt-on that adds revenue does not. Buyers running search fund and ETA playbooks in government-adjacent services need to model average headcount over the trailing 24 months before signing anything, and multi-unit operators should remember that affiliation rules pull related entities into the count, the same way they do in the franchise model.
The Risk
The strongest case against this reading is that set-aside dependence is a bad business model and the rule is right to punish it. Girth and Brown’s data supports that: contractors who survive a decade in the federal market lean on set-asides less each year. A firm whose entire margin depends on a legal category rather than on price or capability has a fragile business, and the category was always the government’s to redefine.
There is also a real efficiency argument. GAO has found that more competition delivers better price and performance. If a $30 million engineering firm loses a recompete to a $200 million one that does the work cheaper, the taxpayer wins and the losing firm was collecting a subsidy.
Two things weaken that defense. First, SBA never modeled the transfer. It acknowledged that firms nearest the current thresholds face the most new competition and that margins may compress, then declined to quantify either. Second, the smallest firms are not the ones who benefit. The rule does nothing for a company entering federal contracting for the first time, which is the population the 23% goal was written to build. Bipartisan Policy Center analysts have made this point and SBA has not answered it.
The 8(a) interaction deserves watching too. SBA’s new social disadvantage test takes effect September 10, which makes economic disadvantage the operative gate. Those caps sit at $850,000 adjusted net worth and $400,000 average AGI. Owners of newly small firms with $200 million of revenue will not clear them, so the certification programs stay narrower than the base size standards. That gap is where the next round of lobbying goes.
Quick Questions
Is the rule in effect? No. It is a proposal. Current standards govern until a final rule takes effect, and firms should not change SAM representations yet. Size is determined at self-certification on each offer.
When does it become final? Unknown. Comments close September 21, 2026, and SBA said it will review them before issuing a final rule. There is no statutory deadline for the final action.
Who wins the most? Firms in professional services, IT, engineering, and consulting that outgrew their standard. SBA identified 5,314 engineering services contractors alone that would regain small status, plus 2,247 in other computer related services and 2,171 in custom computer programming.
Who loses? Growing small businesses sitting just under today’s thresholds. SBA says so in the rule. Those firms compete for the same contracts as the newcomers and have thinner past performance records.
Does this change SBA lending? At the margin. Most 7(a) and 504 borrowers sit far below the size standard already, and both programs carry statutory caps, which is part of why OMB called the rule insignificant. The bigger lending change this year was the July 4 decoupling that took combined 7(a) plus 504 capacity to $10 million.
How does the 23% goal actually work? It applies to a goaling base, not to total federal contract spending. Federal contract obligations ran over $883 billion in FY2025 while the base against which the goal is measured was roughly $640 billion. About 28 cents of every federal contract dollar sits outside the goal entirely.
The Business Model Analyst Take
Small business status was never a description. It was a rented moat, and the landlord just doubled occupancy.
SBA is solving a real problem with a tool that has no reverse gear. The benefit cliff punishes growth, that is worth fixing, and the firms stuck above the old thresholds have a legitimate complaint. But the fix removes the ceiling, refuses to ever lower a standard, and adds an escalator that compounds faster than inflation. Combine those three and the category stops sorting anything. A definition that can only expand converges on including everyone, at which point the 23% set-aside becomes a rounding convention rather than a policy.
The practical read for operators: if your business plan has a line in it that depends on a government-assigned category, discount that line. Not to zero, but treat it as a contract with a counterparty who can rewrite the terms on 30 days’ notice, because that is what happened on August 20. The firms that survive the next decade in federal contracting will be the ones who can win a full and open competition and treat the set-aside as upside rather than as the plan.
For the newly small, the window is narrow in a different way. You get up to nine years of runway in 8(a) if you qualify, and you get set-aside eligibility at sizes nobody has ever had it at. Use it to build past performance you can carry into open competition, because the standard that just made you small will keep rising, and eventually it will stop being the thing that distinguishes you from anyone.
Comments close September 21. The transition rules, which standard applies to a pending offer, are the part nobody has written yet, and they are where a well-argued comment can still move something.