
Most explainers about the SBA 7(a) loan read like a brochure a bank left on a table. Maximum loan amount, friendly rates, government backing, call us today. That framing is useless if you are actually trying to buy a business, because it treats the 7(a) as a product you apply for rather than what it really is: a set of hard constraints on your capital structure.
The 7(a) does not just tell you how much you can borrow. It tells you how much of your own cash has to be in the deal, how long you get to pay the money back, who has to sign personally, what the seller is allowed to do after closing, and how much of the purchase price can be deferred. Change any one of those and the deal either works or it does not. Buyers who lose deals almost never lose them on the interest rate. They lose them on structure.
This is a mechanics guide. If you want the strategic case for buying a small business instead of starting one, we covered that separately in the ETA arbitrage piece. If you plan to raise outside capital to fund the search itself rather than writing the checks yourself, how search funds work covers that structure. This one is about what happens after you have decided to buy and now need the capital stack to close.
SBA 7(a) loan (business acquisition use): A term loan made by a private lender and partially guaranteed by the U.S. Small Business Administration, used to finance a complete or partial change of ownership of an operating small business. The SBA does not lend the money. It insures a portion of the lender’s loss, which is why a bank will write a ten-year loan against goodwill it could never collateralize.
Maximum loan: $5 million per 7(a) loan. SBA’s maximum guaranteed exposure is $3.75 million.
Guaranty: 85% of loans up to $150,000; 75% above that.
Minimum equity injection on a change of ownership: 10% of total project cost.
Governing rulebook: SOP 50 10 8, effective 1 June 2025, plus later procedural notices.
What the 7(a) actually finances in an acquisition
The important thing about the 7(a) in an acquisition context is that it will fund intangibles. That is the whole trick.
A conventional commercial lender underwrites against collateral. In a typical small business purchase, the collateral is close to worthless: a used van, some shelving, a leasehold you cannot foreclose on. The value you are buying is the customer list, the reputation, the trained staff, the recurring contracts. On the balance sheet that becomes goodwill, and goodwill has a liquidation value of roughly zero.
The 7(a) guaranty is what makes a lender willing to write against that zero. In an acquisition, 7(a) proceeds can cover the purchase price of the business including goodwill, the associated real estate if the deal includes it, equipment, working capital to run the business after closing, and the closing costs and fees themselves. That last one matters more than buyers expect: guaranty fees, closing costs and a working capital cushion can all be rolled into the loan, which is why the loan amount and the purchase price are rarely the same number.
The constraint runs the other direction. Because SBA is insuring against a collateral shortfall, it prices and structures the loan as though the shortfall exists. That produces the three features buyers find most annoying: the equity injection, the ten-year maturity, and the personal guarantee. None of them are bureaucratic clutter. They are the three places where SBA transfers risk back to you.
The $5 million ceiling, and the thing that changed in July 2026
A single 7(a) loan tops out at $5 million. That number has not moved.
What did move is the cumulative limit. On 4 July 2026 the SBA doubled the combined 7(a) and 504 exposure a borrower can carry, from $5 million to $10 million, by decoupling the two programs. Administrator Kelly Loeffler described it as “unlocking the largest financing opportunity in agency history.” Most acquisition-finance pages on the internet have not caught up to this yet, and the ones that have tend to describe it wrongly.
Here is the part that matters for a buyer, and the part almost nobody states plainly: the 504 side of that $10 million cannot buy goodwill. SBA 504 proceeds are restricted to fixed assets, principally owner-occupied real estate and machinery with at least ten years of useful life. Working capital, inventory and business acquisition intangibles are excluded.
So the new $10 million ceiling is not a $10 million acquisition budget. It is useful in exactly one situation: your target owns real estate or heavy equipment, and you split the deal. The 7(a) takes the operating business up to $5 million, and a 504 takes the building. If you are buying a services business with a leased office and no hard assets, your ceiling is still $5 million, exactly as it was.
Loeffler herself said on 27 July 2026 that she “absolutely would” support doubling the per-loan cap as well, pointing to manufacturers repeatedly hitting the $5 million wall. That change would require legislation, not a rule, so treat it as a possibility rather than a plan.
The ceiling is also what separates a 7(a) buyer from an institutionally funded one. Search funds in the 2024 to 2025 cohort paid a median of $16.0 million in enterprise value at 6.2x EBITDA, according to the Stanford Graduate School of Business 2026 Search Fund Study. That is three times what a single 7(a) can carry, which is precisely why search funds raise equity from investors instead and why the two paths converge on very different target sizes. The 7(a) is the instrument for the deal you can hold alone.
The 10% down payment, and the seller note that covers half of it
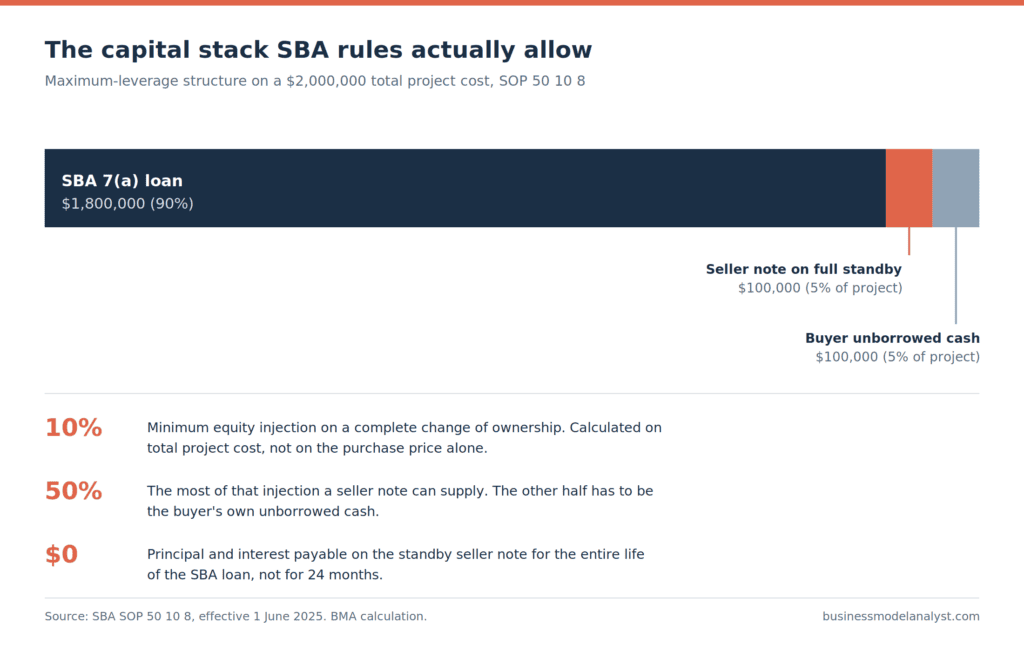
Under SOP 50 10 8, a complete change of ownership requires a minimum equity injection of 10% of total project cost. Note the base: total project cost, not purchase price. If you are financing $2 million of purchase price plus $150,000 of working capital and fees, the injection is calculated on $2.15 million.
This is a real tightening, not a restatement. The previous rulebook, SOP 50 10 7.1, carried no mandatory minimum equity injection at all and let lenders apply their own judgment. That flexibility is gone.
The half of this rule that buyers care about is what counts as equity. A seller note can count, subject to two conditions:
- It must be on full standby for the entire life of the SBA loan. No principal. No interest. Not for 24 months, which was the old convention that survives in a lot of stale online advice. For the whole term.
- It can supply no more than 50% of the required injection.
Put those together and the maximum-leverage structure on a $2 million project is a $1.8 million 7(a) loan, a $100,000 seller note frozen for a decade, and $100,000 of your own unborrowed cash. That is 5% of the project from your pocket, which is the number to hold onto. The “10% down” headline is real, but half of it is negotiable with the seller and half of it is not negotiable with anyone.
The standby condition is where deals quietly die. A seller who is happy to carry 5% at 8% interest is often unwilling to carry 5% at zero interest for ten years with a balloon at the end. That is not a financing detail. It is a valuation conversation, and the sooner you have it, the fewer LOIs you waste.
Two structures that experienced buyers use in response. First, the two-note stack: one note on full standby that counts as equity, and a second subordinated note on limited standby that does not count as equity but can often be excluded from the debt service coverage calculation. Second, keeping the seller note conversation on the table during price negotiation rather than after, since a seller who understands the standby terms will price them into the headline number one way or another.
Who signs, and for how long
The personal guarantee is the least discussed and most consequential part of the structure.
On a complete change of ownership, every owner of 20% or more personally guarantees the loan. Owners below 20% generally do not. That is the familiar rule and it survived the rewrite.
On a partial change of ownership, where the seller keeps a stake, SOP 50 10 8 rewrote the arithmetic. Any seller retaining equity, even 1%, must personally guarantee the full loan amount, for at least two years after final disbursement or until the loan has been current for twelve consecutive months. All new owners acquiring any interest must be co-borrowers regardless of size. Partial changes must be structured as stock or membership unit purchases, not asset purchases. Phased or multi-step buyouts are out; ownership transfers in a single closing.
The practical effect is that seller rollover equity, once a common way to bridge a valuation gap and keep the seller motivated, has been made expensive enough that most sellers refuse it. A seller who was going to keep 15% and stay involved is now being asked to personally guarantee 100% of a loan they do not control. Most will not.
There is a related restriction buyers routinely trip over. After a complete change of ownership, the seller cannot remain an officer, director, stockholder or employee of the business beyond twelve months from closing. Transitional help is permitted, but as a 1099 consultant, not as an employee. If your deal thesis depends on the founder staying three years to hold the key accounts together, the 7(a) is the wrong instrument, or the thesis needs rebuilding.
Insurance obligations tightened alongside. Life insurance on key personnel is now required in defined cases, and hazard insurance is mandatory on all collateralized assets. Small line items, but they are closing conditions, and closing conditions have a way of appearing at week seven.
Ten years for goodwill, and what that costs
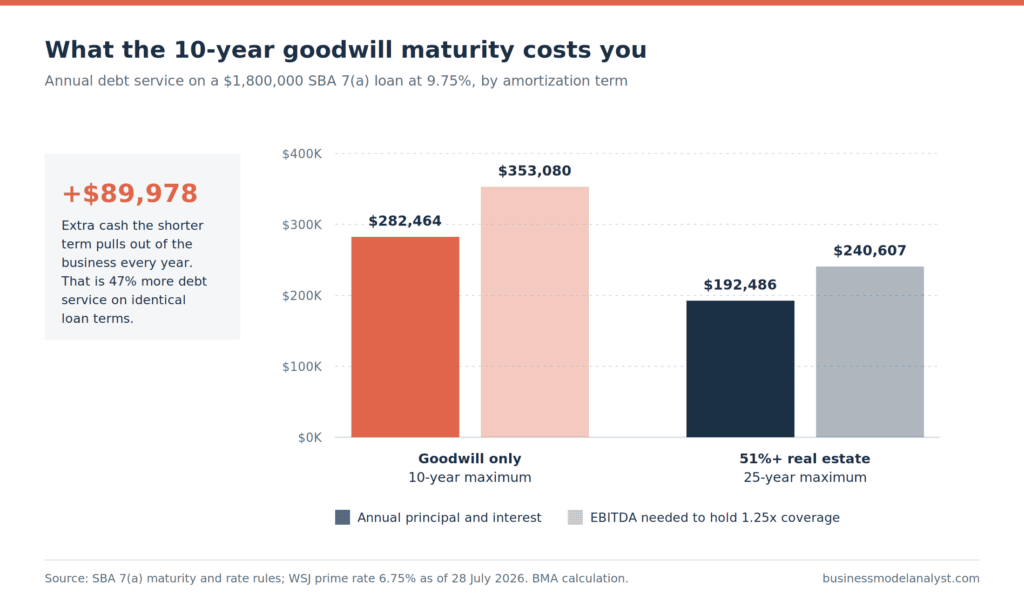
SBA maturities are set by use of proceeds, not by borrower preference. Working capital and general business purposes, which is where goodwill lands, cap out at ten years. Real estate and equipment can run to 25 years.
This single line does more damage to acquisition math than the interest rate ever will.
Take a $1.8 million loan at 9.75%. Amortized over ten years, annual debt service is roughly $282,500. Amortized over 25 years, the same loan at the same rate costs roughly $192,500. The ten-year cap pulls an extra $90,000 out of the business every year, a 47% increase in debt service on identical loan terms.
Run that through a coverage test and the consequence becomes concrete. To hold 1.25x coverage against ten-year amortization you need roughly $353,000 of EBITDA. Against 25-year amortization you need about $241,000. The same business, at the same price, at the same rate, either clears or fails depending entirely on whether the deal includes real property.
Which is why the maturity rule quietly drives deal selection. When real estate makes up at least 51% of the project, the whole loan can be written on the longer term, and the debt service math changes completely. Buyers who understand this stop treating an owned building as a nuisance to be excluded from the deal and start treating it as the cheapest coverage ratio available. Meanwhile a pure goodwill purchase, the classic services roll-up target, gets the harshest amortization the program offers.
Rates: prime plus a capped spread
The 7(a) is not a fixed-rate government loan. The overwhelming majority of acquisition loans are variable, priced off the WSJ prime rate, which stood at 6.75% as of 28 July 2026.
SBA caps the spread by loan size. The caps are ceilings, not quotes, and competitive lenders often price inside them on larger, cleaner deals.
| Loan size | Maximum spread over base rate | All-in ceiling at prime 6.75% |
|---|---|---|
| $50,000 or less | +6.50% | 13.25% |
| $50,001 to $250,000 | +6.00% | 12.75% |
| $250,001 to $350,000 | +4.50% | 11.25% |
| Above $350,000 | +3.00% | 9.75% |
Two things follow. First, larger loans are structurally cheaper, and the drop from +4.5% to +3.0% at the $350,000 line is steep. Second, because the rate floats with prime and the term runs a decade, your debt service is exposed to rate policy for the entire holding period. A 100 basis point move in prime on a $1.8 million ten-year loan changes annual debt service by roughly $10,000. Model the deal at a rate above today’s, not at today’s.
The guaranty fee, and why the headline number overstates it
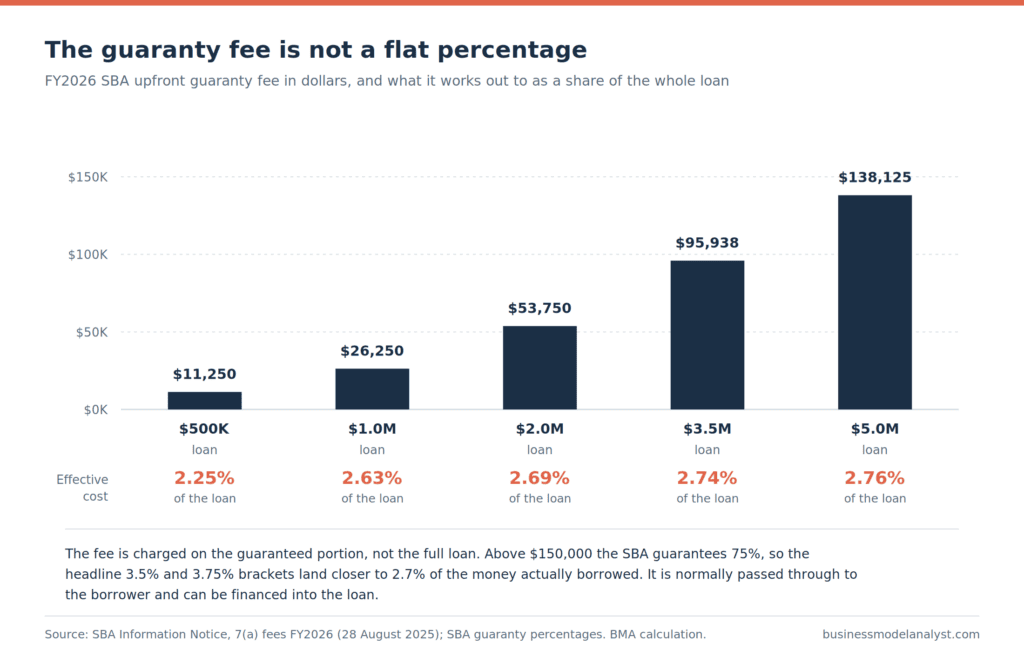
For fiscal 2026 the SBA upfront guaranty fee on loans with maturities over twelve months runs 2% of the guaranteed portion for loans up to $150,000, 3% from $150,001 to $700,000, and for loans from $700,001 to $5 million, 3.5% of the guaranteed portion up to $1 million plus 3.75% on the guaranteed portion above that. Lenders also pay an annual service fee of 0.55% of the outstanding guaranteed balance, which they are not permitted to pass through.
The upfront fee they can pass through, and normally do. But the headline percentages are charged on the guaranteed portion, not the whole loan, and above $150,000 the guaranty is 75%. That gap is worth understanding because it is where most published cost estimates go wrong.
On a $2 million loan, the guaranteed portion is $1.5 million. The fee is 3.5% of the first $1 million plus 3.75% of the remaining $500,000, or $53,750. Against the full $2 million borrowed, that is 2.69%. At $5 million the fee reaches $138,125, still only 2.76% of the loan. The effective cost is remarkably flat across the range, roughly 2.25% to 2.76%, and it can be financed into the loan rather than paid at close.
For a capital structure exercise, that means the guaranty fee is real but rarely decisive. It is a one-time cost of about 2.7 points on the borrowed amount. The ten-year amortization, by contrast, costs you 47% more debt service every single year. Buyers spend far more energy negotiating the fee than the term, and they have it exactly backwards.
The process, and how long it really takes
The advertised timeline and the observed timeline are different numbers. Here is the honest sequence for an acquisition.
| Stage | Realistic duration | What determines it |
|---|---|---|
| Pre-screen and deal fit | 3 to 7 days | Whether the target’s cash flow covers new debt, and whether the financials are clean enough to underwrite |
| Underwriting | 10 to 20 days | The lender rebuilds post-acquisition cash flow and tests coverage. Add-backs get challenged here |
| SBA authorization | 5 to 10 days | Near zero if your lender has delegated Preferred Lender authority. Otherwise SBA reviews it |
| Closing preparation | 10 to 15 days | Business valuation, appraisals, insurance, entity formation, landlord waivers, third parties |
| Total | 35 to 45 days prepared, 70+ days unprepared |
Two structural points buyers should act on.
Use a Preferred Lender. PLP lenders approve under delegated authority and skip an entire review cycle. On a competitive deal where the seller has other offers, that stage alone can be the difference.
Understand the valuation trigger. Under SOP 50 10 8, if the financed portion of the project minus the appraised value of real estate and equipment is $250,000 or less, the lender may value the business in-house. Above that threshold, an independent valuation is required, performed by someone holding a recognized credential such as CVA, ASA, ABV, CBA or BCA and independent of the loan decision. If buyer and seller have a close relationship, family members or existing co-owners, the independent valuation is required regardless of amount. Since most goodwill-heavy acquisitions clear $250,000 easily, assume you are getting a third-party valuation and budget the two to three weeks.
Underwriting standards shifted again in 2026. Procedural Notice 5000-875701, effective 1 March 2026, discontinued the SBSS credit score for federally regulated lenders, requiring them instead to apply the same commercial credit analysis they use on comparable non-guaranteed loans. For 7(a) Small Loans it set a minimum debt service coverage ratio of 1.1 to 1 on a historical or projected basis, alongside documented coverage analysis and two months of commercial bank statements. In practice most acquisition lenders underwrite to a coverage ratio comfortably above the floor, so do not build a model that clears 1.1x and call it financeable.
One more eligibility gate that catches people: the business must be 100% owned and controlled by U.S. citizens, lawful permanent residents or qualified U.S. Nationals. SBA revised its guidance on businesses owned by non-U.S. citizens through Policy Notice 5000-876441, effective 1 March 2026. If your cap table has any non-citizen ownership, resolve that question before you sign an LOI, not during underwriting.
Why deals get declined
Declines cluster into a small number of patterns, and almost all of them are structural rather than personal.
Coverage does not work post-close. The lender rebuilds the target’s cash flow with the new debt on top and the owner’s compensation normalized. Seller add-backs that were never really discretionary get stripped out. If coverage fails, no amount of buyer enthusiasm fixes it.
The equity injection is not documentable. Cash counts, but it has to be traced: statements going back 30 to 90 days, wire confirmations, gift letters. Money that appeared last week from an undocumented source is not equity. Personal loans can qualify only if repayment comes from a source outside the business.
The seller will not sign a full-standby note. Covered above. This is the single most common late-stage collapse under the current rules.
The structure is disqualified rather than the borrower. Rollover equity in a partial change, an asset purchase where a stock purchase is required, a phased buyout, a seller who wants to stay on as an employee past twelve months. These fail on form, not on credit, and they fail after you have spent money on diligence.
Concentration and transferability. A business where the departing owner is the relationship, or where one customer is 40% of revenue, will fail underwriting on transfer risk even if the historical numbers are excellent.
Financial records that cannot be reconciled. Tax returns that do not tie to the P&L, cash-heavy revenue that cannot be verified. SOP 50 10 8 does permit CPA-prepared or CPA-reviewed statements where returns are incomplete or unrepresentative, which helps, but it does not cure unreconcilable books.
The program is repricing risk, and that is the real story
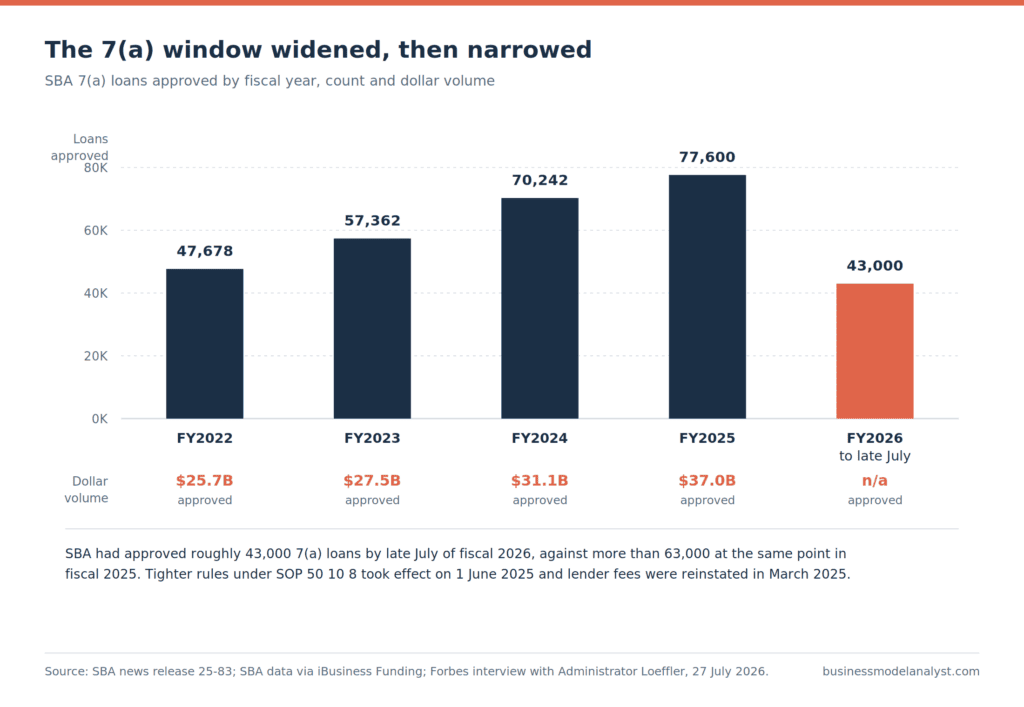
Every rule above exists for a reason, and the reason is visible in SBA’s own numbers.
The 7(a) program is statutorily required to operate at zero subsidy, meaning fees paid by lenders and borrowers are supposed to cover losses without appropriated funds. In March 2025 the SBA disclosed that the program had run negative cash flow of about $397 million in fiscal 2024, its first deficit in more than a decade, and that roughly $460 million in upfront lender fees had gone uncollected between 2022 and 2024 while underwriting standards were relaxed. At a February 2025 Senate Small Business Committee hearing, Chair Joni Ernst cited a twelve-month default rate that had more than doubled to roughly 3.2%, with defaults on loans under eighteen months old nearly tripling to almost 1.5%.
That is the context for everything SOP 50 10 8 did. Fees were reinstated in March 2025. The rulebook was rewritten effective 1 June 2025. The mandatory 10% injection came back, seller notes were pushed to full-life standby, rollover equity was made unattractive, and phased buyouts were banned. These are not arbitrary. They are a lender tightening covenants after a bad vintage.
The volume response has been immediate. Approvals climbed from 47,678 loans and $25.7 billion in fiscal 2022 to 77,600 loans and $37 billion in fiscal 2025. By late July of fiscal 2026, SBA had approved roughly 43,000 7(a) loans, against more than 63,000 at the same point a year earlier.
Read that as pricing, not as policy failure. The guaranty is insurance. Insurance that pays out more than it collects gets repriced, and repricing insurance means either charging more or covering less. SBA chose to cover less, by raising the amount of genuine buyer equity that has to sit beneath its guaranty. If you are buying a business in the current window, you are borrowing into a program that has just decided its previous risk settings were wrong.
Frequently asked questions
Can I buy a business with no money down using an SBA 7(a) loan?
No. A complete change of ownership requires a minimum 10% equity injection of total project cost, and a seller note can supply at most half of it. The floor on your own unborrowed cash is 5% of the project. Zero-down structures marketed online either predate SOP 50 10 8 or are not 7(a) deals.
Does the seller note have to be interest-free?
If it counts toward your equity injection, yes. It must be on full standby with no principal and no interest payments for the entire life of the SBA loan. A second, non-qualifying seller note can carry payments, but it does not count as equity.
How much can I borrow in total?
$5 million per 7(a) loan. Since 4 July 2026 you can hold up to $10 million of combined 7(a) and 504 exposure, but 504 proceeds cannot fund goodwill or working capital, so the higher ceiling only helps when the deal includes real estate or long-life equipment.
What interest rate will I actually pay?
Variable, tied to prime. For loans above $350,000 the spread is capped at prime plus 3.00%, which is 9.75% at the prime rate of 6.75% in late July 2026. Smaller loans carry higher caps. Lenders may price below the cap.
How long is the repayment term?
Ten years for goodwill and general business purposes. Up to 25 years where real estate or equipment is involved, which is why deals including real property carry materially lower annual debt service.
Do I have to sign a personal guarantee?
On a complete change of ownership, every owner of 20% or more does. On a partial change, all new owners are co-borrowers and any seller retaining even 1% must guarantee the full loan for at least two years.
Can the seller stay on after closing?
For up to twelve months, and only as a 1099 consultant rather than an officer, director, stockholder or employee. Longer transition arrangements need a different financing structure.
How long does approval take?
Roughly 35 to 45 days from application to funding for a well-prepared deal with a Preferred Lender, and 70 days or more when documentation, valuation or purchase agreement terms are still moving.
Is a business valuation required?
Yes, in most acquisition cases. If the financed portion minus appraised real estate and equipment exceeds $250,000, an independent credentialed valuation is required. It is required at any amount when buyer and seller are related.
The Business Model Analyst Take
The 7(a) is best understood not as a loan program but as a standing offer from the federal government to convert a specific kind of intangible asset into ten-year amortizing debt, at a price. The price is 10% equity, a personal guarantee, roughly 2.7 points of guaranty fee, and a maturity short enough to make coverage the binding constraint on every deal you look at.
That framing changes how you should shop. Buyers who treat the 7(a) as a product spend their energy on rate shopping and lender selection. Buyers who treat it as a capital structure spend their energy on the three variables that actually determine whether a deal closes: whether the seller will freeze a note for a decade, whether the target’s cash flow clears coverage against ten-year amortization rather than the 25-year amortization their mental model defaults to, and whether the deal contains enough real property to earn the longer term.
The 2025 and 2026 rule changes made this more true, not less. By eliminating the flexibility that let lenders paper over thin equity, SBA moved the decision point earlier in the process. You now find out whether the structure works during negotiation rather than during underwriting, which is worse for buyers who were relying on ambiguity and better for buyers who can do the arithmetic.
The uncomfortable implication is that the current rulebook systematically favors one kind of target over another. Asset-light service businesses, the category most people mean when they say they want to buy a small business, get the shortest maturity, the tightest coverage, and the highest sensitivity to a seller’s willingness to defer. Businesses with real estate get the long term, the lower debt service, and now access to a second $5 million through the 504 side. The program is not neutral between those two, and it just got less neutral. Price your search accordingly.