What is a Samsung SWOT analysis? A Samsung SWOT analysis is a structured assessment of Samsung Electronics’ internal strengths and weaknesses alongside the external opportunities and threats shaping its markets. In 2026 the exercise is unusually stark: Samsung is simultaneously the world’s largest memory chipmaker, the world’s largest smartphone vendor, and a company whose entire profit engine now rests on a single division riding a historic AI memory boom.
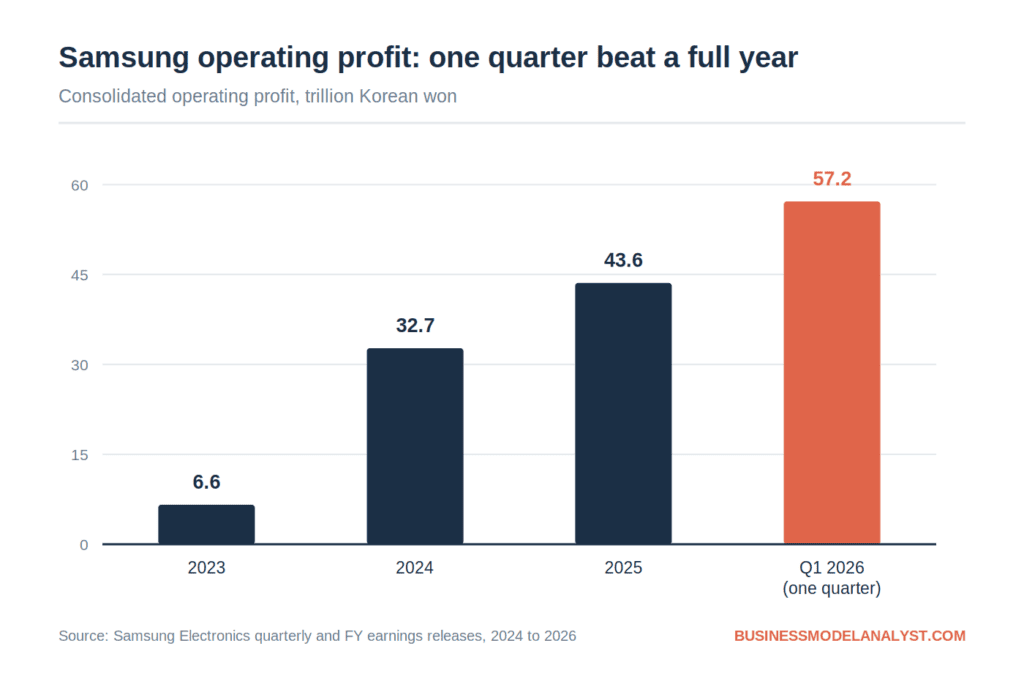
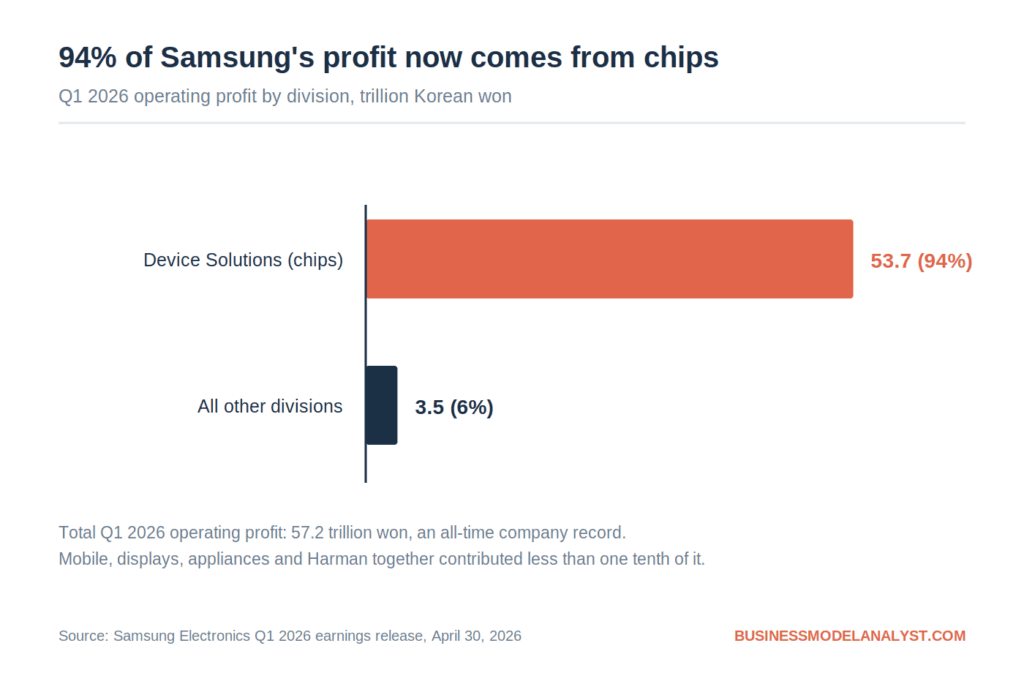
Samsung Electronics just posted the most extreme quarter in its 88 year history. In the first three months of 2026 it earned more operating profit than in the whole of 2025. Ninety four percent of that profit came from one division. The rest of the company, including the smartphone business that most people think of as “Samsung,” contributed less than one tenth.
That single fact reframes every part of this SWOT analysis. Samsung is no longer best understood as a diversified consumer electronics conglomerate that happens to make chips. It is a memory semiconductor company with a very large consumer hardware business attached, and the strategic question for the next 24 months is what happens to the second part when the first part stops printing money.
Samsung at a glance (2026)
Samsung Strengths
1. Number one position in DRAM at the exact moment DRAM became scarce
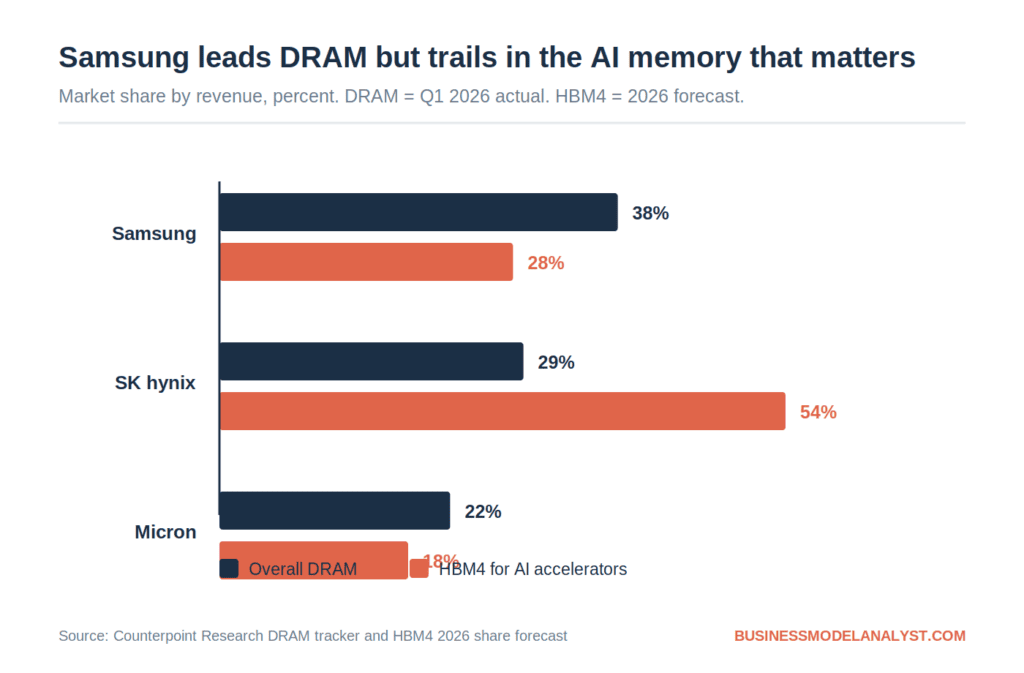
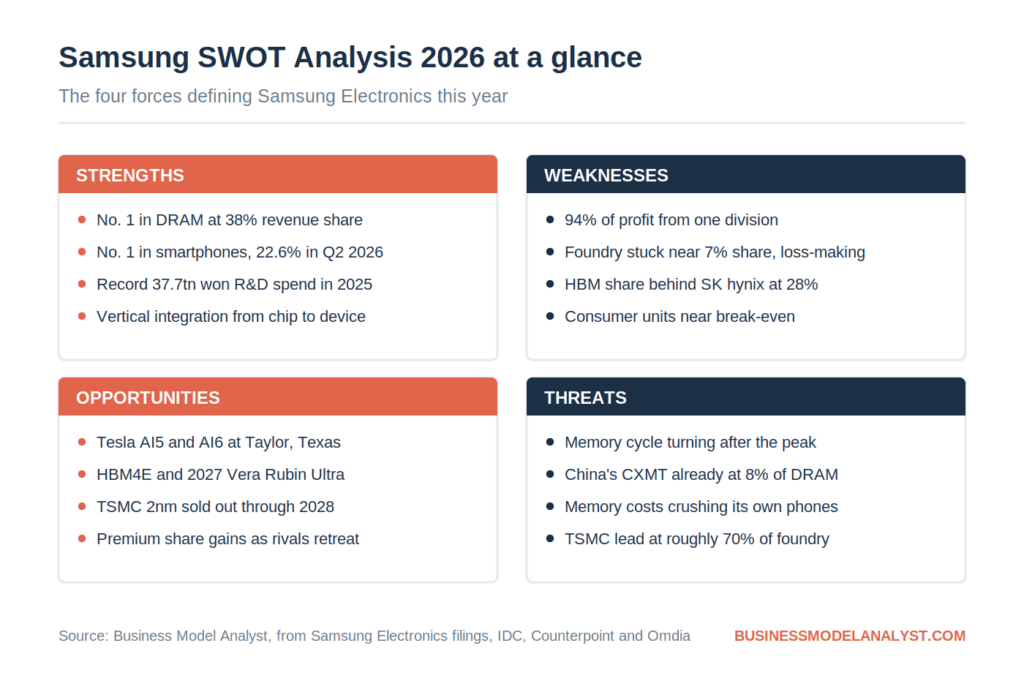
Samsung held 38% of global DRAM revenue in the first quarter of 2026, ahead of SK hynix at 29% and Micron at 22%. That leadership has always been valuable. What changed is the price environment. Server memory pricing roughly doubled between late 2025 and early 2026 as hyperscalers competed for supply, and because DRAM is a fixed-cost business, almost all of that price increase fell straight to operating profit. Samsung’s chip division ran a 66% operating margin in Q1 2026, a figure normally associated with software companies rather than factories.
The strength here is not simply that Samsung makes memory. It is that Samsung makes more of it than anyone else, so it captures more of the upside per won of price movement than any competitor.
2. Vertical integration that turned a supply crisis into a share gain
Global smartphone shipments fell 6.7% year over year in the second quarter of 2026 to 277.5 million units, the weakest quarter in over a decade, because memory and storage now account for more than 60% of a phone’s bill of materials. Chinese vendors were hit hardest. Xiaomi shipments fell 26.3%, OPPO 17.5%, and vivo 19.4%.
Samsung grew. It took 22.6% of the market on 62.7 million units and reclaimed the number one position it had briefly lost to Apple in late 2025. The reason is structural: Samsung buys a meaningful share of its own memory from itself. When component costs spike, a vertically integrated manufacturer can absorb the shock and keep shipping while rivals cut production. Very few companies in the industry can do this. Apple manages it through scale and supplier leverage; Huawei through in-house chip design. Almost nobody else can.
3. R&D spending at a level competitors cannot match
Samsung spent KRW 37.7 trillion on research and development in 2025, a company record and roughly 11% of revenue. That funds simultaneous programs in DRAM, NAND, HBM, foundry process nodes, displays, and mobile devices. The breadth is what matters. It is why Samsung was the first company in the world to mass produce HBM4, shipping commercially in February 2026 on a 4nm logic die with a 12-high stack reaching 3.3 terabytes per second, and the first to sample HBM4E.
4. Legal overhang finally removed from the top of the company
South Korea’s Supreme Court upheld the acquittal of Executive Chairman Lee Jae-yong on July 17, 2025, ending nine years of proceedings tied to the 2015 merger of Samsung C&T and Cheil Industries. The ruling is final and cannot be appealed. For most of the past decade Samsung made capital allocation decisions while its controlling shareholder faced possible imprisonment. That constraint is gone, and it shows in the pace of decision making since: the $16.5 billion Tesla foundry contract, the FläktGroup HVAC acquisition in Europe, and an aggressive capacity expansion at Pyeongtaek.
5. Category leadership that compounds across the portfolio
Samsung remains the leading television manufacturer globally and a top-tier player in displays, home appliances, and, through Harman, automotive audio and connected-car systems. These businesses are no longer where the profit is, but they are where the brand lives, and they give Samsung distribution and shelf presence that a pure semiconductor company would have to buy.
Samsung Weaknesses
1. Profit concentration that would alarm any board
Ninety four percent of Q1 2026 operating profit came from Device Solutions. In practical terms Samsung has become a leveraged bet on the price of DRAM. When memory prices were at their 2023 trough, group operating profit collapsed to KRW 6.6 trillion, roughly one eighth of what a single quarter now produces. The same mechanism that delivered 2026’s records will deliver the reverse when pricing normalizes.
This is the most important weakness in the analysis, and it is the one most SWOT write-ups on Samsung miss entirely because they still treat “diversification” as a strength. Diversification of revenue is not diversification of profit.
2. Foundry is still losing money and still losing to TSMC
Samsung’s contract chip manufacturing business holds roughly 7% of global foundry revenue against TSMC’s approximately 70%. Its 2nm yields reportedly peaked above 60% during Q1 2026, a strong recovery from around 20% in late 2025, but TSMC has been running 70% to 90% on its own 2nm node. Samsung’s own foundry leadership has publicly framed annual profitability as a 2028 target, which is a candid way of saying the division will lose money for at least two more years.
3. Behind in the highest-value memory segment
Samsung leads overall DRAM, but HBM is where AI margin concentrates, and there Samsung is second. Counterpoint Research forecasts 2026 HBM4 share of roughly 54% for SK hynix, 28% for Samsung, and 18% for Micron. Samsung was first to ship the product and still received the smaller allocation, because Nvidia assigns capacity years ahead based on qualification track record. Being technically first does not undo a reputational deficit built over the HBM3 and HBM3E generations.
4. The consumer businesses are being squeezed by Samsung’s own division
There is an uncomfortable internal contradiction in the 2026 numbers. The memory business is profitable precisely because component prices are punishing, and the mobile and appliance businesses are the customers being punished. Samsung’s television and home appliance unit posted an operating loss in the fourth quarter of 2025. Mobile margins are compressing as memory content costs rise faster than retail prices. Group profit is spectacular; the health of the businesses that carry the Samsung brand to consumers is not.
5. Still dependent on Android for the software layer
Samsung sells more smartphones than anyone but does not own the operating system, the app store economics, or the default AI assistant relationship on its own devices. Apple converts roughly four fifths of global smartphone industry profit on a minority unit share precisely because it owns that layer. Samsung’s Galaxy AI features have improved the position at the margins, but the structural asymmetry remains unresolved after fifteen years.
Samsung Opportunities
1. Tesla as the anchor customer that makes Taylor work
The $16.5 billion contract signed in July 2025 runs through 2033 and covers Tesla’s AI5 and AI6 chips. AI5 completed tape-out in July 2026 and will be built on Samsung’s 2nm process at the Taylor, Texas fab, with AI6 allocated to Samsung alone. This matters beyond the revenue. A top-tier customer running its most strategically important silicon on Samsung is the credibility signal the foundry business has lacked since it started losing customers at 3nm.
2. TSMC’s capacity is sold out, and Samsung is the only alternative
TSMC’s advanced node capacity is reportedly booked through 2028. For any company that needs leading-edge wafers before then, there is exactly one other supplier on the planet with a comparable process. Samsung does not need to beat TSMC to win here. It needs to be good enough that scarcity does the selling, and 2nm yields above 60% may now clear that bar.
3. HBM4E and the 2027 accelerator generation
Samsung was first to sample HBM4E, targeting 3.6 terabytes per second, positioning it for Nvidia’s Vera Rubin Ultra in 2027. Allocation for that generation has not been fixed. This is the single clearest path for Samsung to convert technical leadership into the market share it failed to capture in HBM3E.
4. Taking premium and mid-range share while rivals retreat
The memory cost squeeze is forcing Chinese vendors to cut product lines and raise prices. Samsung, with secured internal supply, has been able to hold pricing in India and the Middle East and expand in the budget segment that Chinese brands are vacating. Analysts expect Samsung to keep gaining share through 2026 even as the overall Android market contracts sharply.
5. Redeploying record cash flow
A company generating this much profit has options its competitors do not. The FläktGroup acquisition points toward industrial HVAC as a growth pillar, and robotics, medical imaging, and automotive electronics through Harman are all underweighted relative to what the cash could support. The strategic question is whether Samsung uses this window to buy its way out of profit concentration or simply lets the cash accumulate.
Samsung Threats
1. The memory cycle has never not turned
Every memory supercycle in history has ended the same way: high prices trigger capacity expansion across all suppliers simultaneously, supply overshoots demand, prices collapse, and margins go with them. The mid-1990s cycle saw DRAM prices fall 51% in one year and a further 65% the next. Samsung, SK hynix, and Micron are all expanding capex right now. The current cycle is ASP-driven rather than volume-driven, which analysts read as evidence of genuine scarcity, but it also means the correction arrives the moment pricing normalizes rather than requiring a demand collapse.
2. CXMT is scaling faster than anyone expected
China’s ChangXin Memory Technologies reached 8% of global DRAM revenue in Q1 2026, up from 3% to 4% a year earlier, on roughly 700% year-over-year revenue growth. Its Q1 2026 DRAM average selling prices sat only 5% to 10% below Samsung’s. US export controls keep it out of EUV lithography and therefore out of leading-edge HBM for now, but in commodity DRAM it is already the fourth largest supplier and is roughly doubling wafer capacity. Apple has reportedly been in talks to source from it.
3. Samsung’s own success is destroying its customers’ economics
If memory reaches an estimated 40% of cloud vendors’ capital expenditure by 2027, hyperscalers will respond. That response takes predictable forms: custom memory designs, multi-sourcing to Chinese suppliers, software optimization to reduce memory footprint, and hardware architectures engineered around scarcity. Every one of them erodes pricing power. The same dynamic is visible in phones, where memory costs pushed global shipments to a thirteen-year low.
4. TSMC’s structural lead in foundry
TSMC holds roughly ten times Samsung’s foundry share, better yields, and a customer list including Apple, Nvidia, AMD, Qualcomm, and Broadcom. It is also building in Arizona, which neutralizes the geographic-diversification argument that Taylor was meant to win on. Samsung’s realistic ceiling in this business over the next several years is credible number two, not challenger.
5. Geopolitical and concentration risk in manufacturing
Samsung’s core memory fabrication remains concentrated in South Korea, with Pyeongtaek carrying the critical 1c DRAM expansion. Regional tension, export control changes, tariff policy on semiconductors, and energy costs for EUV-heavy fabs all land on a narrow physical footprint. The Taylor investment reduces this over time but will not materially change the concentration before 2027.
How Samsung compares on the three battlegrounds that matter
| Battleground | Samsung position | Leader | Gap |
|---|---|---|---|
| Overall DRAM | 38% revenue share, ranked first | Samsung | Leading |
| HBM for AI accelerators | 28% forecast HBM4 share | SK hynix, 54% | Roughly 26 points behind |
| Contract chip manufacturing | About 7% revenue share | TSMC, about 70% | Roughly 10x behind |
| Smartphones by volume | 22.6%, ranked first | Samsung | Leading |
| Smartphone industry profit | Minority share | Apple | Structurally behind |
Read together, the table explains the whole strategy. Samsung wins where scale and manufacturing capability decide the outcome. It loses where customer trust, ecosystem lock-in, or accumulated qualification history decide it. Those are much harder problems to solve with capex.
Frequently asked questions
What are Samsung’s biggest strengths in 2026? Leadership in DRAM at 38% revenue share, the number one position in global smartphones at 22.6%, vertical integration that lets it absorb component shocks that cripple rivals, record R&D spending of KRW 37.7 trillion, and a resolved governance situation following the chairman’s final acquittal in July 2025.
What is Samsung’s biggest weakness? Profit concentration. Roughly 94% of Q1 2026 operating profit came from the chip division, which makes group earnings a leveraged bet on memory pricing. Foundry remains loss-making with a stated profitability target of 2028.
Is Samsung ahead or behind in AI chips? Both, depending on the segment. Samsung leads overall DRAM and was first to mass produce HBM4. It trails SK hynix badly in HBM allocation for Nvidia’s platforms, at roughly 28% against 54%.
Who are Samsung’s main competitors? SK hynix and Micron in memory, TSMC in contract manufacturing, Apple and the Chinese vendors in smartphones, and increasingly CXMT in commodity DRAM. Different competitors in each segment is itself a feature of the conglomerate structure.
Why did Samsung’s profit rise so sharply in 2026? AI infrastructure demand created a memory shortage. Server DRAM prices roughly doubled. Because memory manufacturing is a high fixed-cost business, price increases translate almost directly into operating profit, producing a 66% margin in the chip division.
What is the biggest risk to Samsung right now? The memory cycle turning. Every prior supercycle ended in oversupply and price collapse, and all three major suppliers are expanding capacity at once while China’s CXMT scales rapidly at the commodity end.
The Business Model Analyst Take
Samsung in 2026 is the clearest live example we have seen of a company whose reported results and underlying business are telling different stories.
The results are extraordinary and, importantly, real. This is not accounting. Samsung genuinely earned KRW 57.2 trillion in three months because it sells a physical product the world urgently needs and cannot easily get elsewhere. Anyone dismissing this as a bubble is misreading the demand side.
But the composition of that profit is a warning, not a victory lap. A company earning 94% of its profit from one division is not diversified regardless of how many industries it operates in. Samsung’s famous breadth, the appliances and displays and audio systems, currently functions as overhead attached to a memory business, not as a portfolio of hedges. The 2023 trough proved what happens when the memory leg buckles: group profit fell to roughly one eighth of a single 2026 quarter, and nothing else in the portfolio was large enough to matter.
The strategically interesting question is what Samsung does with the cash. There is a window here, probably eighteen to twenty four months wide, in which Samsung can fund almost anything. The obvious moves are the ones already underway: close the HBM gap with SK hynix before the 2027 accelerator generation locks in, and get the Taylor foundry to break-even on Tesla volume. Both are defensible. Neither solves the concentration problem, because both make Samsung more of a semiconductor company, not less.
Our read is that Samsung’s leadership has quietly accepted that. The FläktGroup deal and the robotics and automotive investments are real but small relative to the cash available. The company is behaving like a firm that has decided its future is chips and is using the boom to buy a permanent seat at the leading edge rather than to rebuild diversification.
That is probably the right call. It is also a bet that the AI infrastructure build-out lasts long enough to pay for it. If it does, Samsung emerges from this cycle as a structurally stronger semiconductor company with a credible second-source foundry. If demand normalizes before Taylor ramps and HBM4E allocation is settled, Samsung will have spent its best-ever cash generation on capacity that arrives into a falling market. That is the same mistake the industry has made in every previous cycle, and the reason to take the threat seriously is that Samsung has made it before.