
Samsung and SK hynix rebuilt pay as a slice of operating profit. Now management wants to hand over shares instead of cash, and cut wages when the cycle turns.
South Korea’s matchmakers have repriced memory-chip engineers as the equals of doctors and lawyers, on the strength of bonuses averaging roughly $400,000 at Samsung Electronics and about half a million dollars at SK hynix. That number is real. What almost nobody is pricing is the instrument it comes from: not a salary, but a claim on operating profit that paid zero as recently as 2023, and that both companies are now trying to settle in restricted stock.
On August 4, in the fifth round of this year’s wage talks, SK hynix management put two proposals on the table. Pay more than half of the profit-sharing bonus in company shares, with a lock-up. And allow wages to be adjusted downward if the company posts a loss. Six days later, the Wall Street Journal ran a story about how hard it is for a Samsung engineer to tell whether a date likes him or his bonus.
What Happened
The money is genuinely extraordinary. SK hynix reported second-quarter 2026 revenue of 79.3187 trillion won and operating profit of 60.5426 trillion won, an operating margin of 76%, with revenue up 257% and operating profit up 557% year over year. First-half operating profit came to 98.15 trillion won.
Samsung posted second-quarter operating profit of 89.5 trillion won, up 1,814% year on year, on revenue of 171.5 trillion won. Both companies have crossed a $1 trillion market capitalization, and Korea became the only country outside the United States with two companies worth more than $1 trillion.
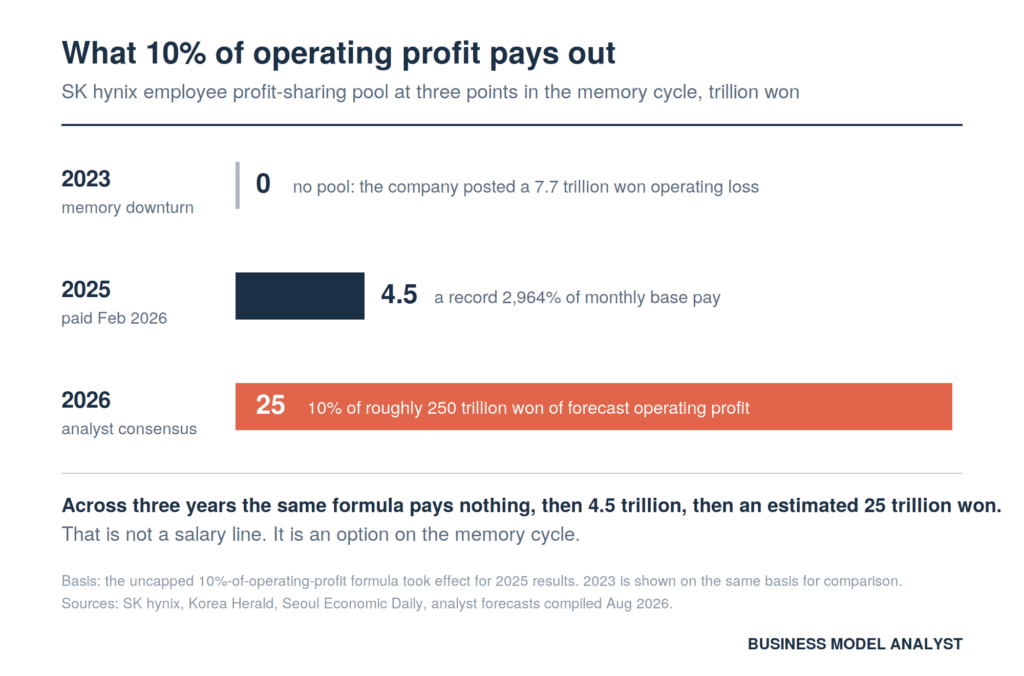
The bonus mechanics that follow from those numbers are equally extraordinary. SK hynix paid employees a record 2,964% of monthly base salary in February 2026 after a 47.2 trillion won operating profit for 2025, under a scheme that allocates 10% of annual operating profit to employee bonuses with no upper limit. That payout came to roughly 4.5 trillion won. Reuters estimates the 2026 average bonus could reach 779 million won per worker.
Against an average Korean salaried wage of about 41.23 million won, that single bonus is worth roughly nineteen years of average pay. It is why the marriage market moved.
The Backstory
Both bonus systems were rewritten in the last twelve months, and both rewrites were won by labor.
SK hynix’s 2025 agreement set a 6% wage increase and made 10% of annual operating profit the funding source for profit sharing, in exchange for scrapping the previous ceiling of 1,000% of base salary. Eighty percent of each individual’s calculated amount is paid in the applicable year and the remaining 20% over the following two years, under a system meant to run for ten years.
Samsung signed its 2026 wage agreement on May 27 after union members approved a last-minute deal that narrowly averted a strike, winning 73.7% support among 62,616 union members who voted. The deal creates a special management bonus for the semiconductor division funded by 10.5% of the division’s operating profit, and revises the regular over-performance incentive, or OPI, which stays capped at 50% of annual salary but will now be funded from 10% of operating profit rather than from economic value added. Samsung will partly fund the special bonuses with company stock over at least ten years, contingent on the chip division exceeding operating profit targets of 200 trillion won for 2026 to 2028, and 100 trillion won from 2029 to 2035.
That OPI change is the detail everyone skipped, and it is the most consequential line in the agreement. Economic value added subtracts a charge for the capital a business consumes. Operating profit does not. In a year when the two companies are pouring hundreds of trillions of won into new fabs, Samsung’s workers negotiated their way out of the one formula that would have shrunk their bonus as the capital base grew. Management did not give that away for free. It got a ten-year lock with profit hurdles attached and the right to settle in shares.
The Plan
The reason management now wants shares is sitting in the capex schedule.
On August 7 SK hynix’s board approved a 54 trillion won investment in new fabs at Yongin and Cheongju: 35.2 trillion won for the Yongin Y2 facility and 19.1 trillion won for the Cheongju M17 plant. That sits inside a broader master plan of 600 trillion won for the Yongin cluster and 100 trillion won for Cheongju. Korean semiconductor equipment stocks jumped on August 10 as the confirmed scale landed in a regulatory filing, on top of an 800 trillion won cluster project in the southwest.
Management’s stated logic is that paying in stock reduces cash outflow while letting employees participate in long-term corporate value, and that securing cash is directly tied to future competitiveness in an industry where advanced fabs cost tens of trillions of won. The talks shifted into this phase after SK Group chairman Chey Tae-won said in mid-July that employees should not become the only happy party at the expense of other stakeholders, and questioned whether performance bonuses hurt shareholders and partners.
The second proposal is blunter. Management wants the ability to adjust wages during a deficit, arguing that a highly volatile memory market needs a structure that shares gains during booms and flexes labor costs during downturns. SK hynix posted an annual operating loss of 7.7 trillion won in the 2023 downturn. The union reads this as a wage cut in a loss year and as management pushing the consequences of its own decisions onto employees, and internal voices have raised the possibility of collective action.
The Business Model Angle
Strip the romance out and what Korea’s two chipmakers have built is a labor cost that behaves like equity.
Upside participation without a cap. Downside exposure that management is now trying to write in explicitly. Settlement in shares rather than cash. A ten-year term with performance hurdles. Deferred vesting, since a fifth of each SK hynix payout is spread over the following two years. Every one of those features belongs to an equity instrument, not a wage.
This is a smart piece of engineering for a company in the most violently cyclical business in technology, which is the argument we made in detail when Wall Street decided Micron was the next Nvidia. Fixed labor cost in a commodity cycle is a solvency problem in the trough. Profit-linked labor cost is a shock absorber: it inflates when there is cash to pay it and deflates to nothing when there is not. Samsung paid no performance bonuses at all after its chip unit posted operating losses through the 2023 memory downturn.
The cost is that management no longer controls the size of the line. At a 10% formula on consensus 2026 profit, the SK hynix bonus pool alone runs to roughly 25 trillion won, close to half the 54 trillion won of fab investment the board approved on August 7. At Samsung, the bonus provision is now large enough to move the reported number: analysts estimate second-quarter operating profit would have exceeded 100 trillion won excluding the performance bonus provisions, against 89.4 trillion won reported. A profit-share that is deducted before the profit line it is calculated from is a genuinely unusual accounting object, and it is why the finance side wants to settle it in paper.
There is a second transfer running inside Samsung that the coverage misses entirely. The MX and Networks unit posted 33.2 trillion won in revenue but an operating loss of 700 billion won for the quarter, as surging component costs wiped out the margin, and the consumer electronics unit also recorded a slight operating loss. Samsung’s phone division is being crushed by memory prices that Samsung’s memory division sets, a squeeze we traced through the value chain when Apple raised prices on almost every Mac and iPad. The engineers collecting $400,000 sit in one division of the same corporate structure as colleagues whose unit just lost money buying their output.
The Risk
The concentration risk here is personal, and it is the part the dating market has not worked out.
An SK hynix engineer’s base salary depends on the memory cycle. Their bonus, which now dwarfs the salary, depends on the memory cycle with leverage. If management wins the stock proposal, more than half of that bonus becomes an illiquid position in a single memory stock, which also depends on the memory cycle. The union’s objection is precise: employees would carry the loss if the share price falls, and earned income tax could be levied on the market price at the grant date, meaning a tax bill struck at the top of the cycle on an asset you cannot sell. The same members are asking for an in-house mortgage facility of around 500 million won, up from the current 100 million won limit, to match Samsung. That would add property leverage on top.
The national version of the same problem is already visible. Korean insurance surrender payouts jumped 16% in the first quarter as households cashed out policies to buy Korean stocks. We covered the distributional fight this is feeding in AI chip riches splitting Korea and Taiwan. The narrower point is that the households closest to the cash flow are the ones least able to diversify away from it.
Timing is the other risk, and it cuts against management. Talks began in late June and have failed through five rounds. Last year’s negotiations did not conclude until September 5. Observers warn that a drawn-out dispute could disrupt the HBM4 production expansion that begins in earnest in the second half. Asking a workforce to swap cash for locked-up stock during a supply crunch is asking from a position of unusual weakness.
The honest counterargument is that the union may be refusing the better trade. SK hynix shares have surged more than 630% over the past twelve months. Employees who took stock in early 2026 rather than cash would have crushed the cash payers. And the cash need is not invented: the fab commitments are real, board-approved, and priced in the tens of trillions.
Quick Questions
How does the SK hynix bonus actually work?
Ten percent of annual operating profit funds a bonus pool with no ceiling. Eighty percent is paid in the year it is earned, and 20% is spread across the following two years. The arrangement is meant to run for ten years.
Why did the bonus formula change at both companies?
Both were rewritten after union pressure. SK hynix traded away a 1,000%-of-base-salary cap for the 10% profit link in 2025. Samsung’s union had sought bonuses equal to 15% of operating profit and the removal of payout caps, and settled on a 10.5% special bonus for the semiconductor division plus a reformulated OPI.
What is “wage adjustment in the event of a deficit”?
A management proposal that would let SK hynix reduce pay if the company posts a loss, on the argument that a volatile memory market needs labor costs that flex both ways. The union treats it as a wage cut and a transfer of business risk to employees.
Has the bonus ever gone to zero?
Yes, and recently. SK hynix lost 7.7 trillion won at the operating line in 2023, and Samsung paid no performance bonus at all after its chip unit’s 2023 losses.
The Business Model Analyst Take
The last line of the Journal’s story is the most financially literate sentence in it. A designer who dated an SK hynix engineer for three years, and has since moved on, says what she really regrets is not buying the stock.
She is right, and she has identified the actual structure of the trade. Proximity to a chip engineer was never the position. The position was always the equity, and what Korea’s two chipmakers have done over the last twelve months is convert their engineers into holders of it, first economically and now, if management wins in August, literally.
That has a clean read for anyone building a compensation system in a cyclical business. Profit-linked pay is not generosity and it is not a bonus in the ordinary sense. It is a transfer of cycle risk from the balance sheet to the household, sold in a boom when the risk looks like a gift. The version workers accept at a 76% operating margin is the same version that pays them nothing at a 7.7 trillion won loss, and the party proposing to settle it in restricted stock during the best quarter in the industry’s history is the party that has run this cycle before.
The marriage market is valuing a doctor’s income. What it is actually looking at is a levered, undiversified, illiquid long position in DRAM.
Based on reporting by Jiyoung Sohn and Sooyoung Rhee for The Wall Street Journal, “The Dating Scene That’s Suddenly Dominated by Chip Nerds,” August 10, 2026, with additional reporting from Seoul Economic Daily, The Korea Herald, CNBC and company filings.