
Tech leaders keep promising humanoid butlers by next year. The robots quietly generating billions have no arms, no legs, and no head, and that gap is the whole business story.
Humanoid robots attract the biggest projections in tech, yet fewer than 10 have moved past small-scale testing, and the best of them work at roughly half a human’s productivity. The robots generating real returns are limbless industrial machines bolted to warehouse floors. The winning form factor is not human-shaped, and that mismatch has quietly become a valuation problem.
This year a humanoid robot named Lightning beat every human in the Beijing half-marathon, then fell over mid-race and needed its handlers to stand it back up so it could finish. A separate startup began taking orders for an $8,000 humanoid that folds laundry, as long as nothing is inside out and you are not washing sheets or blankets. These are the flagships. Meanwhile, the machines actually saving companies money are wheeled units that will never trend on social media.
What Happened
A widely shared analysis from Prof G Media this week laid out the gap between what humanoid robots can do and what their backers claim they will do. The reporting is blunt: one of the top humanoid companies in the world has admitted its robots are, at best, half as productive as the humans they are meant to replace, and even that figure only covers unskilled tasks like stacking boxes and quality control.
The projections point the other way. Nvidia’s Jensen Huang, asked how long until humanoids match human-level ability, answered “this year.” Cathie Wood’s ARK says humanoids will transform home life by 2028, despite her own firm estimating a humanoid is 200,000 times more complex than a robotaxi, a problem no one has solved yet. Elon Musk said two years ago that Tesla would run Optimus robots in its factories in 2025 and ship them to other companies in 2026. Neither has happened at any meaningful scale.
The numbers behind adoption are just as sobering. Fewer than 10% of the humanoid robots built last year were deployed in real applications. Most went to universities for research. No one has yet shown humanoids doing substantive work at scale.
The Backstory
The optimism is not random. It tracks the same curve that made large language models feel inevitable, and people are extrapolating from software to hardware. That extrapolation breaks on physics.
Three constraints keep coming up. Power first: most humanoids run two to four hours per charge, short of a normal shift. Then hands, which turn out to be the hard part. A human hand carries 27 bones, dozens of tendons, and more than 17,000 nerve endings, and Musk himself has called the hand and forearm the majority of the engineering difficulty in the entire robot. Third is data. Robots lack embodied knowledge, the physical sense of where they are and how to move through a space, and acquiring it takes staggering volumes of training data that mostly does not exist yet. A four-year-old child moves through the world more fluidly than any humanoid, and has ingested far more real-world data than the largest language models.
Rodney Brooks, one of the founders of modern robotics, put a timeline on it in late 2025: more than ten years from the first profitable deployment of humanoid robots, even at minimal dexterity.
The Plan
The people building this future are not hedging in public. Musk has said 80% of Tesla’s value will eventually come from Optimus. Figure AI’s founder, like Musk, cites Isaac Asimov’s robot fiction as a formative influence, and the company has raised close to $1 billion at a reported valuation north of $39 billion. The banks have supplied the spreadsheets to match. Morgan Stanley projects more than 1 billion humanoids in use by 2050 and a market near $5 trillion. Goldman Sachs pegs the 2035 total addressable market at $38 billion.
The tell is where the enthusiasm concentrates. Musk manages a company whose valuation increasingly rests on Optimus. Wood runs a robotics ETF. Huang has made robotics one of Nvidia’s largest bets. The projections are not lies, but they are made by the people who most need them to be true.
The Business Model Angle
Here is the part the hype skips. The most successful robotics deployment of the past decade was not humanoid. It was Amazon.
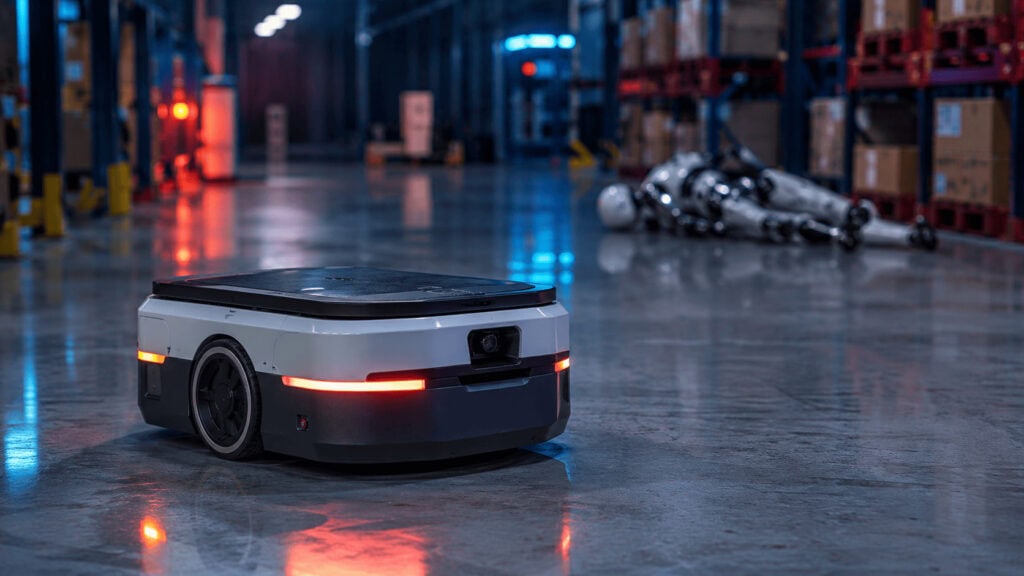
After buying Kiva Systems in 2012, Amazon spent a decade redesigning its warehouses around wheeled robots with no arms, legs, or heads. It now runs more than 1 million of them and books an estimated $4 billion a year in cost savings, and its employees each handle roughly 22 times as many packages as they did a decade ago. The lesson is the opposite of the humanoid pitch. Amazon did not build a robot to fit a human world. It rebuilt the world to fit a cheaper, simpler robot. Retrofitting won, and it was worth every dollar.
This exposes the core contradiction in the humanoid case. Backers argue the human form matters because the world is built for humans, so a human-shaped robot needs no retrofit. But they also argue humanoids will take over dangerous jobs, which are dangerous precisely because those environments are not built for the human body. Not having fragile limbs in a meat-processing plant is an advantage, not a gap to close. The two arguments cancel each other out.
Now look at where capital is going versus where capability is. Robotics startups raised $18.8 billion globally in the first half of 2026, already past the $15 billion raised in all of 2025 and the prior $14.1 billion peak from 2021. Funding is accelerating while deployment sits in the single digits as a share of units built.
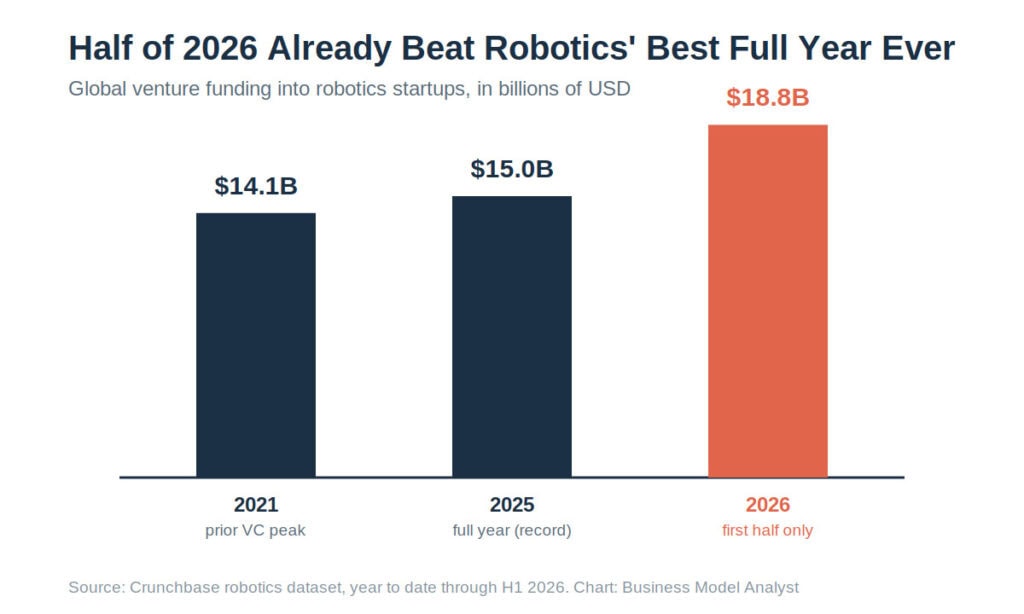
Capital racing ahead of unit economics is not new, and it is not automatically wrong. But it means the valuations are being underwritten by a narrative, not by deployment data. For a business built on physical hardware, that is a fragile place to price a market.
The Risk
The risk is confusing direction with timing. Humanoids may well work eventually, and the industrial robotics market underneath the hype is genuinely booming. US industrial robot installations rose 11% in 2025 after three years of decline, and reshoring plus tariffs could push that further. That is a real, investable trend with real ROI.
The danger is paying humanoid-narrative prices for a capability that Brooks and other researchers put more than a decade out. A record funding year in a hardware category almost guarantees a matching washout when manufacturing reality arrives. The companies with actual multi-year bookings and shippable units will separate hard from the ones selling demo reels. Anyone allocating capital, or writing about where it should go, should watch deployment counts and unit economics, not choreographed stage demos.
Quick Questions
Are humanoid robots making money right now? Not meaningfully. Fewer than 10 companies have moved past small-scale testing, most units built last year went to university research, and the leading operators report productivity around half of a human worker’s on simple tasks.
Which robots are actually profitable? Industrial robots without human form. Amazon’s fleet of more than 1 million wheeled warehouse robots generates an estimated $4 billion in annual cost savings, the clearest robotics ROI of the past decade.
Why do companies keep building humanoids anyway? Partly genuine long-term ambition, partly narrative. Humanoids justify higher valuations and headline-grabbing forecasts, and several of the loudest advocates run funds, ETFs, or companies whose valuations depend on the story landing.
When will home humanoid robots be viable? No credible near-term date exists. A leading robotics researcher estimates more than ten years to the first profitable deployment even at minimal dexterity, and surveys show most consumers are not interested in a household robot to begin with.
The Business Model Analyst Take
The humanoid robot is a category where the form factor is doing marketing work, not economic work. Investors are being asked to price a science-fiction outcome on a hardware timeline, and the two do not match.
The useful frame for founders and operators is to separate the form factor from the function. The function, automating physical labor, is real and already profitable. The form factor, a machine shaped like us, is the expensive, unsolved, emotionally appealing part that keeps attracting capital out of proportion to its results. Tesla is the cleanest example of the tension, since a growing share of its valuation now rests on Optimus rather than on the cars that actually generate revenue, a bet our Tesla SWOT analysis treats as long-dated and unproven. The counter-model is Amazon, which got rich on robotics by refusing to make its robots look human.
If you want the durable read: bet on the function, be skeptical of the form, and treat any humanoid ROI forecast dated before the mid-2030s as a valuation tool rather than a plan.
Based on reporting from Prof G Media (Mia Silverio), with data from Morgan Stanley, Goldman Sachs, Crunchbase, the Financial Times, and Scientific American.