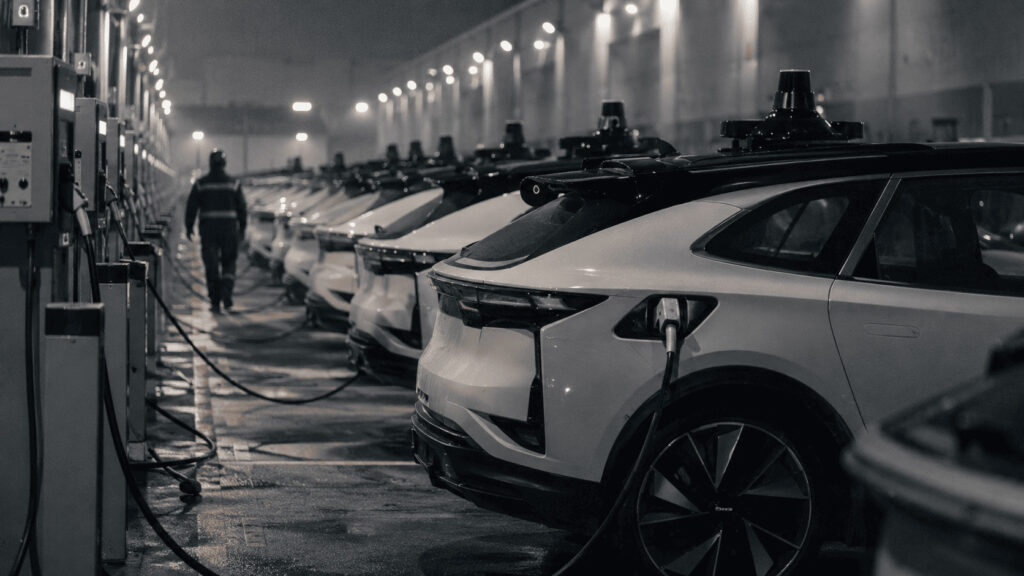

Everyone is racing to build the smartest self-driving brain. The real money is hiding in the parts nobody wants to touch.
The robotaxi race won’t be won by the best self-driving AI. According to a VC stack breakdown making the rounds, the AI itself is just 7% of what a ride actually costs. The biggest slice, at 37%, is unglamorous fleet operations: cleaning, charging, depots, and maintenance.
Picture this. A driverless car glides up to the curb, no human behind the wheel, looking like the future finally showed up on schedule. But before that car ever rolled to your address, someone charged it overnight, vacuumed the back seat, swapped a worn tire, and routed it back to a depot. That someone, it turns out, is sitting on the most valuable real estate in the whole business.
What Happened
One of the founders backed by a venture investor, Kieran White, mapped the full robotaxi cost stack. The takeaway flips the popular assumption on its head. The flashy self-driving software, the thing every headline obsesses over, came in at just 7% of the cost of an actual ride. Fleet operations, the boring physical layer, came in at 37%, the single biggest chunk of the whole pie.
In other words, the layer everyone is fighting over is the smallest line item. The layer nobody wants is the largest.
The Backstory
For years, the robotaxi story has been an AI story. Whoever builds the smartest driving brain wins, or so the thinking goes. The entire narrative has orbited around names like Waymo and Tesla and the question of who can teach a car to handle a tricky left turn in the rain.
That framing made sense. Self-driving is genuinely hard, and the engineering is genuinely impressive. But it also quietly trained everyone to look in exactly one place, and to ignore the unglamorous machinery that actually keeps a fleet of cars on the road.
The Plan
The breakdown reframes the whole opportunity. If AI is only 7% of the cost, then 93% of the value sits in everything else. And the single fattest slice of that, 37%, is the operational layer nobody is racing to build.
The argument is simple: the real companies will get made in the boring layer. Charging networks, depot logistics, cleaning, maintenance, the physical plumbing of a driverless fleet. The flashy layer gets the headlines. The boring layer gets the profits.
The Business Model Angle
This is a picks-and-shovels play, and it is one of the most reliable patterns in business history.
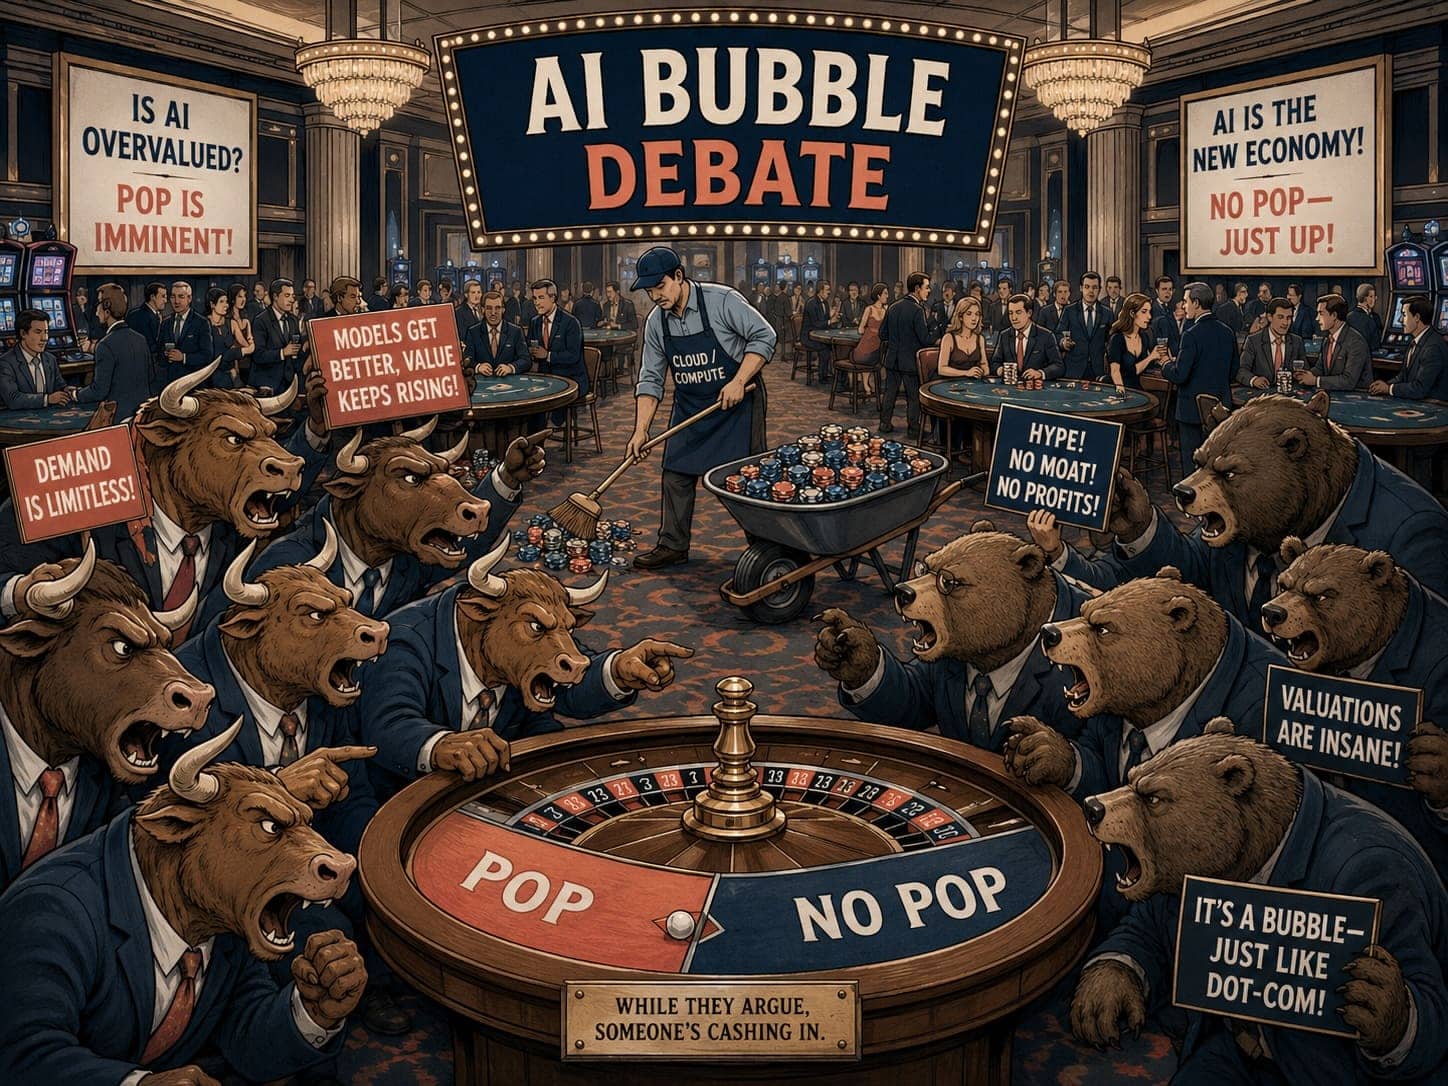
The source nails the analogy. In the AI gold rush, everyone chased the model. The fortunes, though, got made selling the picks and shovels underneath: the chips, the cloud, the tooling. The miners came and went. The suppliers got rich either way.
Robotaxis look like the same movie. When every founder and every dollar crowds into the glamorous layer, that layer gets competitive, expensive, and margin-thin fast. The durable money often hides one level down, in the infrastructure everyone assumed was someone else’s problem. It is the same lesson that made ride-hailing economics so brutal for the platforms but so interesting underneath. If you want a primer on how the layer above works, our breakdown of the Uber business model is a good place to start.
The lesson for founders: when the crowd runs at the shiny thing, look at what the shiny thing depends on.
The Risk
Now the honest counterpoint, because this is one breakdown, not gospel.
First, this is a single investor’s cost map, not an industry-audited model. And the person making the argument backs founders building in exactly that boring layer, so there is a built-in incentive to make the boring layer look like the promised land.
Second, those percentages are a snapshot, not a law of physics. As fleets scale, automation will come for cleaning, charging, and maintenance too, which could shrink that 37% over time. Meanwhile the AI layer can keep compounding in strategic value even if its per-ride cost share stays small.
Third, and most important: boring does not automatically mean profitable. Depots, charging, and maintenance are capital-heavy, operationally messy, and low-margin in plenty of other industries. Being the biggest cost line is not the same as being the best business. Sometimes the largest slice of the pie is large precisely because it is hard and expensive to run.
Quick Questions
Wait, AI is really only 7% of a robotaxi ride’s cost?
That is the figure from the stack breakdown going around. The self-driving software, the part everyone fixates on, lands at roughly 7% of what a ride costs. The rest is everything else it takes to actually run a fleet.
So what is the most expensive part of a robotaxi ride?
Fleet operations, at 37%, the single biggest slice. That is the unglamorous stuff: cleaning the cars, charging them, running the depots, and keeping them maintained.
What does “picks and shovels” mean here?
It is the gold-rush idea that you often make more money selling tools to the miners than mining yourself. In robotaxis, that means the boring operational and infrastructure layer underneath the self-driving cars, not the cars’ AI itself.
Is this a real startup opportunity or just VC hype?
Probably some of both. The pattern is real and well-documented, but the breakdown comes from someone who invests in that exact layer, so treat the framing as a thesis to pressure-test, not a guarantee.
The Business Model Analyst Take
The headline tech is rarely where the durable money lives. Robotaxis are following the same script as the AI boom: everyone sprints toward the model, while the unglamorous infrastructure underneath quietly becomes the real business. For founders and operators, the move is not to chase the layer everyone is already crowding. It is to ask what that layer can’t run without, and go build that. Boring, in business, is frequently where the margins hide. Just remember that “biggest cost line” and “best business” are not the same sentence, so pressure-test the boring layer as hard as you would the shiny one.
Source: the original robotaxi cost stack breakdown on Instagram.