
Robinhood spent its first decade being underestimated. It was the free-trading app that let college kids buy meme stocks, the platform blamed for gamifying the market, the company that halted GameStop trades and got hauled before Congress. In 2025 it stopped being a punchline. Robinhood posted record revenue of $4.5 billion, its first back-to-back years of GAAP profit, and a stock that roughly tripled. CEO Vlad Tenev now describes the company not as a brokerage but as a “financial super app,” and for the first time the numbers make that ambition hard to dismiss.
This SWOT analysis breaks down where Robinhood is genuinely strong, where the model is still fragile, and which of its many new bets actually matter. The short version: the growth is real, but so is the dependence on volatile trading and a regulatory environment that keeps circling.
What is a SWOT analysis? A SWOT analysis is a strategic planning tool that maps a company’s internal Strengths and Weaknesses against its external Opportunities and Threats. Strengths and weaknesses are things the company controls, such as its brand, margins, and product mix. Opportunities and threats come from outside, such as market trends, regulation, and competitors. For Robinhood, the split matters: its strengths are impressive, but most of its risks sit in that external column.
Robinhood at a Glance
| Metric | Detail |
|---|---|
| Company | Robinhood Markets, Inc. |
| Founded | 2013, by Vlad Tenev and Baiju Bhatt |
| Headquarters | Menlo Park, California |
| CEO | Vlad Tenev (Chairman and CEO) |
| Ticker | NASDAQ: HOOD |
| 2025 revenue | $4.5 billion (up 52% year over year) |
| 2025 net income | $1.9 billion (diluted EPS of $2.05) |
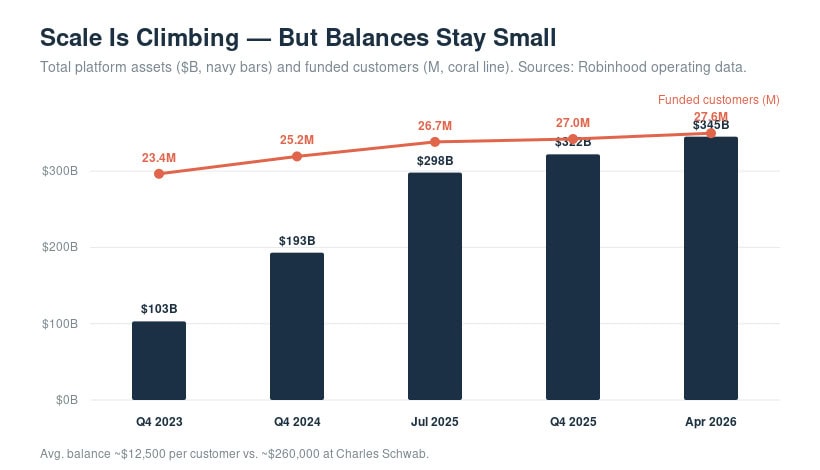
| Funded customers | 27.6 million (April 2026) |
| Total platform assets | ~$345 billion (April 2026) |
| Gold subscribers | 4.34 million (~16% of customers) |
| Market cap | ~$100 billion (mid-2026) |
The business now earns money across three broad buckets: transaction fees (options, crypto, equities, and other trading), net interest revenue (on cash, margin loans, and securities lending), and subscription and other revenue (mostly Robinhood Gold). That mix is the whole story of the turnaround, and it is worth keeping in mind through every section below. For the underlying mechanics, see our breakdown of how Robinhood makes money and the full Robinhood business model.
Strengths
| Strength | Why it matters |
|---|---|
| Record financials | $4.5B revenue and $1.9B profit in 2025, a genuine turnaround from years of losses |
| Recurring revenue engine | 4.34M Gold subscribers and ARPU up to $191 reduce reliance on pure trading |
| Product velocity | 11 separate business lines each generating ~$100M or more in annualized revenue |
| Brand with young investors | The default first brokerage for a generation, and the front door to the wealth transfer ahead |
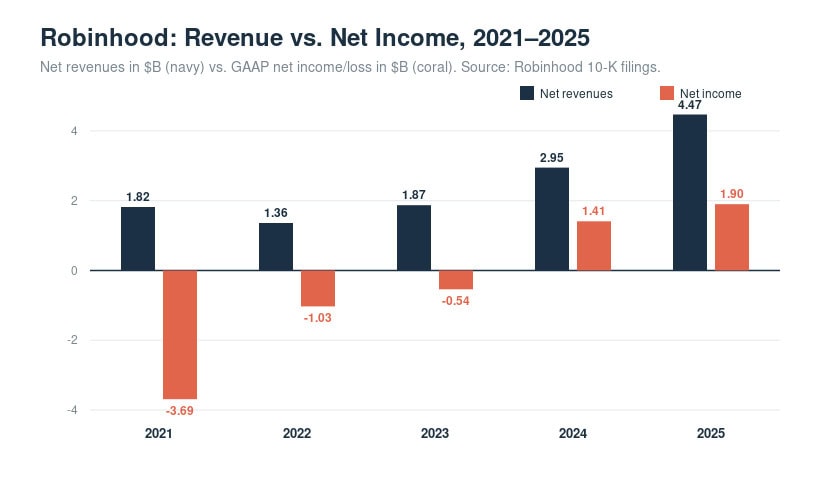
The financial turnaround is the headline strength. For three straight years Robinhood lost money, including a brutal $3.7 billion loss in 2021. Then the model flipped. In 2024 it earned $1.4 billion, and in 2025 it set records almost everywhere: revenue up 52% to $4.5 billion, net income of $1.9 billion, net deposits of $68 billion, and diluted EPS of $2.05. This is no longer a growth-at-any-cost story. It is a profitable business throwing off enough cash to buy back stock, with more than $1.2 billion in repurchases completed by early 2026.
Recurring revenue is finally meaningful. Robinhood Gold, the $5-a-month (or $50-a-year) subscription, reached 4.34 million subscribers, up 58% year over year, and roughly 16% of all customers now pay for it. Gold subscription revenue alone hit $50 million in a single quarter. Average revenue per user climbed to $191. Every dollar that shifts from unpredictable trading commissions toward predictable subscriptions and net interest makes the whole company more durable, and that shift is well underway.
Product velocity is the real competitive weapon. Robinhood ships fast, and by late 2025 it counted 11 distinct business lines each pulling in $100 million or more in annualized revenue. That includes options, crypto, equities, futures, index options, securities lending, Gold, its cash card, retirement accounts, prediction markets, and more. Few fintechs launch and scale new products at this pace, and each new line both deepens engagement and spreads the revenue base wider.
The brand is a genuine moat with young investors. Robinhood is, for millions of people, the first place they ever bought a share of stock. That default position matters enormously as an estimated $124 trillion in wealth transfers to younger generations through 2048. A cheap, familiar app that a 25-year-old already trusts is extremely well placed to hold those relationships as those customers age and their balances grow.
Weaknesses
| Weakness | Why it matters |
|---|---|
| Small account balances | ~$12,500 average per customer versus ~$260,000 at Charles Schwab |
| Trading-dependent revenue | Options, equities, and crypto fees rise and fall with market sentiment |
| Crypto volatility | Crypto revenue fell 38% year over year in Q4 2025, dragging down the quarter |
| Compliance record | More than $80 million in fines between 2023 and 2025 |
The average account is still tiny. This is the number that keeps Robinhood honest. With roughly $345 billion in platform assets spread across 27.6 million customers, the average balance is about $12,500. Charles Schwab, by comparison, holds more than $12 trillion in client assets with an average account near $260,000. Robinhood has the users; it does not yet have their serious money. Until those balances grow, its net interest and asset-based revenue are capped well below what the customer count might suggest.
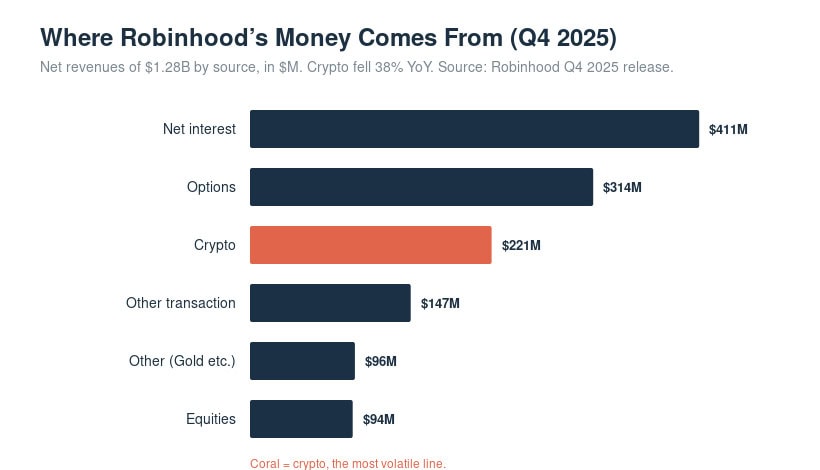
Revenue is hostage to market conditions. A large share of Robinhood’s income depends on people actively trading, and trading volume tracks sentiment. When markets are hot and volatile, revenue surges. When they cool, it can fall just as fast. The Q4 2025 results made this concrete: overall revenue still grew 27%, but the quarter missed forecasts because crypto revenue fell 38% year over year to $221 million. One soft asset class was enough to spook investors and knock the stock lower after hours.
The compliance ledger is a recurring cost and reputational drag. Between 2023 and 2025 Robinhood paid more than $80 million in fines across securities violations, identity-verification failures, crypto withdrawal issues, and product-oversight shortcomings. Newer probes keep arriving: Florida has investigated Robinhood Crypto over alleged deceptive marketing, and Lithuania’s central bank has reviewed its tokenized equity products. Individually these are manageable. Collectively they signal a company whose “move fast” instinct repeatedly outruns its controls.
Opportunities
| Opportunity | Why it matters |
|---|---|
| Tokenization and Robinhood Chain | Own blockchain plus tokenized stocks could open a new, higher-control revenue layer |
| Prediction markets | Hit record volumes and may become a major line beyond crypto |
| Banking and wealth management | Gold credit card, banking, and Robinhood Strategies push into recurring finance |
| Global expansion | EU tokenized stocks, Singapore, Toronto, and Asia-Pacific acquisitions |
Tokenization is Robinhood’s biggest structural bet. In mid-2026 the company launched the public mainnet for Robinhood Chain, its own Ethereum layer-2 built on Arbitrum, alongside tokenized stocks and decentralized lending. The pitch is to become the front door to a faster, more global, more speculative version of markets where stocks, tokens, derivatives, and prediction contracts all sit in one app. If tokenized equities gain traction, Robinhood captures a revenue layer it controls end to end, rather than routing orders to third parties. It is early and unproven, but the upside is large.
Prediction markets arrived faster than expected. Event contracts on outcomes such as elections and sports have posted record volumes and are emerging as a potential major revenue driver in their own right. They plug neatly into Robinhood’s young, engagement-hungry base and give the company a second speculative growth engine that does not depend on crypto prices.
Banking and wealth management deepen the wallet. Robinhood Banking, a Gold credit card, a Platinum tier, and the Robinhood Strategies managed-portfolio product (already past 100,000 funded customers) all push the company beyond trading into everyday finance. AI features like Robinhood Cortex, an assistant now rolling out across the app, add stickiness and justify the premium tiers. The strategic logic is clear: own more of each customer’s financial life, and the account balances that today look small start to climb.
International expansion widens the runway. Robinhood is offering tokenized US stocks and ETFs across 31 EU and EEA countries with nearly 24/5 trading, launching brokerage in Singapore, opening an office in Toronto, and pursuing acquisitions in Indonesia. Its core US market is maturing; geographic expansion is how it keeps the funded-customer count growing.
Threats
| Threat | Why it matters |
|---|---|
| Intense competition | Schwab, Fidelity, and Interactive Brokers plus Coinbase, Kraken, Kalshi, and Polymarket |
| Regulatory pressure | Ongoing scrutiny of PFOF, crypto rules, and tokenization |
| Rate and cycle sensitivity | Net interest and trading revenue both move with rates and sentiment |
| Stock volatility | Beta near 2.4 makes HOOD swing far harder than the market |
Robinhood is now fighting on two fronts at once. On one side sit the incumbents: Charles Schwab, Fidelity, and Interactive Brokers, all vastly larger, all offering commission-free trading, and all with the deep balances Robinhood lacks. On the other side sit the crypto-native and prediction-market challengers: Coinbase (which has begun adding stock trading), Kraken, Hyperliquid, and prediction venues Kalshi and Polymarket. Robinhood’s edge is that it bundles all of this in one app, but that also means it has no single lane it can defend without a rival attacking it. For a fuller map of the incumbent landscape it competes against, see our analysis of Fidelity’s main competitors.
Regulation is the standing external risk. Payment for order flow, the arrangement where market makers pay Robinhood to route trades, remains a periodic target of regulatory scrutiny and is still central to the transaction-revenue model. Crypto rules keep shifting, and tokenized equities face an uncertain legal path, especially in Europe. Any of these could force changes to how core lines make money.
Macro sensitivity cuts both ways. Robinhood’s net interest revenue benefits from higher rates, while its trading revenue benefits from bullish, volatile markets. A scenario of falling rates and a flat, quiet market would pressure both engines at once. The business is built for excitement, and long stretches of boredom are its natural enemy.
The stock itself is a threat to sentiment. HOOD carries a beta around 2.4, meaning it moves roughly twice as hard as the broad market. It touched a 52-week high near $153 in October 2025 before pulling back toward $100. That volatility can feed on itself, shaping headlines and customer confidence in a company whose brand is tied to the market’s mood.

How Robinhood Stacks Up Against Competitors
The competitive picture is best understood by size and by lane. Against the incumbents, Robinhood is small on assets but fast on features. Against the crypto and prediction upstarts, it is the more established, better-capitalized brand.
| Company | Edge over Robinhood | Robinhood’s edge |
|---|---|---|
| Charles Schwab | ~$12T+ in client assets, huge average balances, full advisory | Simpler app, younger base, faster product cycle |
| Fidelity | Deep research, retirement dominance, trust with older investors | Mobile-first design, crypto and prediction markets |
| Interactive Brokers | Professional-grade tools, global reach, pricing for active traders | Mainstream accessibility, brand with new investors |
| Coinbase | Crypto-native depth and infrastructure | Broader multi-asset app, stocks plus options plus events |
| Kalshi / Polymarket | Prediction-market focus and liquidity | Bundled into one app alongside every other asset |
The pattern is consistent. No single competitor beats Robinhood on everything, but every competitor beats it on something. Robinhood’s whole strategy is a bet that bundling wins: that a young investor would rather do stocks, options, crypto, prediction markets, and banking in one familiar app than assemble a stack of specialists. So far, the funded-customer growth suggests that bet is working.
Frequently Asked Questions
Is Robinhood profitable in 2026? Yes. Robinhood reported record net income of $1.9 billion for full-year 2025, its second consecutive profitable year, and entered 2026 with continued revenue growth. This follows three straight years of losses from 2021 to 2023.
How does Robinhood make most of its money? Through three main channels: transaction-based revenue from options, crypto, and equities trading; net interest revenue from cash, margin lending, and securities lending; and subscription revenue, mostly from Robinhood Gold. Trading fees remain the largest single bucket, which is why crypto and market swings move results so much.
What is Robinhood’s biggest weakness? Small account balances. The average funded customer holds around $12,500, versus roughly $260,000 at Charles Schwab. Robinhood has the users but not yet their serious long-term money, which caps its asset-based revenue.
Who are Robinhood’s main competitors? Traditional brokerages Charles Schwab, Fidelity, and Interactive Brokers on one side, and crypto and prediction-market platforms such as Coinbase, Kraken, Kalshi, and Polymarket on the other. SoFi and Webull also compete for the same younger retail traders.
What are Robinhood’s biggest growth opportunities? Tokenization (including its own Robinhood Chain blockchain and tokenized stocks), prediction markets, banking and wealth management products, and international expansion across the EU, Singapore, and Asia-Pacific.
Why is Robinhood stock so volatile? HOOD has a beta near 2.4, so it tends to move about twice as much as the broad market. Because so much of its revenue depends on trading activity and crypto prices, the stock amplifies both optimism and fear about market conditions.
The Business Model Analyst Take
Robinhood’s 2025 was a legitimate breakout, and the bears who spent years calling it a gambling app for broke twenty-somethings now have to reckon with $1.9 billion in profit and a super-app strategy that is actually shipping. The strengths are real and, importantly, they are compounding: recurring Gold revenue, a widening product base, and a brand that owns the on-ramp for a generation of investors.
But the central tension has not gone away. This is still a company whose fortunes rise and fall with how excited people feel about markets, and whose biggest opportunities, tokenization and prediction markets, are also its biggest regulatory exposures. The $12,500 average balance is the tell. Robinhood has won the customers; the next decade is about whether it can win their wealth as those customers grow up, or whether Schwab and Fidelity simply wait for those balances to matter and then compete for them directly.
Our read: Robinhood has earned its re-rating, but the model is optimized for a fast, speculative, engaged market. The strategic question for 2026 and beyond is not whether it can launch new products. It clearly can. It is whether it can convert a generation of small, active accounts into large, loyal ones before its rivals, on either front, get there first.