
Barge freight from Rotterdam to southern Germany costs seven times normal. The fleet that could handle it was never built, because nobody had a reason to build it.
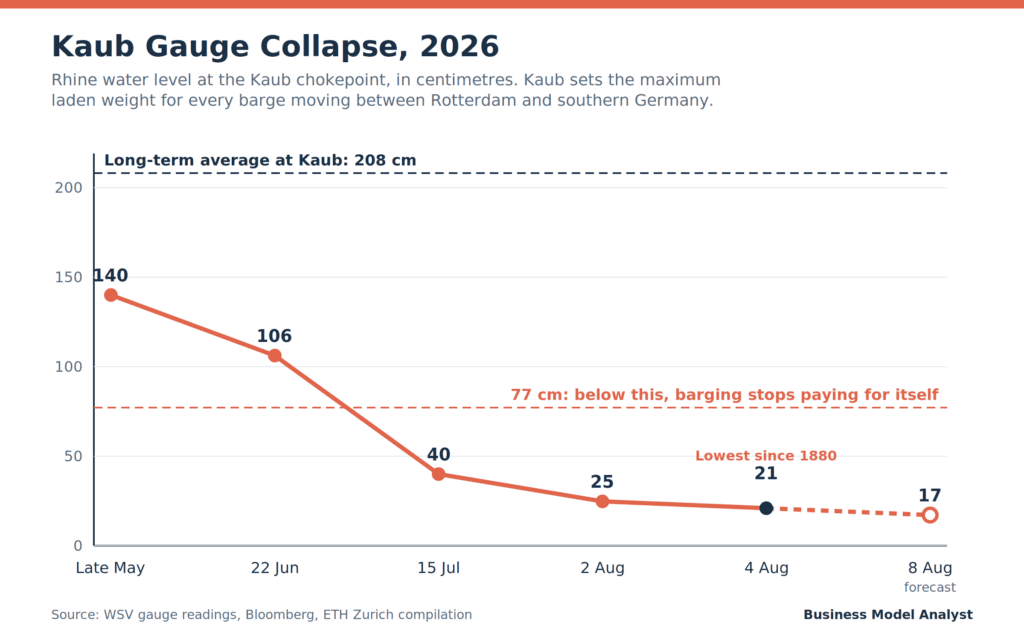
Water at the Kaub chokepoint fell to 21 centimetres on 4 August 2026, the lowest reading since German officials started measuring in 1880, with forecasts pointing to 17 centimetres within days. Barges that normally haul 5,100 tonnes past Kaub are moving about 800. Freight from Rotterdam to points south of the chokepoint has reached roughly €150 per tonne against €20 in normal water. The Kiel Institute for the World Economy puts the third-quarter hit to German GDP at 0.1% to 0.2%, or $1.2 billion to $2.3 billion. Of the roughly 8,000 cargo vessels working the Rhine, about a dozen were designed to run in shallow water.
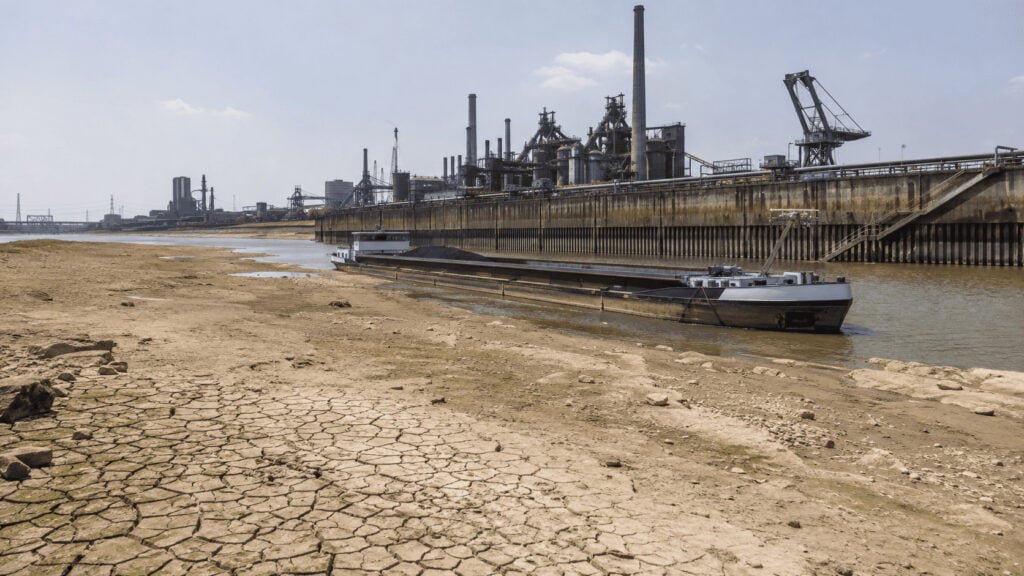
Wilma van Ingen brought the W. De Beijer Sr up from Rotterdam this week loaded with iron ore. The push freighter runs 564 feet and carries 5,000 tonnes when the river cooperates. She came into Duisburg with 1,200.
That is the whole story of German industrial competitiveness in one number. Not the energy price, not the tariff schedule, not the Chinese export flood. A boat carrying a quarter of what it was built to carry, on a river that BASF, Bayer, Mercedes-Benz and ThyssenKrupp all built their plants against on the assumption that bulk transport would stay cheap forever.
What Happened
The Kaub gauge sits on the Middle Rhine between Koblenz and Mainz, at the shallowest point on the entire river. Every barge running between the Amsterdam-Rotterdam-Antwerp port complex and the industrial hinterland of Germany, France and Switzerland loads to whatever Kaub allows that morning.
Kaub averages 208 centimetres. In a normal August it sits above two metres. On 4 August it read 21, and the German Federal Waterways and Shipping Administration expects 17 by the weekend.
At 40 to 50 centimetres, vessels carry about a fifth of normal cargo. Below 30, most of the fleet cannot pass Kaub at all. A handful of specialised shallow-draft vessels still make the run, and their crews need detailed knowledge of the shoals to do it safely.
Prices moved the way you would expect when capacity vanishes on a route with no substitute. The benchmark oil and liquid-bulk rate from Rotterdam to German cities south of Kaub rose about 400% in two months. Container operators are charging low-water surcharges reaching €1,000 per box. The Rotterdam-to-southern-Germany rate broke the €130 per tonne record set during the 2022 drought and kept going.
Consumers see it at the pump. The German cartel office reports petrol shipped by river costs drivers up to 11 cents more per litre.
Downstream at Duisburg, the world’s largest inland port, chief executive Markus Bangen says his operation is working at its limit. Duisburg handles roughly 100 million tonnes and more than 20,000 ships a year. Lighter loads mean more trips, and port calls across the system have climbed 50% to 60% in recent weeks.
The Danube is in the same condition. Hungary and Romania have curbed nuclear generation because they cannot draw enough cooling water, and both governments have asked households and businesses to cut consumption.
The Backstory
Germany has run this experiment before. The 2018 drought shut factories and cost roughly 0.3 percentage points of GDP growth. In November of that year, industrial production fell 1.5%.
Kiel Institute economists Nils Jannsen and Saskia Meuchelböck later built the model everyone now quotes: when Kaub stays below 78 centimetres for a full month, German industrial production drops about 1%. Inland shipping accounts for a small slice of total German freight tonnage, but it moves the goods that sit at the top of the production chain. Around 30% of coal, crude oil and coke oven products travel by water. Choke that and the disruption propagates down through every stage that follows.
After 2018, German industry did respond. BASF commissioned the Stolt Ludwigshafen, a 135-metre by 30-metre vessel built from light materials specifically to run in extreme low water, and put it into service in 2023. Siemens Energy expanded deep-water port storage because its 300-tonne turbines cannot travel by rail or road at all. K+S built wastewater storage basins at its Werra plant. EnBW stockpiles fuel for its coal plants whenever a unit goes offline.
Bangen at Duisburg says the measures are working and the port sits in a better position than it did eight years ago. He is right in a narrow sense and wrong in a broader one. The fleet did not change. Of nearly 8,000 cargo ships plying the Rhine, roughly a dozen carry a low-water design. Newer hulls use multiple small propellers or shielded encasements, because a single large propeller stops working in shallow water. Twelve out of eight thousand is not a transition.
The Plan
Transport Minister Steffen Bilger convened industry executives, shipping operators and port bosses in Bonn on 6 August to hunt for something practical.
The structural fix has been sitting on the shelf for a decade. Abladeoptimierung Mittelrhein would deepen the fairway between Mainz and St. Goar to a continuous 2.10 metres at the reference low-water level across the full 120-metre channel width. The German federal transport plan assigned it a benefit-cost ratio of 30.7, the highest of any waterway project in the country, and parliament wrote the requirement into law in December 2016. Ships would carry about 45 more tonnes on average, taking roughly 100,000 truck journeys off German roads every year.
Ten years after that law passed, the waterways authority held a scoping meeting in Bingen in April 2026 for the first sub-section. No dirt has moved.
Companies are doing the only thing available in the meantime. BASF normally ships about 40% of the freight at its Ludwigshafen complex by water and is pushing what it can onto trucks and rail. Shell has diverted deliveries from its Rhineland refinery to rail, road and pipeline while leaning harder on storage. Thyssenkrupp chartered shallow-draft vessels to keep raw materials reaching its Duisburg blast furnaces. Lanxess stood up a crisis team. Evonik has already seen production affected at its Marl chemical park.
The road-and-rail escape route is narrower than it looks. Replacing a single barge takes up to 100 trucks or an entire freight train, and major construction on the line along the Rhine’s eastern bank is restricting rail capacity between Cologne and the Rhine-Main region right now. Carsten Brzeski of ING, who rows on the Main and has watched the water drop for twelve years, describes German railways as a disaster in their own right.
The Business Model Angle
German heavy industry treated the Rhine as fixed infrastructure and it behaves like a spot market.
BASF, Covestro, Shell and Thyssenkrupp all sited enormous fixed assets along a corridor because water transport was the cheapest way to move bulk material, and they capitalised that assumption into plant location decisions that cannot be reversed. Covestro moves more than 30% of its finished products and brings in close to 75% of its raw materials on the river. That is not a logistics preference. That is a balance sheet built on a variable priced by rainfall in the Alps.
The barge market makes the problem self-sustaining. When Kaub drops, operators earn far more for moving far less. A rate that goes from €20 to €150 per tonne means the same hull generates more revenue at a fifth of the payload. Scarcity pays the incumbent fleet. Building a low-water vessel costs more upfront, and a wide shallow hull with multiple small propellers burns more fuel per tonne in normal water than the conventional design it replaces. The vessel earns a premium during droughts and a penalty the rest of the time, while the operator who skipped the capex collects the drought premium anyway through surcharges. Twelve low-water ships out of eight thousand is what that arithmetic produces.
Shippers reached the rational conclusion and started leaving. Inland waterway transport fell from 4.7% of total German freight in 2017 to 4.1% in 2024. Cargo owners de-risked by exiting the mode rather than fixing it, which shrinks the volume base that would fund fleet renewal and hands politicians a smaller constituency for the dredging project. Each drought accelerates the exit.
What German industry bought after 2018 was optionality, not capacity. Storage tanks, deep-water buffer stock, multi-modal contracts and crisis teams all work, and all of them consume working capital permanently to insure against a seasonal event. BASF CEO Markus Kamieth says the company is carrying inflated logistics costs and is not worried about the quarter. That confidence has a price, and it now sits in the cost structure of every German chemical plant on the river, every year, drought or not. Add it to energy prices and US tariffs and you get a fair description of why Germany grew 0.2% last quarter.
The Risk
Kiel puts the third-quarter drag at 0.1% to 0.2% of GDP, which sounds survivable until you set it against 0.2% growth in the second quarter. Brzeski expects a bigger hit than 2018 and points to the calendar: the Rhine usually bottoms out in September or October, and 2026 arrived at a record low in the first week of August with no rain forecast.
The duration matters more than the depth. Kamieth has flagged possible force majeure declarations. JPMorgan’s Chetan Udeshi told clients that if levels persist the way they did through the second half of 2018, German chemical names face additional downside to second-half expectations, though smaller given post-2018 mitigation.
The second-order risk is the one nobody is pricing. Every drought that pushes another cargo owner off the water permanently shrinks the revenue pool that funds barge fleet renewal and weakens the political case for spending on the fairway. A route with a benefit-cost ratio of 30.7 that has produced one scoping meeting in ten years is not going to be rescued by urgency. Switzerland, which takes about 30% of its mineral oil products up the Rhine from ARA, has fewer alternatives than Germany does.
Quick Questions
Why does one gauge reading control the whole river? Kaub marks the shallowest point on the navigable Rhine. A barge loads for the worst spot on its route, so Kaub sets the maximum laden weight for the entire Rotterdam-to-Basel corridor. Carriers also use it as the reference for low-water surcharges.
Can trucks and trains absorb the cargo? Partially and expensively. One barge equals up to 100 trucks or a full freight train, German rail already runs tight, and construction is restricting the line between Cologne and the Rhine-Main region. Siemens Energy’s 300-tonne turbines cannot go by road or rail at any price.
Why hasn’t the fleet been rebuilt? Low-water vessels cost more and run less efficiently in normal conditions, while conventional operators capture the drought premium through surcharges without spending the capital. About a dozen of the roughly 8,000 Rhine cargo ships carry a low-water design.
Is this worse than 2018? Lower and earlier. Kaub broke the 1880 record in the first week of August, weeks ahead of the usual seasonal trough. Whether the economic damage exceeds 2018 depends on how long it lasts, not how low it goes.
The Business Model Analyst Take
The Rhine story gets filed under climate, and it belongs under capital allocation.
German industry has spent eight years insuring against low water instead of fixing it, and the insurance shows up as permanent working capital sitting in storage tanks and buffer stock rather than in plants or products. The fix that would actually change the physics returns 30 times its cost and has produced a scoping meeting. The fleet that would carry cargo through a drought numbers twelve vessels, because scarcity pays the operators who did not build one.
The pattern generalises well beyond the Rhine. Any business that sits on infrastructure it does not own and cannot influence has an input priced by someone else’s weather, someone else’s regulator or someone else’s balance sheet. The costs get treated as fixed until the day they are not. Covestro can tell you what 75% raw material dependence on a single corridor is worth in a dry August.
For anyone running a supply chain, the question worth asking this week is not whether your logistics are cheap. It is what your cheapest route costs when it stops working, who captures that money, and whether anybody in the chain has a commercial reason to prevent it.