
Revolut SWOT Analysis at a Glance
What it is: A strategic assessment of Revolut Group Holdings Ltd, the London-headquartered financial technology company that operates a multi-product banking app in 40 markets.
Where it stands (FY2025): Revenue of £4.5 billion (about $6.0 billion), up 46%. Profit before tax of £1.7 billion, up 57%, at a 38% margin. 68.3 million retail customers and 767,000 business customers. Fifth consecutive profitable year.
Core strength: Six revenue engines, none of them larger than 22% of the mix, running on a single technology platform.
Core weakness: Revolut monetises each customer worse than its main global rival and remains the UK’s most complained-about firm for fraud.
The strategic question: Can a company built on cheap FX and card interchange become a real bank before its valuation demands that it already is one?
Revolut spent a decade being described as a travel card that got lucky. The 2025 numbers make that description untenable. Revenue reached £4.5 billion, profit before tax hit £1.7 billion, and the company closed the year with 68.3 million retail customers, having added 16 million in twelve months. It is now, by valuation, the most valuable private technology company in Europe and the most valuable neobank on earth.
It is also a company whose entire investment case now rests on things it has not done yet. The full UK banking licence only arrived in March 2026, after a wait of nearly four years. The US charter application was filed the same month and has not been granted. The lending book, the thing that separates a bank from an app, is a rounding error against the deposits sitting on the platform.
So this Revolut SWOT analysis is less about whether the company is good. That question is answered. It is about whether the gap between what Revolut is and what investors are pricing it to become can actually be closed. For the mechanics of how the money moves, our teardown of the Revolut business model covers the plumbing in detail. What follows is the strategic position.
Revolut at a Glance
| Metric | FY2025 | FY2024 | Change |
|---|---|---|---|
| Group revenue | £4.5B | £3.1B | +46% |
| Profit before tax | £1.7B | £1.1B | +57% |
| PBT margin | 38% | 35% | +3 pts |
| Net profit | £1.3B | £0.8B | +63% |
| Retail customers | 68.3M | 52.5M | +30% |
| Business customers | 767K | 577K | +33% |
| Customer balances | £50.2B | £30.2B | +66% |
| Lending portfolio | £2.2B | £1.0B | +120% |
| Valuation (secondary) | $75B (Nov 2025) | $45B (2024) | +67% |
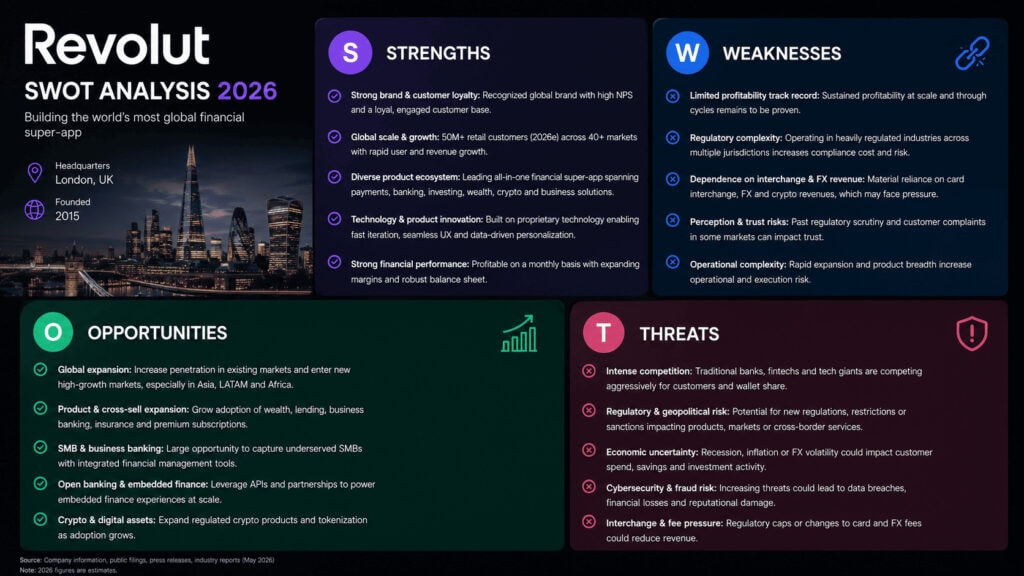
Revolut SWOT Analysis Summary

If you want a refresher on how the four quadrants are meant to interact, our guide to SWOT analysis explains the framework itself.
Revolut’s Strengths
A revenue mix that does not depend on any one thing
The single most important fact about Revolut in 2025 is not the profit number. It is the shape of the revenue.

Fee-based revenue accounted for 76% of turnover in 2025, up 4.2 percentage points on the year. Most retail banks run the exact opposite structure, with interest income supplying 70% or more of the top line. That inversion matters because it means Revolut’s earnings are far less hostage to the rate cycle than a conventional lender’s, and because eleven separate product lines now clear £100 million in annual revenue each. When a bank’s income depends on the base rate, its strategy is really the central bank’s strategy. Revolut has largely escaped that.
Subscriptions are the quiet standout: £708 million, growing 67%, faster than anything else in the mix. Paid-plan adoption rose 42%. This is recurring, high-margin, non-cyclical revenue of a kind that almost no bank on earth has managed to build, and it exists because Revolut sells a product people choose to pay for rather than a service they tolerate.
Profitability at genuine scale
Five consecutive profitable years, a 38% pre-tax margin, and 46% revenue growth in the same period is a combination that should not really happen. Growth companies buy growth with margin. Revolut expanded both at once, in a year when it also increased hiring and marketing spend.
For context, roughly three-quarters of neobanks worldwide still lose money. Most of them cannot get past the structural problem that a free current account used as a secondary spending card generates almost no revenue. Revolut broke that trap by stacking products on top of the account until the account stopped being the product.
The deposit flywheel finally turning
Customer balances jumped 66% to £50.2 billion. Savings balances more than doubled to £20.4 billion. This is the metric that tells you whether people treat an app as their bank or as their holiday wallet, and the answer, in Europe at least, has shifted. Revolut’s own CFO says one in five working-age adults in Europe now uses the app, and that in Spain, France and Italy close to one in three newly opened bank accounts is a Revolut account.
Regulatory footprint as a moat
Revolut now operates as a licensed bank in more than 30 of its 40 markets, including the UK and Mexico, with the Lithuanian entity Revolut Bank UAB anchoring EU operations under ECB supervision. Licences are slow, expensive and boring, which is exactly why they are defensible. A competitor can copy the app in a quarter. It cannot copy four years of PRA scrutiny.
Revolut’s Weaknesses
The fraud problem it has not outrun
Revolut has been the most-named firm in escalated UK fraud complaints for three years running. Data obtained by Which? through a freedom of information request to the Financial Ombudsman Service showed 3,242 authorised push payment fraud complaints referred against Revolut in 2024, ahead of Monzo at 2,344 and Barclays at 1,704. The 2025 data told a similar story.
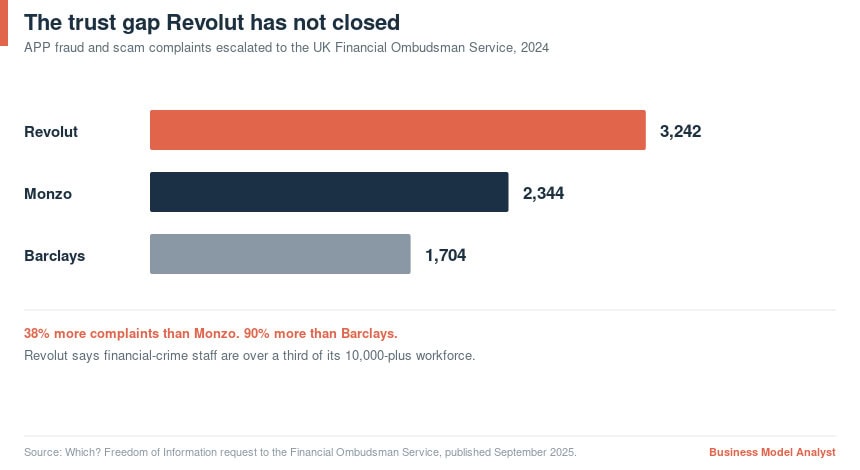
Revolut’s defence is that its financial-crime team now makes up more than a third of a workforce exceeding 10,000, that it analyses over a billion transactions a month, and that it prevented more than £600 million of attempted fraud in 2024. All of that can be true and the reputational damage can still compound. A BBC Panorama investigation found 9,793 fraud reports naming Revolut filed with Action Fraud in a single year, roughly 2,000 more than Barclays and Lloyds.
Here is why this is a strategic weakness rather than a PR one. Revolut has just been handed a UK banking licence and is about to ask British consumers to hold their salaries, mortgages and pensions there. Trust is the entire product in that transition. A company that scales its fraud complaints in line with its user growth will find the regulator’s patience finite, and the FCA and PRA have already demonstrated they are willing to make Revolut wait.
Monetisation per customer is mediocre
Divide FY2025 revenue by the retail base and Revolut earns roughly $88 per customer per year. That is a respectable figure against the industry average of about $45. It is a poor one against Nubank’s $124, achieved on a base almost twice as large.
The reason is structural. A large share of Revolut’s users, particularly outside its core European markets, still treat the app as a travel and FX tool rather than a primary account. The average is dragged down by a long tail of low-engagement users who signed up for cheap currency exchange and never came back. Growth to 100 million customers, the stated target for mid-2027, will make the headline number bigger and the average number worse unless product depth improves faster than the user count.
A bank with almost no loans
Revolut holds £50.2 billion of customer balances and lends £2.2 billion. That is a loan-to-deposit ratio of about 4%. A typical high-street bank runs somewhere between 70% and 100%.
The company frames its balance sheet conservatism as prudence, and with 90% of assets sitting in cash and treasury investments, it is genuinely low-risk. But a bank that does not lend is a very expensive money-market fund. The entire economic case for the UK licence is the ability to write credit cards, overdrafts and personal loans against that deposit base. Until it does, Revolut is leaving the most profitable product in banking on the table, and it will have to learn underwriting at speed, in a credit cycle it has never been tested in. The lending book grew 120% in 2025. It needs to grow like that for years, without the credit losses that usually follow.
Key-person and governance concentration
Nik Storonsky’s stake would be worth roughly $80 billion at a $200 billion listing. Founder control of that magnitude is a strength when the founder is right and an unpriced risk when he is not. Revolut’s internal culture has drawn repeated scrutiny, and its regulatory delays in the UK were tied explicitly to concerns about risk controls rather than to business performance.
Revolut’s Opportunities
The United States
In March 2026 Revolut filed with the Office of the Comptroller of the Currency and the FDIC for a national bank charter, to operate as Revolut Bank US, N.A., and appointed Cetin Duransoy, previously US chief executive of Raisin, to lead the market. This is the single largest opportunity on the board and the single largest execution risk.
A charter would let Revolut operate across all 50 states under one federal framework, own the customer relationship end to end rather than renting it from a partner bank, and fund lending with its own deposits. It would also drop Revolut into the most competitive consumer banking market on earth against Chime, SoFi, JPMorgan’s digital stack and a wall of regional incumbents. Its multi-product app is genuinely differentiated in a market where most neobanks sell one thing. Nobody in the US is asking for another checking account.
The UK bank it was never allowed to be
Cleared to launch its UK bank on 11 March 2026 after nearly four years in the licensing queue, Revolut is now migrating its UK customer base into the banking entity and plans to offer credit cards, unsecured personal loans and overdrafts. Nine million-plus UK customers, previously served as an e-money institution with no deposit protection, become eligible for the full product set.
The revenue arithmetic is simple. Lending against existing deposits is the highest-margin thing Revolut can do with a customer it already has. The company has also committed roughly $4 billion of a $13 billion five-year investment plan to the UK.
Geographic runway
| Market | Status | Strategic weight |
|---|---|---|
| Mexico | Banking operations launched January 2026 | LatAm beachhead against Nubank |
| India | Payments licence secured | Largest untapped user pool |
| UAE | In-principle payments licence | Wealth and remittance corridor |
| Argentina | Entered via acquisition of Banco Cetelem | Regional expansion |
| Peru | Banking licence application filed | Regional expansion |
| United States | Charter application filed March 2026 | Highest revenue per customer globally |
The stated goal is 30 new markets by 2030 and 100 million customers by mid-2027.
Product depth as the real growth lever
Zero-commission ETF plans across the EEA and Switzerland, CFD trading in 29 countries, mortgage refinancing launched in Lithuania, and Revolut Mobile, a genuine mobile network service in the UK and Poland. The mortgage move matters most. It is the stickiest product in retail finance and the one that converts an app into a primary banking relationship for a decade.
Revolut’s Threats
Nubank is bigger, richer and better at monetising

Nubank closed 2025 with 131 million customers, $16.3 billion of revenue and $2.9 billion of net income at a 33% return on equity. It generates more revenue than Revolut and Chime combined. It has also said 2026 is the year it starts building the capabilities to become a global digital banking platform, which is a polite way of saying it intends to leave Latin America.
The comparison that should worry Revolut shareholders is not the customer count. It is that Nubank got to superior unit economics by owning credit in its home market from day one, while Revolut spent the same decade optimising a fee stack and waiting for licences.
The rate cycle
Interest income was £974 million, 22% of revenue. It grew 23% in 2025, slower than every other stream. If policy rates fall, that line compresses, and it compresses fastest in exactly the markets where Revolut holds the most deposits. The company’s fee-heavy mix cushions this better than most banks manage, but it does not eliminate it.
Regulation catching up with the model
Mandatory APP fraud reimbursement in the UK arrived in October 2024 and shifted the cost of scams onto payment firms. For the firm with the most fraud complaints in the country, that is a direct earnings line, not a compliance footnote. Add the EU’s tightening consumer-protection agenda, a pending US charter that gives American regulators leverage, and a UK regulator with a demonstrated willingness to say no, and the regulatory environment is a persistent tax on the growth plan.
The valuation itself
A November 2025 secondary sale priced Revolut at $75 billion. Reports since have pointed to a further secondary in the second half of 2026 at more than $100 billion, and an eventual IPO discussed in the $150 billion to $200 billion range, though the company has said publicly that a listing is not imminent and that it has set no formal target. Our roundup of the highest-valued unicorns puts that in context against the rest of the private market.
At $75 billion, Revolut trades at roughly 12.5 times FY2025 revenue. At $200 billion it would trade at over 33 times, in a sector where public comparables re-rate violently. That expectation is a threat in its own right, because it forces management to keep compounding at 40% or more while simultaneously learning to underwrite credit, close a fraud problem, and enter the US. Any one of those alone would occupy a normal bank’s entire strategy.
Frequently Asked Questions
How much money does Revolut make? Revolut reported group revenue of £4.5 billion (about $6.0 billion) and profit before tax of £1.7 billion (about $2.3 billion) for the year ended 31 December 2025. Net profit was £1.3 billion, its fifth consecutive profitable year.
How many customers does Revolut have? Revolut closed 2025 with 68.3 million retail customers and 767,000 business customers. The company reported crossing 70 million retail customers in early 2026 and is targeting 100 million by mid-2027.
Is Revolut a real bank? Yes, in most of its markets. Revolut operates as a licensed bank in more than 30 of its 40 markets, including the UK, where it was cleared to launch its bank in March 2026, and the EU, through Revolut Bank UAB in Lithuania. It is not yet a chartered bank in the United States, where its application is pending with the OCC and FDIC.
What is Revolut’s biggest weakness? Two compete for the title. It earns less revenue per customer than Nubank despite similar product breadth, and it has been the most-named UK firm in escalated fraud complaints for three consecutive years, which is a serious liability for a company asking consumers to treat it as their primary bank.
Who is Revolut’s biggest competitor? Globally, Nubank, which serves 131 million customers and generated $16.3 billion of revenue in 2025. In the UK, Monzo and the high-street incumbents. In the United States, Chime, SoFi and the digital arms of the large national banks.
What is Revolut worth? A secondary share sale in November 2025 valued Revolut at $75 billion, up from $45 billion in 2024. Reports have indicated a further secondary sale in 2026 could value it above $100 billion.
The Business Model Analyst Take
The bull case writes itself, and that is precisely the problem. Revolut has the growth, the margin, the diversification and now the licences. Every box a sceptic could have ticked in 2022 has been ticked.
But look closely at what actually changed in 2025 and what did not. Revenue, profit and customers all moved sharply. Revenue per customer barely moved. The lending book, the one thing that turns a fee business into a bank, sits at 4% of deposits. The fraud complaints did not fall. In other words, Revolut got much bigger without meaningfully getting deeper, and the strategy from here depends entirely on depth.
That is the tension worth holding. A $75 billion valuation on $6 billion of revenue is defensible for a company compounding at 46%. A $200 billion valuation is a bet that Revolut becomes something it currently is not: a bank that lends, in the United States, at scale, without the credit losses and consumer-protection failures that have humbled every fintech that tried it before. Nubank did that. It took a decade and a home market where the incumbents were genuinely terrible. Revolut is attempting it in the two most competitive, most regulated banking markets in the world, simultaneously, while explaining to the FCA why its customers keep getting scammed.
The company that emerges from the next three years will either be the first genuinely global consumer bank or a very profitable, very good app that ran out of upside somewhere around 100 million users. The 2025 report does not tell you which. The 2027 lending book will.