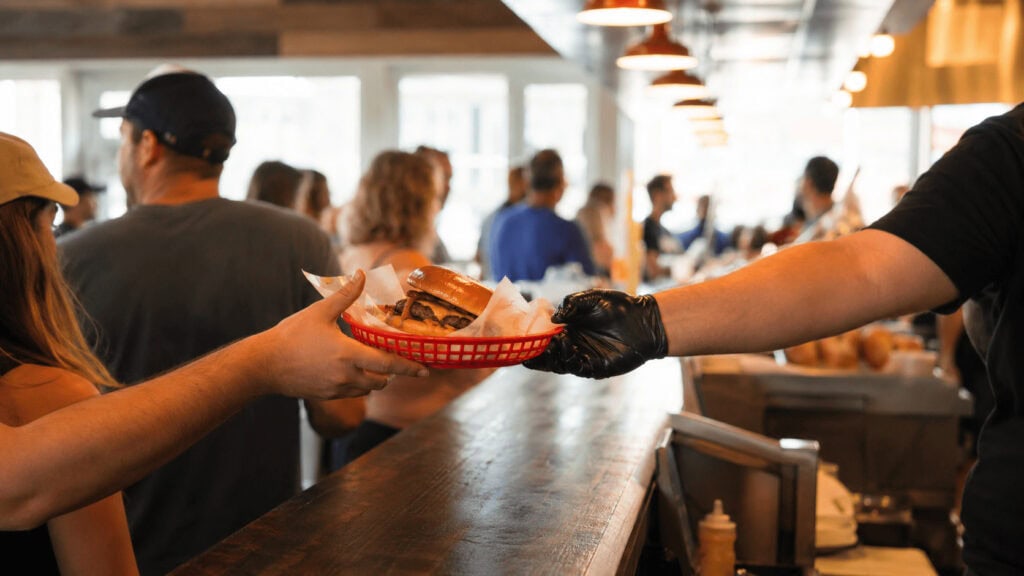

The $113 billion burger sector grew just 1.5% last year. The chains pulling it forward are the ones most Americans cannot even find in their state.
Regional burger chains like In-N-Out, Whataburger and Culver’s are driving most of the growth in America’s hamburger category, even as the broader sector crawls. The reason is not price. It is quality, service and disciplined expansion. In-N-Out’s domestic sales rose roughly 10% last year alone.
Picture this: a Saturday morning in a parking lot somewhere in the Southeast. People are camped out in lawn chairs with coolers packed, waiting for a burger joint to cut the ribbon on its newest location. No giveaway, no celebrity guest, no $5 deal. Just a chain that refuses to be everywhere at once, and a crowd that drove an hour to prove the point.
What Happened
Move over, Big Macs and Whoppers. The chains stealing the category’s momentum are the regional ones.
According to industry data reported by The Wall Street Journal, In-N-Out’s domestic sales grew by around 10% last year, second only to Shake Shack among U.S. burger chains. Culver’s and Whataburger now rank as the fifth and sixth largest U.S. burger chains by sales, according to market-research firm Technomic.
Here is the part that stings for the giants: these regional players are doing it while competing against heavyweights with thousands more locations and far bigger marketing budgets. As Culver’s CEO Julie Fussner put it, “The differentiator is the service. It’s the breadth of the menu and the quality of our food.”
The Backstory
The backdrop is a category in a rough patch. Burgers remain the biggest segment of the U.S. restaurant industry, but the $113 billion hamburger sector grew just 1.5% last year, the slowest growth of any of the 10 restaurant categories Technomic tracks, other than pizza and sandwiches.
Fast food usually thrives when wallets tighten. This time, diners worn down by years of menu price hikes stayed away. Chains answered with a flood of $5 meal deals to win them back.
The regional winners come from a different lineage. Whataburger started in 1950, when Harmon Dobson opened a stand in Corpus Christi, Texas, with one goal: make a burger big enough to need two hands and good enough to make you say “what a burger.” In-N-Out took the opposite of a land-grab approach, deliberately slowing its growth back in 2010 when current president Lynsi Snyder took the helm.
The Core Development
The regional playbook is the inverse of the national one. Instead of discounting harder, these brands are leaning on craveability and consistency.
Whataburger now generates more than $4 billion in annual U.S. sales across 17 states, and it is growing at roughly six times the rate it averaged before 2019, on track to open about 60 restaurants this year. CEO Debbie Stroud credits a “cultlike following” built on quality and customization, where regulars know they can add grilled jalapeños or swap onions for fresh tomatoes.
Culver’s, with 1,066 locations across 26 states, says traffic is up 5% this year. Notably, Fussner said the chain used to lean on discounts but found they lost their punch as customers got conditioned to expect them. So Culver’s competes on its ButterBurgers, sizes and service instead.
The giants have noticed. Burger King overhauled its signature Whopper this year and started taking phone calls from diners about its food. McDonald’s, which upgraded its burgers in 2023, pledged this month to cook fresh beef in more markets and make stores more inviting with kiosks and play spaces.
The Business Model Angle
Strip away the ButterBurgers and this is a clinic in how to win a mature market without a price war.
The pattern is differentiation over discounting. In a commoditized category, the obvious move is to compete on price, and that is exactly the trap. Discounts train customers to wait for the next deal, which is precisely why Culver’s walked away from them. The “better burger” players chose a harder, stickier moat: be the burger people actively crave, not the one they settle for because it was cheap.
The second lesson is that scarcity can be strategy. In-N-Out added only four states to its footprint in the last decade, and fans literally camp out for new openings. That restraint is not timidity. It is brand equity. “An overemphasis on growth would compromise our performance,” said COO Denny Warnick. Compare that to the McDonald’s business model, where roughly 40,000 franchised locations deliver scale and consistency but make premium craveability much harder to manufacture. Neither model is wrong. They are just optimized for different things.
For founders, the takeaway is sharp: in a saturated market, you rarely win by being the cheapest or the biggest. You win by being the one people will drive past three competitors to reach.
The Risk
Now the honest counterpoint, because the “small beats big” narrative is seductive and partly a trick of the light.
Much of what makes these chains special is that they are regional. Scarcity, novelty and local loyalty are doing real work here. The moment In-N-Out blankets the country, the parking-lot campouts stop being remarkable. The very discipline that protects the brand also caps the upside, and slow growth leaves wide-open white space for the giants to defend.
And the giants are no longer asleep. Burger King and McDonald’s are both upgrading food and service right now, with marketing budgets and location counts the regionals cannot match. There is also the macro question: retired exec Steve Hanshaw says he would “much rather pay $15 for a good burger than to get a great deal,” but in a genuinely tight economy, how many diners share that math? Most of these chains are also privately held and family-led, which keeps them disciplined but limits the capital and succession runway for aggressive moves.
Winning the growth race in a stalling sector is impressive. Sustaining it as the giants wake up and trade up is the real test.
Quick Questions
Why are regional burger chains growing faster than McDonald’s and Burger King?
They compete on quality, service and customization instead of price, which has kept their most loyal customers coming back without heavy discounting. In-N-Out grew around 10% last year, while the overall sector grew just 1.5%.
Is In-N-Out planning to go national?
Not aggressively. The family-owned chain has added only four states in the last decade and deliberately slowed growth in 2010 to protect food quality, service and management standards.
Why don’t chains like Culver’s just discount more?
They tried. Culver’s says discounts became less effective once customers were conditioned to expect them, so the chain shifted to competing on its ButterBurgers, menu breadth and service. Traffic is up 5% this year.
Are the big chains doing anything about it?
Yes. Burger King overhauled its Whopper this year and McDonald’s pledged to cook fresh beef in more markets, improve service and bring back play spaces.
The Bottom Line
The burger wars just proved an old lesson in a new wrapper: in a crowded, low-growth market, price is a race to the bottom and craveability is the only durable moat. The regional chains winning right now are not the cheapest or the most convenient. They are the ones customers genuinely want, served by brands disciplined enough to grow slowly and protect what makes them special. For any founder in a commoditized category, that is the whole playbook: earn the line out the door, then resist the urge to ruin it by being everywhere at once.