
Reddit is the most valuable text archive on the consumer internet and the only company that cannot get at it. In the quarter ended June 30, 2026, Reddit reported $805 million of revenue, up 61%, with a 91.3% gross margin and $253 million of net income. In the same release, it reported 23.1 million logged-in daily users in the United States, up 1%.
Both numbers are true, and they point in opposite directions. Sorting out which one describes the business is what this SWOT analysis is for.
What is a SWOT analysis? A SWOT analysis sorts a company into four buckets. Strengths and weaknesses are internal, things the company controls. Opportunities and threats are external, things the company can only respond to. The point is not the list. The point is finding where a strength and a weakness turn out to be the same asset viewed from two sides, because that is where strategy actually gets made. For the framework itself, see our guide to SWOT analysis and our SWOT analysis examples.
The thesis: four quadrants, one question
Reddit holds 26 billion posts and comments, built by unpaid contributors and policed by unpaid moderators. That archive is the asset. Every quadrant below resolves to a single question about it: who gets to read it.
Google and OpenAI read all of it under license. Perplexity and Anthropic read it too, which is why Reddit is suing them. Google’s AI Overviews cite Reddit in roughly 21% of answers, and Perplexity in something close to half. Reddit’s own home feed, meanwhile, can only draw from about one week of posts at a time.
The archive is the strength. The inability to surface it is the weakness. Selling access to it is the opportunity. Losing control of who reads it is the threat. Here is the company those four things produce.
Reddit at a glance, Q2 2026
| Metric | Q2 2026 | Q2 2025 | Change |
|---|---|---|---|
| Revenue | $805M | $500M | +61% |
| Advertising revenue | $762M | $464M | +64% |
| Other revenue (incl. licensing) | $43M | $35M | +24% |
| Net income | $253M | $89M | +183% |
| Gross margin | 91.3% | 90.8% | +50 bps |
| Daily active uniques | 130.3M | 110.4M | +18% |
| Weekly active uniques | 514.6M | 416.4M | +24% |
| Global ARPU | $6.18 | $4.53 | +36% |
| U.S. ARPU | $11.85 | $7.87 | +51% |
| Capital expenditure | $1.1M | $0.5M | +125% |
That capex line is not a typo. Reddit spent $1.1 million on property and equipment in a quarter where it collected $805 million. Its entire net PP&E balance stood at $12.0 million against $3.64 billion of total assets. For context on how a business model like this one is put together, our Reddit business model breakdown covers the mechanics.
Strengths
1. Reddit raises prices and advertisers pay
The Q2 2026 advertising number came from pricing, not volume. Reddit told investors that ad revenue growth was driven by pricing of roughly 40% against a 17% increase in impressions. Global ARPU rose 36%. U.S. ARPU rose 51%, to $11.85 from $7.87.
Active advertisers grew more than 70% year over year, conversion volume more than doubled, and 11 of 15 industry verticals grew over 50%. Third-party work from Attain and Circana put Reddit at 1.5x the return on ad spend of the average social platform for consumer packaged goods advertisers across the U.S. and Western Europe. TransUnion ranked Reddit the most efficient paid social channel in EMEA for retail.
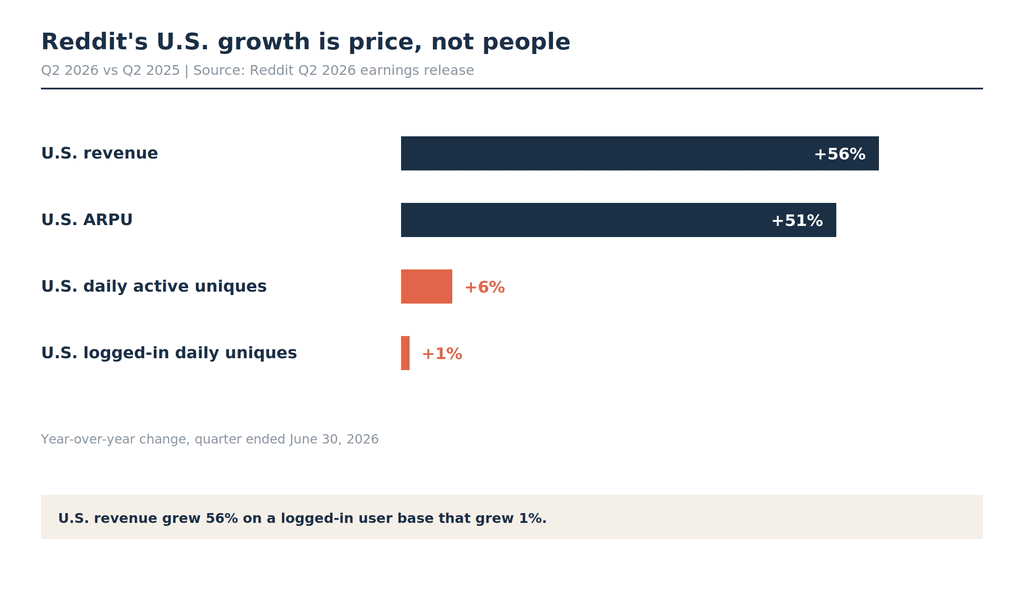
The same chart is a weakness, which is the interesting part. Hold that thought.
2. The supply side costs nothing
Reddit’s 91.3% gross margin exists because the two most expensive things about a media business, content and moderation, are donated. Users write the 26 billion posts. Volunteer moderators enforce the rules across roughly 138,000 actively maintained subreddits out of 2.8 million that exist. Reddit pays for neither.
Cost of revenue in Q2 was $70 million on $805 million of sales. Operating cash flow crossed $1 billion on a trailing twelve-month basis for the first time. Management also announced it had passed $1 million of revenue per employee, which against $2.78 billion of trailing revenue implies headcount somewhere near 2,800 people. Meta runs about 76,000.
3. The corpus is still mostly human
Pangram’s July 2026 scan of 1,002,627 posts across five platforms found Reddit at 4.4% AI-generated overall, with replies at 98.1% human. LinkedIn came in at 41% of long-form content fully AI-generated. In a market where synthetic text is now the default, Reddit’s archive is the cleanest large sample of people talking to each other, and Huffman has built the entire investor pitch on it. Semrush ranks Reddit the second most search-visible domain in the United States behind Wikipedia. One Search Engine Land study found Reddit appearing in 97.5% of Google product-review results.
4. A balance sheet with no obligations attached
Reddit closed the quarter with $2.79 billion in cash and marketable securities, no debt, and $760 million remaining on a $1 billion buyback authorization after retiring 1.5 million shares at an average of $157.57. It has an $880 million multi-year AWS commitment running to June 2029, and beyond that almost nothing that requires capital.
Weaknesses
1. The contributor base in the U.S. stopped growing
Reddit’s U.S. logged-in daily active uniques went from 22.9 million to 23.1 million. That is 200,000 people over twelve months, on a base management wants to take to 100 million.
Logged-in users are the ones who post, vote, comment, and moderate. They are also the ones advertisers are paying $11.85 a head to reach. Everything Reddit sells depends on that cohort growing, and in the U.S. it added 0.9%.
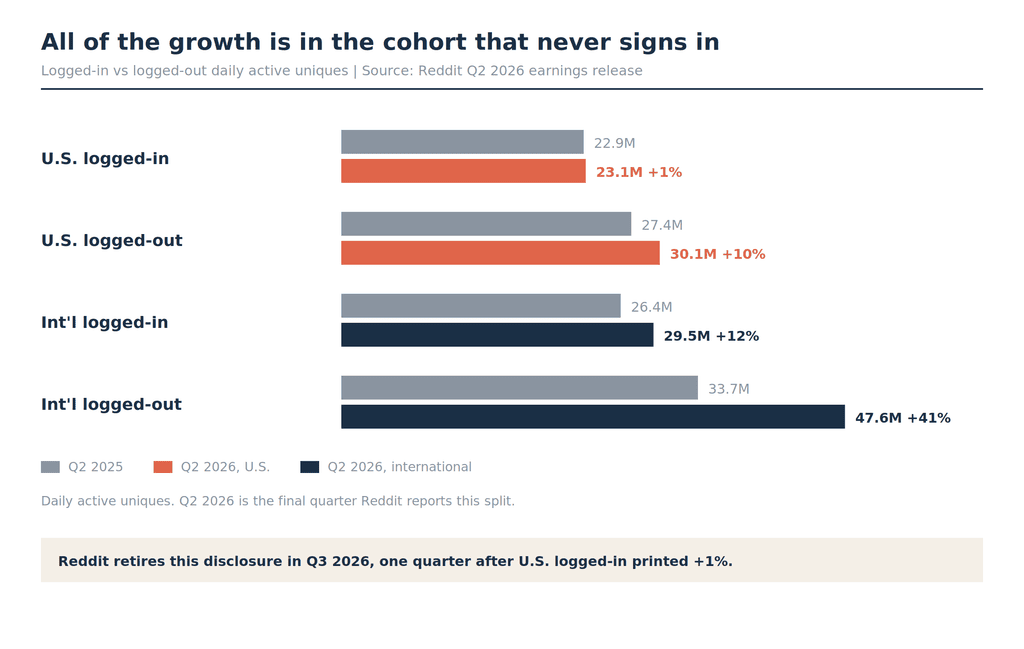
Global logged-out daily uniques grew 27%, to 77.7 million. Logged-in grew 7%. International logged-out grew 41%, much of that machine-translated pages arriving from search. Huffman calls this cohort “drive-by traffic” and says the business does not live there. He is right about the economics and that is the problem, because the drive-by cohort is where the growth is.
Run the arithmetic on the stated targets. U.S. daily uniques at 53.2 million compounding at 6% reach 100 million in about eleven years. U.S. logged-in uniques at 23.1 million adding 200,000 a year do not reach it inside anyone’s planning horizon. Reddit’s other target, one billion global dailies, sits about twelve years out at the current 18% rate.
2. Reddit’s feed cannot see Reddit
On the Q2 call, Huffman described his own recommendation stack with unusual candor. The models are smaller than state of the art. They refresh in days rather than minutes. They ingest about 10% of user activity. And the candidate set, the pool of posts eligible to appear in the home feed, covers roughly one week.
Reddit added 1 billion posts and comments in the quarter, so a week is about 77 million items. Against a 26 billion item corpus, that is 0.3%.
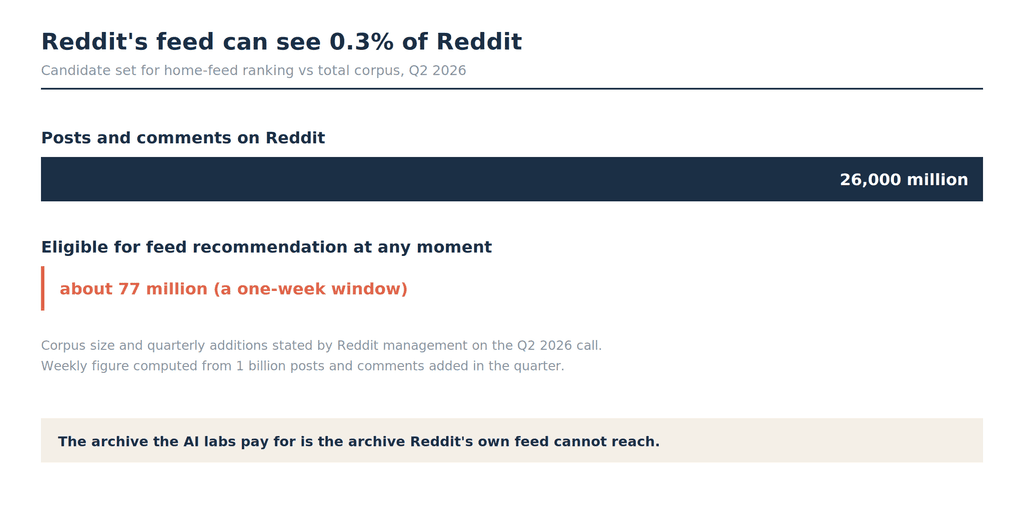
Huffman named the specific loss: parenting advice, book reviews, movie recommendations, content that stays useful for years and never appears in the feed. The archive that OpenAI pays to train on and that Google surfaces in AI Overviews is invisible to Reddit’s own product. Any user who wants the good stuff has to go through a search engine to get it, which is how Reddit ended up with a traffic dependency in the first place.
3. Reddit is buying demand rather than building product
Set the two expense lines side by side. Sales and marketing went from $120.6 million to $195.9 million, up 62%. Research and development went from $196.6 million to $231.3 million, up 18%.
The CEO says the feed is behind the state of the art and that fixing it is what gets Reddit to a billion users. The spending says the priority is selling the audience Reddit already has. CFO Drew Vollero conceded on the call that user acquisition spending “needs stronger attention to improve returns,” which is a polite way of saying the paid channel is not paying back.
4. The metric under pressure is the metric being retired
Beginning in Q3 2026, Reddit stops publishing the logged-in and logged-out split. Q2 2026 was the final disclosure, and it printed U.S. logged-in growth of 1%.
Reddit announced this on the Q4 2025 call, before the number went flat, and the stated reason is that the company runs the business against total audience. Both things can be true. The result is the same: the one number that separates Reddit’s contributors from its passers-by disappears from the filings in the quarter after it stalled.
5. Reddit’s own answer engine reaches 3% of its audience
Reddit Answers grew from 1 million weekly users in Q1 2025 to 15 million in Q4 2025. On-platform search reached 80 million weekly users, up from 60 million. Both are real growth. Both are small against 514.6 million weekly uniques. Reddit’s search product touches 15.5% of its weekly base and its AI answer product touches 2.9%.
Opportunities
1. Read its own archive
The fix for weakness two is the largest single opportunity Reddit has, and it requires no acquisition, no new audience, and no partner. Widening the candidate set from one week to the full corpus, scaling the models, and moving refresh from days to minutes turns 26 billion items of dormant inventory into feed supply. Huffman put it plainly: he expects every improvement to work because the starting point is so low.
Adjacent to that, Reddit is testing what Huffman calls spoken Reddit, background listening to posts, which competes with an existing cottage industry of YouTube channels that read Reddit threads aloud. That content type already has an audience. Reddit does not own any of it today.
2. The international ARPU gap
International daily uniques hit 77.1 million, up 28%, and now outnumber U.S. dailies. International ARPU is $2.26 against $11.85 in the U.S., a gap of 5.2x. International revenue grew 84% and international weekly uniques grew 35% to 317.4 million.
Closing even half the ARPU gap on the current international base would add roughly $370 million a quarter. The catch is that international growth is concentrated in logged-out, machine-translated traffic, which is the cohort with the weakest monetization and the loosest attachment.
3. Commerce and lower-funnel advertising
Shopping conversations on Reddit grew 40% year over year. Reddit made its Shopify integration generally available in May and had 500 accounts integrated by quarter end. Dynamic product ads and app installs each more than doubled. Reddit Max, the automated campaign suite, grew revenue more than 150% sequentially.
Search is where these meet. Reddit is piloting shopping listing ads, a multi-advertiser carousel matched to purchase conversations, and Jen Wong said the infrastructure is already built. An ad-supported search surface inside a platform people already visit to research purchases is the most valuable inventory Reddit has never sold.
4. Licensing beyond the two incumbents
Huffman described data licensing as an expanding marketplace with layers: training, post-training, grounding, search indexing. Reddit currently licenses to Google and OpenAI. Every model developer that wants an authentic conversational corpus is a candidate buyer, and Reddit’s litigation is an attempt to convert the unlicensed ones into licensed ones.
Threats
1. Reddit’s landlord is also its competitor and its customer
Google refers a large share of Reddit’s traffic, pays Reddit roughly $60 million a year for content, and builds the product that answers the user’s question so the click never happens. Huffman said it directly on the call: ten blue links drove tremendous value to the ecosystem, and AI Overviews “has yet to make a similar level of positive impact.”
Reddit is selling the raw material for the machine that reduces its distribution. Search referrals were choppy through Q2 and volatile late in the quarter, and Huffman said visibility into referral traffic remains low. The stock fell about 11% on results that beat on revenue, earnings, and guidance.
2. The AI data story is 5% of revenue and shrinking
Reddit’s popular framing as an AI data company does not survive contact with the income statement.
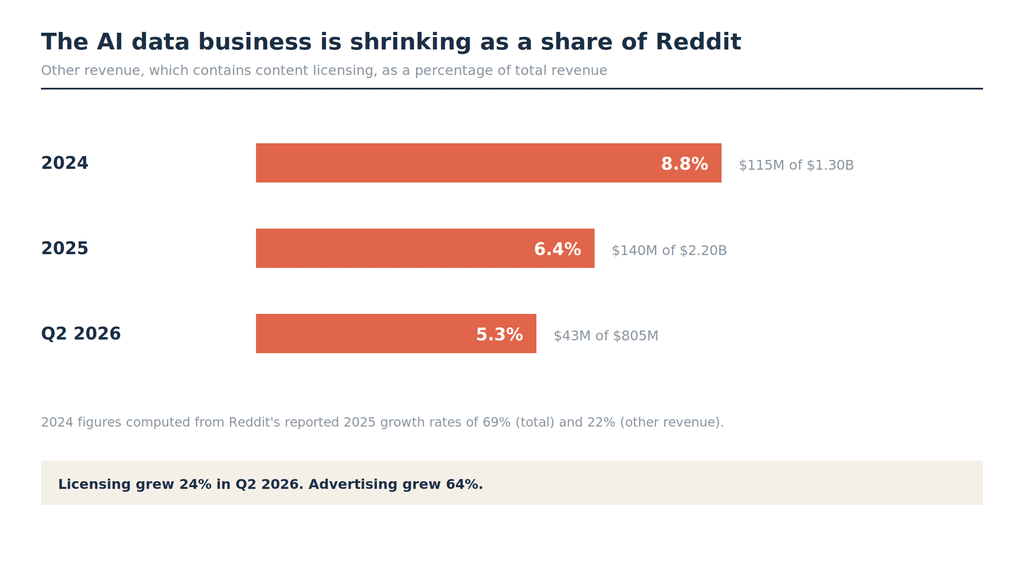
Other revenue, which houses content licensing, was $43 million in Q2 2026 against $762 million of advertising. It grew 24% while advertising grew 64%. As a share of total revenue it has fallen from about 8.8% in 2024 to 6.4% in 2025 to 5.3% last quarter.
That cuts two ways. Renewal risk on the Google and OpenAI agreements, which analysts on the call flagged as coming up in early Q1, threatens a line that is no longer material to revenue. It threatens something else instead: the price signal. If the licensing rate resets downward, the market has to reprice the archive itself, and the archive is the whole equity story.
3. Litigation as a business development strategy
Reddit sued Anthropic in June 2025 over API terms and sued Perplexity, SerpApi, Oxylabs, and AWMProxy in October 2025, alleging they harvested Reddit content out of Google’s search results to route around Reddit’s access controls. Perplexity called the suit a show of force in Reddit’s negotiations with Google and OpenAI, which is uncharitable and probably accurate.
Motions to dismiss from Perplexity and SerpApi went to argument on June 30, 2026 and remain pending before Judge Engelmayer. If the court declines to extend the DMCA’s anti-circumvention provision to downstream buyers of already-scraped data, Reddit’s leverage over unlicensed users of its corpus drops to whatever its user agreement can carry, and the licensing market it is trying to build stays voluntary.
4. Pseudonymity is a regulatory target
The UK’s Information Commissioner’s Office fined Reddit £14,472,500 on February 24, 2026 for processing the data of under-13s without a lawful basis and for failing to run a data protection impact assessment before January 2025. It is the third-largest fine in ICO history and Reddit is appealing.
Reddit’s public response named the tension: the ICO’s position requires Reddit to collect more personal information about every UK user, which cuts against the pseudonymity that makes the platform work. People post honest reviews of their employer, their medication, and their marriage on Reddit because nobody knows who they are. Age assurance regimes in the UK, the EU, and a growing list of U.S. states all push toward verified identity. The regulatory direction attacks the property that makes the archive worth licensing.
5. Synthetic contamination of the asset
Reddit’s pitch to advertisers is that it is the last large source of human text. Management flagged on the Q4 2025 call that distinguishing human from AI content is getting harder. Pangram’s 4.4% figure is low today. It is not a fixed number, and Reddit has no pricing mechanism to defend it, because the suppliers are volunteers who cannot be paid more for staying human.
The SWOT matrix
| Strengths | Weaknesses |
|---|---|
| Ad pricing up ~40%, U.S. ARPU up 51% | U.S. logged-in dailies up 1% to 23.1M |
| 91.3% gross margin on donated content and moderation | Feed candidate set covers 0.3% of the corpus |
| 26B posts, 4.4% AI-generated vs LinkedIn’s 41% | S&M spending up 62% while R&D grew 18% |
| $2.79B cash, no debt, $1.1M quarterly capex | Logged-in/logged-out split retired from Q3 2026 |
| Opportunities | Threats |
| Widen the feed window to the full 26B archive | Google is traffic source, licensee, and substitute |
| Int’l ARPU $2.26 vs U.S. $11.85 on 77.1M dailies | Licensing at 5.3% of revenue, growing 24% vs ads at 64% |
| Ads on search and Answers, shopping conversations +40% | Anti-circumvention rulings pending in the Perplexity case |
| Licensing layers beyond training data | Age assurance regimes vs pseudonymous posting |
What the four quadrants add up to
Reddit converts an archive it does not own into revenue it does keep, and the conversion runs through third parties. Google turns the archive into referrals. OpenAI turns it into training runs. Advertisers pay Reddit for the attention that arrives as a result.
Reddit’s own product converts less of that archive than anyone else does. That is why U.S. revenue can grow 56% while the U.S. contributor base grows 1%: the company has spent two years getting better at charging for an audience it already had, and has not yet built the product that grows one.
Vollero’s framing on the call is the cleanest statement of the whole position. Asked why Reddit does not spend more on user acquisition given a $11.85 U.S. ARPU and 95%-plus incremental gross margins, he said the unlock is retention, and that retention is lower than peers. Reddit knows it can buy users. It cannot yet keep them. The product work that would fix that is the same product work that would let the feed reach the archive, which is the same archive the AI labs are paying to read.
Everything routes back to the same file cabinet.
Frequently asked questions
Is Reddit profitable? Yes. Reddit posted $530 million of net income in 2025 after a $484 million loss in 2024, and $457 million in the first half of 2026 alone. Q2 2026 net margin was 31.4%.
How does Reddit make money? Advertising accounted for $762 million of $805 million in Q2 2026, about 95%. The remainder is content licensing to AI companies plus user subscriptions and awards. See our Reddit business model breakdown for the full structure.
What is Reddit’s biggest weakness? The U.S. logged-in user base. It grew 1% year over year in Q2 2026 to 23.1 million, against a stated target of 100 million U.S. daily users. Logged-in users produce the content and carry the advertising value.
How much does Reddit earn from AI data licensing? Reddit does not break it out, but “other revenue,” which contains licensing, was $140 million in 2025 and $43 million in Q2 2026. It has fallen from roughly 8.8% of revenue in 2024 to 5.3% last quarter.
Who are Reddit’s main competitors? For advertising dollars, Meta, TikTok, Pinterest, and Snap. For discovery, Google, plus ChatGPT and Perplexity, which answer the question Reddit used to receive as a click. For professional discussion, LinkedIn.
Why did Reddit stock fall after a quarter that beat expectations? Shares dropped about 11% after the July 30, 2026 report because management described search referrals as choppy and U.S. daily uniques slipped sequentially from 53.5 million to 53.2 million. Investors priced the user trajectory, not the earnings beat.
The Business Model Analyst Take
Most write-ups of Reddit ask whether the AI companies will keep paying for the data. That is the wrong worry. The licensing line is 5.3% of revenue and falling as a share. Losing it would cost Reddit less than one quarter of advertising growth.
The right worry is that Reddit has proved the archive is worth a great deal to everyone with a model to train and has not yet proved it is worth much to Reddit as a destination. Google monetizes it. OpenAI monetizes it. Perplexity monetizes it well enough to get sued over it. Reddit monetizes a one-week slice of it and sells ads against the traffic that other people’s products send back.
Fixing the feed is not a nice-to-have on the roadmap. It is the whole thesis. If Huffman’s team widens the candidate window and the retention curve bends, Reddit becomes a destination with pricing power and a twenty-year moat of content nobody can replicate. If it does not, Reddit stays what the Q2 numbers describe: an excellent advertising business attached to a stagnant American user base, renting its distribution from the company building its replacement.
Watch one number when Q3 lands in late October. Not revenue, which will beat. U.S. daily active uniques. The logged-in split will be gone by then, which tells you something in itself.