


What is the Red Bull business model? Red Bull GmbH sells one product family, a premium energy drink in a slim 250 ml can, and spends roughly a quarter of its turnover making that can culturally unavoidable. Almost all revenue comes from drink sales. The sports teams, events and media studio are marketing costs that pay back in attention, not profit. Red Bull outsources the filling of the can to partners, but keeps its own people between the pallet and the cooler in many markets. In 2025 that model sold 13.969 billion cans, booked €12.196 billion in turnover and earned €1.9 billion in net income, with no financial debt.
Most write-ups of Red Bull describe a marketing genius that happens to own some Formula 1 cars. That is half right. The part that gets skipped is the plumbing: who fills the cans, who drives the trucks, who stands in front of the retailer’s shelf, and who gets paid when the year is over. Those choices explain why Red Bull earns about the same profit as its closest rival while employing more than three times as many people, why the European Commission is investigating how it manages store shelves, and why a single US grocery chain was able to take it off the shelf in 2026.
This breakdown uses Red Bull’s own published figures, its annual accounts filed in Austria (released on September 23, 2026), and filings from its competitors.
Red Bull at a Glance (2025 Figures)
| Metric | Figure |
|---|---|
| Legal entity | Red Bull GmbH, Fuschl am See, Austria |
| Founded | 1984; first can sold in Austria on April 1, 1987 |
| Cans sold (2025) | 13.969 billion, up 10.2% |
| Group turnover (2025) | €12.196 billion, up 8.6% |
| Net income (2025) | €1.9 billion, up 12% |
| Employees (end of 2025) | 21,924 (19,973 a year earlier) |
| Countries | 178 |
| Marketing paid to athletes and teams (2025) | More than €1.5 billion, 48% of the marketing budget |
| Financial debt | None; growth financed from operating cash flow |
| Owners | Mark Mateschitz 49%; Yoovidhya family side 51% |
Three Things Most Red Bull Business Model Breakdowns Get Wrong
Before looking at how the money moves, it helps to clear out three claims that still circulate on older pages, including earlier versions of this one.
1. “Coca-Cola helps Red Bull outsource production.” It does not. Red Bull’s cans are filled by Rauch Fruchtsäfte, the Austrian family juice company that has bottled Red Bull since 1987, in plants that sit next to can factories run by Ball Corporation. Coca-Cola is on the other side of the fight: it owns 19.5% of Monster Beverage and its bottlers distribute Monster around the world.
2. “Dietrich Mateschitz technically owns the company.” Mateschitz died in October 2022. His 49% stake passed to his son, Mark Mateschitz. The Thai Yoovidhya family, heirs of co-founder Chaleo Yoovidhya, holds the other 51%. The original split was 49%, 49% and a 2% swing stake for Chaleo’s son Chalerm; that 2% was transferred to a trustee, Fides Trustees, in 2025, according to Bloomberg.
3. “Red Bull uses its sports teams to diversify its earnings.” The teams are not a second income stream. Red Bull Racing, the Formula 1 team in Milton Keynes, reported £1.68 million of profit on £314.4 million of turnover for 2024, which is a margin of about half a percent. The clubs, teams and events sit on the cost side of the model. They are how Red Bull buys attention, and the income they generate mostly offsets part of what they cost.
How Red Bull Makes Money
Red Bull makes money the simplest way a beverage company can: it sells cans. Revenue from licensing content, running events or selling merchandise exists, but the company does not break it out, and nothing in its reporting suggests it is material next to drink sales.
What makes Red Bull interesting is not the number of revenue streams. It is how much turnover each can brings in, and how that figure has behaved while volume nearly doubled.
| Year | Cans sold | Group turnover | Turnover per can |
|---|---|---|---|
| 2019 | 7.5 billion | €6.067 billion | €0.809 |
| 2020 | 7.9 billion | €6.307 billion | €0.798 |
| 2021 | 9.8 billion | €7.816 billion | €0.797 |
| 2022 | 11.582 billion | €9.684 billion | €0.836 |
| 2023 | 12.138 billion | €10.554 billion | €0.870 |
| 2024 | 12.7 billion | €11.227 billion | €0.886 |
| 2025 | 13.969 billion | €12.196 billion | €0.873 |
Turnover per can is BMA’s calculation from Red Bull’s published can and turnover figures. Group turnover includes non-drink revenue, so the ratio slightly overstates drink revenue per can.
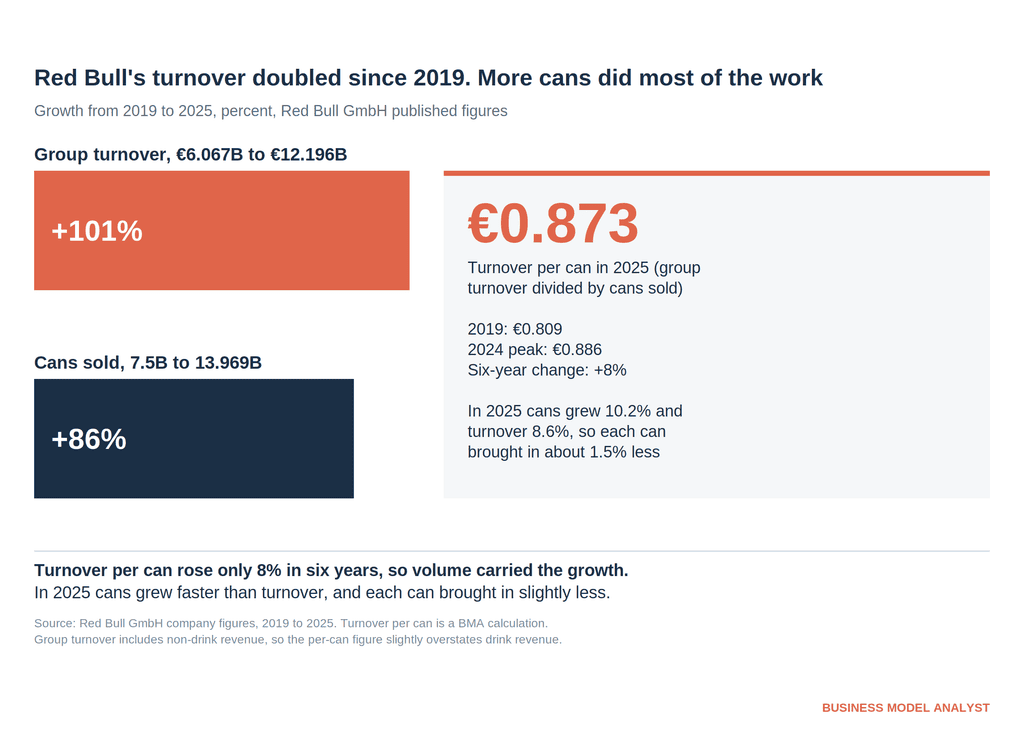
Between 2019 and 2025, turnover grew about 101% while cans grew about 86%. Turnover per can rose only 8% across those six years, from €0.809 to €0.873. In other words, Red Bull’s growth has come overwhelmingly from selling more cans, not from charging much more for each one.
2025 is the exception worth noticing. Cans grew 10.2% but turnover grew only 8.6%, so turnover per can slipped about 1.5% after five years of gains. Red Bull does not explain the gap, but two forces fit it. The first is currency: Red Bull reports in euros and the United States is its most important market, so a dollar that weakened against the euro through 2025 turns the same American sales into fewer euros. The second is mix: growth in markets such as India and Brazil adds cans at lower local prices. Either way, the 2025 accounts show the company did not try to close that gap by cutting marketing, which rose sharply instead.
That per-can figure also explains the flashpoint of September 2026. Kroger, which runs more than 2,700 US stores under banners such as Ralphs and Fred Meyer, removed Red Bull from all of its stores and fuel centers after rejecting a wholesale price increase, according to Bloomberg. Kroger kept selling Monster, Alani Nu, Rockstar and NOS. For a company whose growth has been volume-led, a price increase is a rare lever, and the Kroger standoff is the first public test of how far that lever goes with a large US retailer.
Red Bull Outsources the Can, Not the Cooler
The most repeated line about Red Bull is that it is “asset-light.” That is true for exactly one step of the chain.
Manufacturing is outsourced. Rauch fills the cans. Ball makes them. Red Bull owns neither the filling lines nor the can plants. The company’s newest US project shows how the split works in practice: the integrated campus in Concord, North Carolina, which broke ground in September 2025 and is expected to fill up to 3 billion cans a year by 2031, was built on commitments of about $424 million from Red Bull, $680 million from Rauch and $383.8 million from Ball, according to Cabarrus County incentive filings reported by trade press. Red Bull’s share, roughly 28% of the total, pays for the fully automated warehousing and distribution center on the site. Rauch pays for the filling. Ball pays for the cans.
Distribution is not outsourced, at least not fully. In the US, Red Bull built its own wholesaler, the Red Bull Distribution Company (RBDC), in 2009. It describes itself as the largest distributor of Red Bull products in the country and lists about 4,800 employees in North America, with the rest of the country covered by independent distributors. RBDC employs the sales reps, merchandisers and drivers who stock coolers and negotiate shelf space. That is the part of the chain where the brand’s premium is defended every day: a retailer that discounts, misplaces or runs out of the product is the fastest way to erode a price position.
This is the real design choice in the Red Bull business model, and it becomes obvious next to Monster.

Dollar conversions use the rate Bloomberg applied when Red Bull reported its 2025 turnover, about $1.17 per euro. Net margin and headcount comparisons do not depend on the exchange rate.
Monster outsources both the can and the cooler. It sells to Coca-Cola bottlers and lets their trucks and sales forces do the store work, which is why it can run an $8.29 billion business with 6,891 people. Red Bull’s revenue is larger partly because, in markets where it distributes itself, it sells closer to the retailer and keeps the wholesale step inside its own accounts, but it also carries the people and costs of doing that job. The result: about 1.7 times Monster’s revenue, 3.2 times Monster’s headcount, and a comparable bottom line.
Neither model is wrong. Monster traded control for margin. Red Bull traded margin for control, and control is what a premium-priced, single-product brand needs most.
Where the Money Goes: Marketing Is the Business
Red Bull’s annual accounts for 2025 put a number on what used to be an estimate. Payments to athletes and teams passed €1.5 billion for the first time and made up 48% of the marketing budget. Sponsorship costs rose 22% in the year. The rest of the marketing line covers advertising and promotion, including customer and retailer promotions, according to reporting on the filing by Bloomberg and City AM.

Working backwards from those two figures, the full marketing budget comes to roughly €3.1 billion, about a quarter of turnover. That is about 1.6 times what Red Bull kept as net income. For comparison, Monster’s entire operating expense line, which includes distribution, selling, marketing and administration together, was 26.7% of its 2025 net sales.
Three things follow from that structure.
Marketing is Red Bull’s largest controllable cost. Can prices, aluminum and freight move with the market. The marketing budget is set by the owners. When Red Bull chose to lift sponsorship spending 22% in a year when turnover grew 8.6%, it was deciding how much of its margin to reinvest in the brand, and net income still rose 12%.
About half of the budget does not go to athletes at all. The part of marketing that gets written about is the Stratos jump and the F1 cars. The part that gets less attention is the roughly half spent on advertising, consumer promotion and retailer promotion, which is money that flows to the store side of the business. That second half is where the model meets competition law.
The sponsorship portfolio keeps changing. In 2025 Red Bull added a rugby union club in Newcastle, now the Newcastle Red Bulls, and sold part of its stake in the Alinghi sailing team. It holds a 10.6% stake in Paris FC. The football portfolio includes RB Leipzig, FC Red Bull Salzburg, the New York Red Bulls, Red Bull Bragantino in Brazil and RB Omiya Ardija in Japan. Its two Formula 1 teams, Red Bull Racing and Racing Bulls, have run on Red Bull Ford engines, built in-house by the company’s Red Bull Powertrains division, since the 2026 season.
For the full story of how the athlete and content engine works, see our Red Bull marketing strategy breakdown.
Red Bull Media House: A Studio on the Cost Side
Red Bull Media House, founded in 2007, produces films, series, live broadcasts, magazines such as The Red Bulletin, music through Red Bull Records, and the Austrian television channel ServusTV. It licenses content to outside broadcasters and platforms, which means part of the marketing department earns fees rather than only spending them.
It is still best read as a marketing asset. Red Bull does not disclose Media House revenue or profit, and the value of a live event built around an athlete comes from the attention it drives back to the can. The practical advantage is ownership: a 30-second advertisement is gone when the slot ends, while a documentary, a clip library or a recurring event keeps producing views for years and can be resold.
Who Owns Red Bull and Where the Cash Goes
Red Bull GmbH is privately held and carries no financial debt. It publishes a handful of figures each January and files fuller annual accounts in the Austrian corporate registry later in the year. The company said its growth and investment plans for 2026 would again be financed from operating cash flow.
| Owner | Stake | How they got it |
|---|---|---|
| Mark Mateschitz | 49% | Inherited from his father, Dietrich Mateschitz, in 2022 |
| Yoovidhya family | 49% | Heirs of co-founder Chaleo Yoovidhya |
| Fides Trustees | 2% | Swing stake formerly held by Chalerm Yoovidhya, transferred in 2025 |
The owners are paid through dividends, and those dividends have been large relative to profit. In 2025, on 2024 results, Red Bull paid Mark Mateschitz and the Yoovidhya family €648 million each for their 49% stakes, plus about €30 million on the 2% stake, a total of roughly €1.3 billion that included €500 million drawn from retained earnings. Measured against 2024 net income of about €1.7 billion (implied by the 12% rise to €1.9 billion in 2025), that is a payout of more than three quarters of the year’s profit. A dividend on 2025 results had not been announced when the accounts were published.
That combination, high payouts, zero debt and a marketing budget larger than profit, only works because the core product throws off steady cash and the manufacturing capital sits on partners’ balance sheets.
Key Resources
- The Red Bull brand and trademarks
- The athlete roster, teams and event properties
- Red Bull Media House and its content library
- Distribution organizations and cooler networks
- Long-term manufacturing partnerships with Rauch and Ball
Key Activities
- Brand building through sponsorship, events and content
- Distribution, merchandising and category management at retail
- Product development, including editions and zero-sugar variants
Key Partners
- Rauch Fruchtsäfte (filling) and Ball Corporation (cans)
- Independent distributors and retailers
- Athletes, teams, leagues and event organizers
- Broadcasters and streaming platforms
Cost Structure
- Marketing, roughly €3.1 billion in 2025, about half of it paid to athletes and teams
- Product costs: cans, filling, ingredients and freight
- Distribution and field sales staff
- Team and media operations
Where the Red Bull Business Model Is Exposed
The same features that make the model work are the ones now under pressure.
Control of the shelf is under investigation. On November 13, 2025, the European Commission opened a formal antitrust investigation into whether Red Bull abused a dominant position. It is examining two practices: incentives allegedly offered to supermarkets and fuel station shops to delist or disadvantage rival energy drinks sold in cans larger than 250 ml, and the possible misuse of Red Bull’s role as category manager, the supplier a retailer trusts to advise on the whole energy drink shelf. It is the Commission’s first formal case about category management abuse, and the Netherlands is a particular focus. The investigation is ongoing and does not prejudge the outcome, but an infringement finding can carry a fine of up to 10% of global turnover. The exposure is structural: the store-level control that Red Bull pays for is exactly what the case is about.
Retailers are testing the price. The Kroger delisting shows the limits of pricing power when a retailer has credible substitutes on the shelf. A person familiar with the talks told Bloomberg that Kroger’s energy drink category kept growing without Red Bull, pointing to Alani Nu and Bloom, and that negotiations were ongoing.
Competitors now have their own category captains. Celsius Holdings, which owns CELSIUS, Alani Nu and Rockstar Energy in the US, describes itself as PepsiCo’s energy category captain and held about 20.1% of US energy drink dollar sales in the 13 weeks to June 28, 2026, according to Circana data it reported. Red Bull kept its US share above 35% in 2025, according to Circana data cited by Bloomberg. Our Celsius marketing strategy breakdown explains how that portfolio was assembled.
One product family carries everything. Health rules, caffeine limits, sugar taxes and age restrictions on energy drink sales hit Red Bull harder than a diversified beverage group. Our Red Bull SWOT analysis walks through those threats in detail.
Red Bull vs. Its Main Competitors
| Company | Key energy brands | How it reaches the shelf | Scale marker |
|---|---|---|---|
| Red Bull GmbH | Red Bull, Sugarfree, Zero, Editions | Own distribution arms plus independents | €12.196B turnover (2025) |
| Monster Beverage | Monster, Reign, Bang, NOS, Burn | Coca-Cola bottling system | $8.29B net sales (2025) |
| Celsius Holdings | CELSIUS, Alani Nu, Rockstar (US) | PepsiCo distribution, category captain | About 20% US dollar share (Q2 2026) |
| Private label and value brands | Retailer brands such as Aldi’s Red Thunder | Retailer’s own supply chain | Price pressure at the low end |
Coca-Cola and PepsiCo compete in energy mostly through partners rather than their own flagship brands: Coca-Cola through its stake in Monster and PepsiCo through its stake in and distribution deal with Celsius. That leaves Red Bull as the only one of the three largest US energy drink companies that does not rely on a soft drink giant’s trucks. For a view of how the Coca-Cola system itself makes money, see our Coca-Cola business model breakdown.
Red Bull Business Model FAQ
How does Red Bull make money? Almost entirely by selling energy drinks. In 2025 it sold 13.969 billion cans and booked €12.196 billion in group turnover. Its teams, events and media studio generate some income, but they are run as marketing, not as profit centers.
How much does Red Bull spend on marketing? Red Bull’s 2025 accounts show more than €1.5 billion paid to athletes and teams, which was 48% of the marketing budget. That implies a total of roughly €3.1 billion, about a quarter of turnover and more than its €1.9 billion net income.
Does Red Bull make its own drinks? No. Rauch Fruchtsäfte fills Red Bull cans and Ball Corporation makes them, including at plants in Austria, Switzerland and Glendale, Arizona, with a larger campus under construction in Concord, North Carolina.
Who owns Red Bull? Mark Mateschitz owns 49%. The Yoovidhya family side controls the remaining 51%, including a 2% stake now held by a trustee.
Is Red Bull profitable? Yes. Net income reached €1.9 billion in 2025, up 12%, on turnover of €12.196 billion, a net margin of about 15.6%.
Why is the EU investigating Red Bull? The European Commission is examining whether Red Bull used retailer incentives and its category manager role to push rival energy drinks in cans larger than 250 ml off shelves. The case was opened in November 2025 and has not reached a decision.
The Business Model Analyst Take
The easy story about Red Bull is that it is a media company that happens to sell a drink. The numbers point somewhere more specific. Red Bull is a distribution company that uses media to justify its price.
Look at where it chose to spend and where it chose not to. It will not own a filling line: Rauch and Ball carry that capital, even on the new Concord campus. It will own the warehouse, the delivery and the field team, and it will spend around €3.1 billion a year making sure the can is wanted when it arrives. That is why it employs 3.2 times Monster’s headcount to earn a comparable profit, and why the European Commission’s case is aimed at the shelf rather than at the ads.
The strength of the model is that the owners can reinvest without asking anyone. The risk is that its moat and its legal exposure are now the same asset. If the Commission restricts how Red Bull manages the energy shelf, or if more retailers follow Kroger in calling the price, Red Bull loses some of the store-level control it pays so heavily for, and the premium has to be defended by the brand alone.
Our bet is that the brand can carry more of that weight than the skeptics think, because four decades of consistency are hard to copy. But the growth story of the last six years was volume, not price, and the next chapter will test whether Red Bull can raise the price per can without the shelf pushing back. Watch the 2026 figures in January: if turnover per can rises while volume holds, the model is intact. If volume slows while the price rises, the Kroger standoff was the first crack, not a one-off.
For the wider picture, pair this breakdown with our Red Bull value chain analysis, the Red Bull generic competitive strategy and the company’s mission and vision statement.


