
How 1,432 supermarkets in the Southeast fund a private share market for 260,000 employee-owners, and why the investment portfolio is now bigger than the stores
Publix sells groceries at a 7.4% operating margin, roughly triple what the average American food retailer earns, and then spends the surplus running a share market that no exchange will run for it. In 2025 the company paid $1.70 billion in cash to buy stock back from its own employees, more than three times the $561 million of stock it granted them. The $17.7 billion investment portfolio on its balance sheet exists to make that promise credible.
What is the Publix business model?
Publix Super Markets operates 1,432 supermarkets across eight southeastern states, generating $62.7 billion of sales in fiscal 2025 from a single business line with no segments. It captures an unusually wide margin for grocery by selling service, fresh departments and private label rather than price, and it recycles the resulting cash into two places: new stores it builds without debt, and an internal market where its 260,000 employees buy and sell a stock that trades nowhere else. The board sets the share price quarterly using an independent valuation benchmarked against listed grocers.
Two engines, one balance sheet
Read the income statement and Publix looks like a very good supermarket chain. Read the balance sheet and something else shows up.
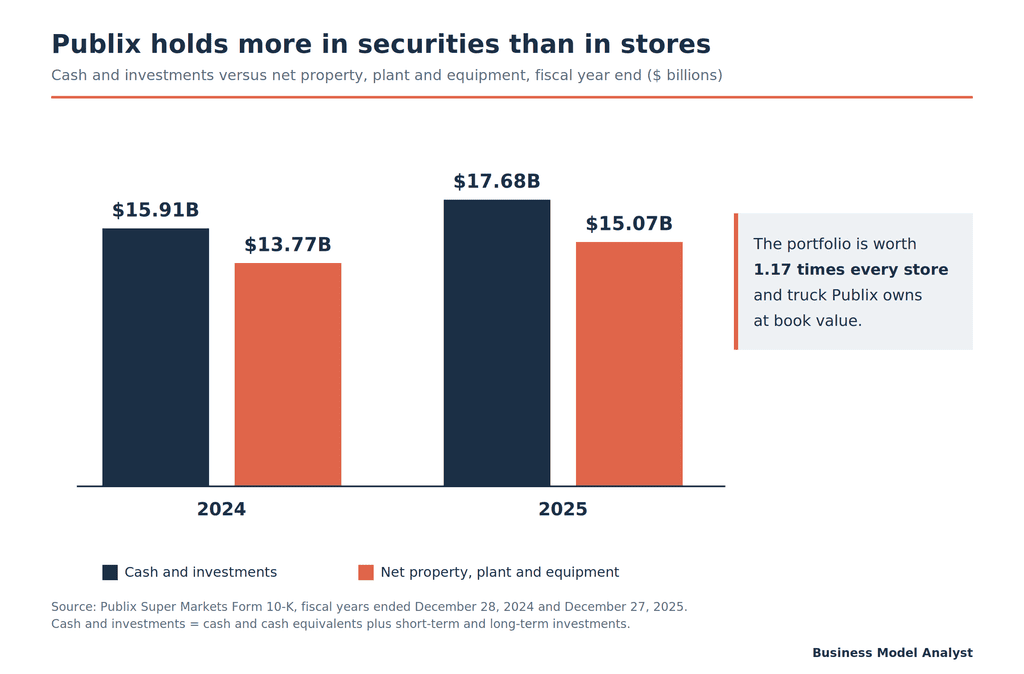
Cash and investments totaled $17.68 billion at the end of fiscal 2025. Net property, plant and equipment, which covers every store, distribution center, dairy plant, bakery, truck and freezer case the company owns, came to $15.07 billion. The securities are worth 1.17 times the physical business.
No listed grocer carries that shape. Kroger runs at 1.76x net debt to adjusted EBITDA and returns its spare cash through buybacks. Publix carries no borrowings at all, owns its corporate offices, distribution centers and manufacturing plants free of debt, and sits on a bond and equity portfolio large enough to buy a mid-cap company outright.
The portfolio is not idle. It is the working capital of the second business.
How Publix makes money
The revenue model is plain. Publix buys merchandise, moves about 67% of it through ten of its own distribution centers, manufactures some of it in six plants and three prepared-foods facilities, and sells it through supermarkets averaging 47,346 square feet. Pharmacy, liquor stores, floral, deli and prepared foods sit inside the same box. There is no retail media network, no membership fee, no third-party marketplace and no meaningful e-commerce build.
| Fiscal 2025 income statement | $ millions | % of sales |
|---|---|---|
| Sales | 62,749 | 100.0% |
| Cost of merchandise sold | 46,820 | 74.6% |
| Gross profit | 15,929 | 25.4% |
| Operating and administrative expenses | 11,765 | 18.7% |
| Operating profit | 4,624 | 7.4% |
| Investment income | 1,210 | |
| Other nonoperating income | 127 | |
| Pretax earnings | 5,961 | |
| Net earnings | 4,734 | 7.5% |
| Net earnings excluding fair value adjustment | 4,203 | 6.7% |
Two things in that table deserve more attention than they usually get.
The first is the gap between operating profit and pretax earnings. Investment income plus other nonoperating income came to $1.34 billion, which is 22.4% of pretax profit. Strip out the unrealized gains on equity securities, which swing with the stock market and which management itself backs out, and the portfolio still contributed $624 million against $5.25 billion of adjusted pretax earnings. Around one dollar in eight of Publix’s pretax profit comes from securities rather than aisles.
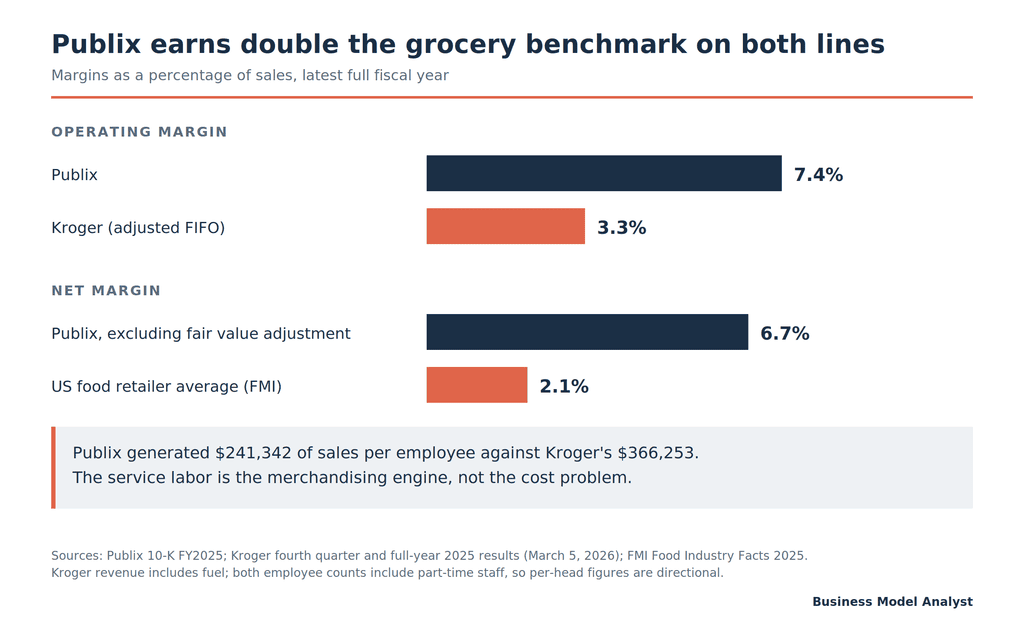
The second is the 7.4% operating margin. FMI put the average net profit for US food retailers at 2.1% in 2025. Publix earned 6.7% net excluding the fair value swing, more than three times the industry benchmark. Kroger, the closest listed comparison at $147.6 billion of sales, delivered $4.9 billion of adjusted FIFO operating profit, a 3.3% margin. Publix runs at roughly double that on a fraction of the revenue.
Where the margin comes from
Publix does not win on cost per labor hour. It loses on it, on purpose.
The company generated $241,342 of sales per employee in 2025 against Kroger’s $366,253, a third less per head. Some of that gap is mix, since Kroger sells fuel and Publix does not, and both figures count part-timers as heads rather than full-time equivalents. The direction still holds. Publix carries about 182 employees per store to staff deli counters, bakeries, sub stations and bag-to-car service that discounters have removed.
That labor buys three things.
Store productivity. Publix averaged $855,000 of weekly sales per supermarket in 2025 against FMI’s industry average of $668,377, a 28% premium. Publix stores run about 12% larger than the industry average, so roughly half the gap is floor space and the other half is throughput.
Gross margin. Publix held 25.4% gross margin against Kroger’s 22.9%. Manufacturing its own dairy, bakery and deli products captures the processor’s margin, and the fresh and prepared departments carry mark-ups that packaged grocery cannot.
Expense discipline. Operating and administrative expenses fell to 18.7% of sales from 18.9%, helped by lower advertising and payroll as a percentage of sales. A chain concentrated in one region, with 889 of its 1,432 stores in Florida, spends less on distribution miles and media than a national operator does.
Owning real estate helps too. Publix owns both building and land at 473 locations and the building at 77 more, and it buys the shopping centers its stores anchor. Rent that would otherwise leave the business stays inside it.
The second business: an internal stock market
Here is the part the grocery coverage skips.
Publix stock trades on no exchange. The company sells shares to current employees and directors through an Employee Stock Purchase Plan and a directors plan, and to participants in the 401(k) plan. It contributes shares through a trusteed, non-contributory ESOP whose annual contribution the board approves at its discretion. That contribution cost $561 million in 2025, against $516 million in 2024 and $491 million in 2023. Spread across the whole workforce, it works out to roughly $2,158 per employee per year, and higher per eligible employee since the plan requires service before participation.
Every plan document blocks transfer for value unless the holder offers the shares to Publix first. Publix is the registrar, the transfer agent and the only buyer.
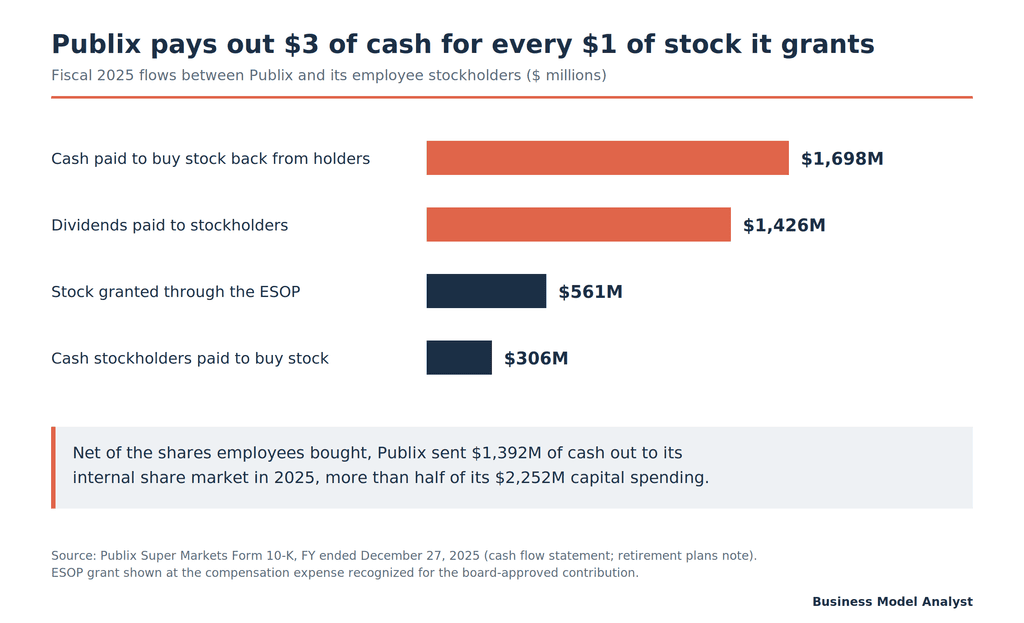
So the company buys. In 2025 it paid $1.698 billion in cash to acquire 85 million shares from stockholders and received $306 million from selling 16 million shares to them. Set that against the ESOP grant and the ratio is stark: for every $1 of stock Publix hands its employees, it pays $3.03 in cash to buy stock back from them, or $2.48 net of the shares they buy.
That is the cost of being your own exchange. A listed company’s employees sell to strangers. Publix’s employees sell to Publix, and Publix funds it from the balance sheet.
The obligation shows up as a separate line above stockholders’ equity. Common stock related to the ESOP stood at $4.925 billion at the end of 2025, up from $4.029 billion at the end of 2022, a 22% increase in three years. It rises with both the share count and the board-set price, so a rising stock price makes the liability larger. The $17.68 billion portfolio covers that line 3.6 times over.
The over-collateralization is the point. Publix states in its own filing that except for certain shares distributed from the ESOP, these repurchases are not required and it retains the right to discontinue them at any time. The liquidity that makes the stock feel like a stock is a voluntary promise, and Publix funds it as if it were not.
What an employee-owner actually holds
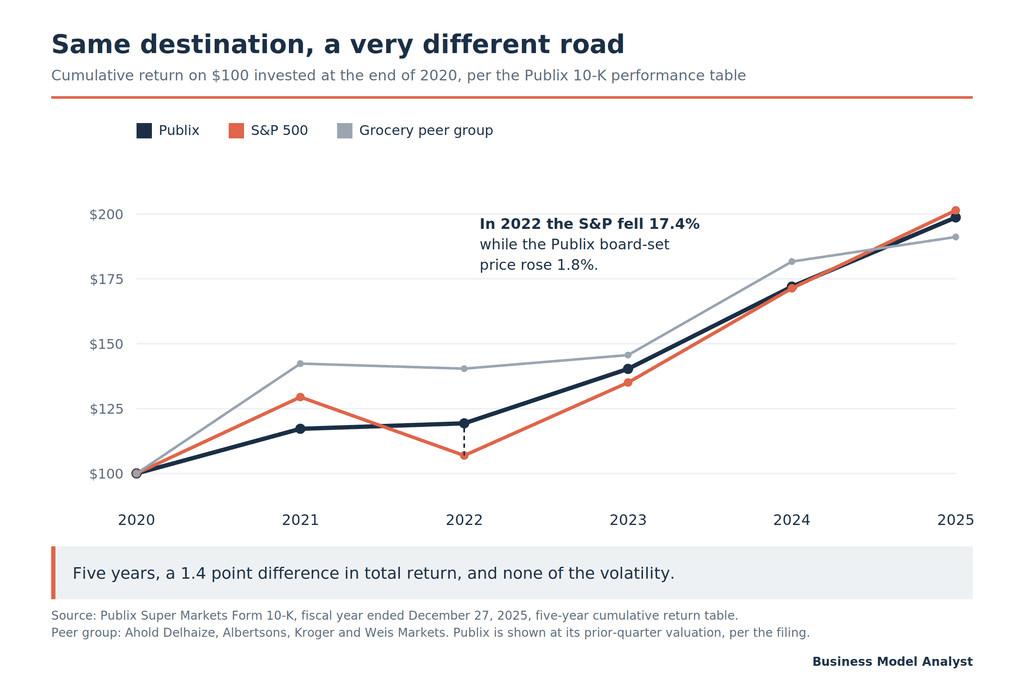
With no market, the board sets the price. An independent valuation compares Publix to comparable listed companies, and the 10-K names Ahold Delhaize, Albertsons, Kroger and Weis Markets as the peer index used for return comparison.
That creates a loop worth sitting with. A Publix cashier’s retirement balance gets repriced partly on how investors feel about four companies she does not work for. When grocery multiples compress, her shares fall even if her store’s sales rose.
2026 has run that experiment twice. Publix cut the price from $20.40 to $19.65 effective March 1, 2026, lifted it to $20.45 on May 1, then cut it to $19.60 on August 1. The August price sits 7.3% below the $21.15 that ran from August to October 2025. Over the same stretch, earnings excluding the fair value adjustment rose 3.9% in 2025 and stayed flat through the first half of 2026.
The smoothing cuts the other way too. Using the cumulative return table in the 10-K, $100 invested at the end of 2020 became $198.68 in Publix stock by the end of 2025, against $201.43 in the S&P 500 and $191.16 in the grocery peer index. Same destination, different road. In 2022 the S&P index fell 17.4% while Publix’s board-set price rose 1.8%. Employee-owners got equity-like returns on an appraisal-smoothed path, which is a real benefit until the appraisal catches up.
Competitive position
Publix holds 889 stores in Florida and is adding density northward, with Kentucky going from 1 store to 6 in 2025 and another 6 under construction, plus Virginia at 24.
The pressure is coming from below. Aldi bought roughly 400 Winn-Dixie and Harveys stores in the Southeast and is converting them, opened about 60 Florida locations in 2025, and plans more than 180 US stores in 2026 as part of a $9 billion American investment through 2028. Walmart competes on price at national scale. Kroger, under Greg Foran, has committed to lowering prices on thousands of items.
Publix has not answered with a general price cut, and its financial structure explains why. A chain earning 7.4% operating margin from service and fresh cannot fund an across-the-board price war without dismantling the surplus that funds the share buyback. Its response has been promotional pricing, a new larger store format with self-checkout lanes, beverage and hot-food counters, and pharmacy plays such as discounted GLP-1 pricing.
The first half of 2026 shows the squeeze. Sales rose 1% in the second quarter with comparable store sales down 0.5%, hit by the Medicare maximum fair price change on ten drugs and by softer consumer spending. Publix has now posted negative comps against a cost base built for service.
The compact canvas
| Block | Publix |
|---|---|
| Value proposition | Service, fresh and prepared food, store quality, convenience; premium positioning rather than lowest price |
| Key resources | 1,432 stores, 67.8m sq ft, 10 distribution centers, 6 manufacturing plants, 260,000 employees, $17.7bn portfolio |
| Key activities | Retail operations, own-label manufacturing, self-distribution, real estate acquisition, internal share market administration |
| Revenue streams | Merchandise sales, pharmacy, liquor, prepared foods, investment income |
| Cost structure | Merchandise 74.6% of sales, operating and administrative 18.7%, capex $2.3bn |
| Customer relationships | Club Publix loyalty program, BOGO promotions, in-store service |
| Key partners | Suppliers and contract manufacturers, shopping center developers |
| Ownership | Present and former employees plus the Jenkins family; no public listing |
What could break it
The price loop runs backwards. If listed grocery multiples keep compressing, the board keeps cutting the price, and the ESOP stops feeling like a wealth engine. Recruiting a service workforce gets harder at the exact moment Publix needs it most.
The buyback outgrows the cash flow. Gross repurchases plus dividends came to $3.12 billion in 2025 against $2.25 billion of capex. Cash acquisition of stock has climbed from $1.165 billion in 2023 to $1.698 billion in 2025, a 46% rise in two years, faster than earnings. Publix controls how many shares it grants. It does not control how many its retirees offer back.
Aldi wins on the trip that matters. Publix’s model needs the big weekly basket. Discounters taking the fill-in trip is survivable. Taking the stock-up trip is not.
Florida concentration. Sixty-two percent of stores sit in one hurricane-exposed state whose population growth carried the chain for two decades.
Frequently asked questions
Who owns Publix? Present and former employees plus members of the Jenkins family. There were about 259,000 holders of record as of February 2026 and 3.21 billion shares outstanding. No shares trade publicly.
Can the public buy Publix stock? No. Shares are sold only to current employees, directors and 401(k) participants, and every plan requires holders to offer shares back to Publix before any transfer for value.
How is the Publix share price set? The board sets it, informed by an independent valuation that compares Publix’s financial results to comparable publicly traded companies. The price changes effective March 1, May 1, August 1 and November 1.
How profitable is Publix compared with other grocers? Publix earned 7.5% net margin in fiscal 2025, or 6.7% excluding unrealized investment gains, against an FMI industry average of 2.1% and Kroger’s 3.3% adjusted FIFO operating margin.
Does Publix have debt? No borrowings. The company funds stores, buybacks and dividends from internally generated cash, and states that its corporate offices, distribution centers and manufacturing facilities are owned with no outstanding debt.
How much does Publix contribute to employee stock? The board approved a discretionary ESOP contribution costing $561 million in 2025, alongside a 401(k) plan and an employee stock purchase plan.
The Business Model Analyst Take
Most write-ups treat Publix’s employee ownership as culture and its margin as an outcome of that culture. Run it the other way. The ownership structure is a financing decision, and it dictates the asset mix.
A listed grocer converts surplus cash into buybacks that shrink the share count and lift the multiple, because a stock exchange handles liquidity for free. Publix has no exchange, so it must hold the reserve itself, which is why $17.7 billion sits in securities instead of in stores, acquisitions or e-commerce infrastructure. The conservatism people admire in Publix is a requirement of the ownership structure, not a preference.
Compare it with Lodge Cast Iron, which shares 20% of pretax profit with employees and zero equity. Lodge keeps the asset and pays out cash flow. Publix hands over the asset and then has to buy it back forever. Both are answers to the same question about what owners give up to keep control, and Publix’s answer is the more expensive one.
For founders the transferable lesson has nothing to do with groceries. If you grant equity in a company with no market, you have taken on an obligation that grows with your own valuation, and you will need a balance sheet to honor it. Publix built one first. Most companies discover the bill later.
The number to watch is not comparable store sales. It is the cash line for acquisition of common stock. When that figure starts growing faster than operating cash flow, the internal market has become the constraint on the grocery business rather than a benefit of it.