
Progressive sorts American households into four named segments, and its entire product roadmap is built to move them up one rung at a time. The problem is that the top rung shops the least and buys through somebody else’s agent.
Progressive’s target market is not a demographic. It is a position on a ladder defined by two questions: does this household stay continuously insured, and does it buy its home and auto coverage from the same company? Answer those and Progressive knows which of its four internal segments you belong to, roughly what you are worth over a lifetime, and how hard it should bid to get you.
The company has been unusually public about this. It named the segments in 2008, built the Destination Era strategy around them in 2014, and spent 45 minutes of its August 2026 investor event on a single one of them. What almost nobody does is take the taxonomy seriously as a business model question rather than a marketing slide. When you do, an uncomfortable pattern shows up: Progressive holds its largest share in the segment that leaves fastest, and its smallest share in the segment that barely shops at all.
Progressive’s target market is the set of US households and small businesses it prices and bids for, organized internally into four personal lines consumer segments (Sams, Dianes, Wrights, Robinsons) defined by insurance continuity and home and auto bundling, plus five commercial auto business market targets defined by vehicle use. The segments are pricing and acquisition categories, not advertising personas.
Progressive’s target market at a glance
| Dimension | Where Progressive actually sits |
|---|---|
| Primary customer | US personal auto households, roughly 80% of companywide premium |
| Segment framework | Sams, Dianes, Wrights, Robinsons (personal lines); five business market targets (commercial auto) |
| Largest untapped segment | Robinsons, almost 35% of the US auto market, Progressive share near 4% |
| Household reach | Nearly one in four US households hold at least one Progressive personal lines product |
| Business customers | Small operators averaging about two vehicles per policy, plus one very large rideshare account |
| Channel split | Personal vehicle 43% agency / 57% direct; commercial auto about 90% agency |
| Geographic footprint | All 50 states, with California run as a separate agency auto organization |
| Product used as the front door | Personal auto, because it renews often and gets shopped often |
The four segments, in Progressive’s own words
Most write-ups of Progressive’s segmentation get the first rung wrong. They describe a Sam as a monoline auto buyer, someone who owns only a car policy. That is not the definition Progressive uses in its own filings.
In its quarterly reports the company defines the four segments this way: Sam is inconsistently insured. Diane is consistently insured and may be a renter. Wrights are homeowners who do not bundle auto and home. Robinsons are homeowners who bundle auto and home. Progressive’s FY2019 annual report is blunter still, referring in passing to “our inconsistently insured segment (i.e., Sams).”
The distinction matters more than it looks. The bottom rung is not defined by how many products you buy. It is defined by whether you stay covered at all. That is a lapse-risk category, and it is the direct descendant of the nonstandard book Progressive built its early business on. Everything above it is defined by stability first and product count second.
At the August 2026 investor event Progressive put numbers on all four for the first time in this level of detail.
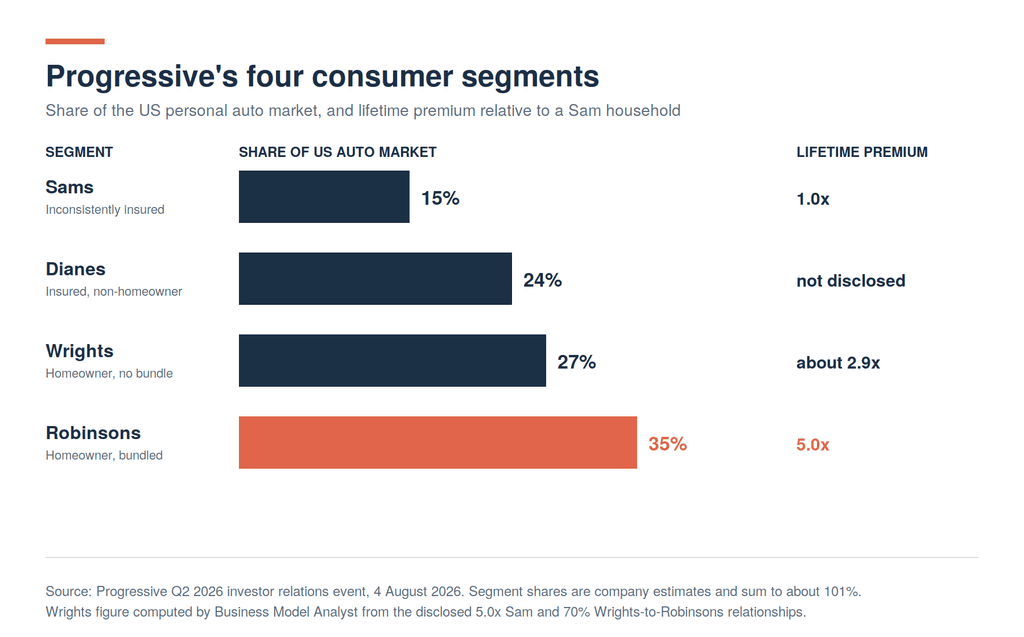
The Wrights figure is ours. Progressive disclosed that a Robinson household generates roughly 70% more lifetime premium than a monoline Wright and five times the lifetime premium of a Sam. Those two statements imply a Wright at about 2.9 times a Sam. Diane has never been quantified publicly, so we leave it blank rather than guess.
Read down that table and the ladder is obvious. Value rises with stability. So does tenure: Progressive told investors back in 2022 that Robinson households carry roughly three times the policy life expectancy of the Sam segment. Policy life expectancy is Progressive’s own retention metric, defined in its annual report as the actuarial estimate of how long a policy stays in force before cancellation or lapse.
Where Progressive’s share actually sits
Here is the part that reframes everything. Progressive held 18.60% of the US private passenger auto market on 2025 NAIC filings, a whisker behind State Farm at 18.64%. Management described the company as the largest US personal auto writer at the August 2026 event, and trailing-twelve-month estimates support that, but published NAIC annual data still has State Farm marginally ahead, so treat the number one claim as unsettled. But management has been explicit that it built that position while primarily serving Sams, Dianes and Wrights, which together are roughly two thirds of the market. Its Robinsons share is around 4%.
Back that out and the picture separates cleanly. If Robinsons are 35% of the market at a 4% share, the arithmetic implies Progressive holds something close to 26% of the other 65%. Two thirds of the market where it is a dominant player. One third where it is a rounding error. That is not one company with an 18.6% share. It is two companies stapled together, and only one of them is winning. The capital consequences of winning the first one so decisively are covered in our piece on Progressive dethroning State Farm and the cash problem that followed.
(Segment shares are Progressive’s household-level estimates while the NAIC figure is premium-based, so treat 26% as directional rather than exact.)
Why the gap closes slowly
The obvious question is why a company this good at pricing has spent more than a decade stuck at low single digit share in the segment it wants most. The usual answers are product quality and property availability, and both are real. Neither is the binding constraint.
The binding constraint is arithmetic. Progressive’s acquisition engine converts quotes into policies. Advertising buys quotes. Quotes only happen when a household shops. And Robinsons, by construction, are the households that shop least.
Take the disclosed inputs and index them. Robinsons are 35% of the market with roughly three times the tenure of a Sam, so their annual shopping flow indexes at about 11.7. Sams are only 15% of the market but turn over three times as fast, so their flow indexes at 15.0. The smallest segment in the market generates more annual shopping events than the largest one.
Then apply the channel filter. Progressive told investors that about 85% of Robinsons auto premium is sold through independent agents. Strip that out and the Robinson flow reachable without an agent relationship falls to roughly 1.8, against 15.0 for Sams. Roughly a nine-to-one difference in annual shopping opportunity between the segment Progressive says it wants and the segment it already owns.
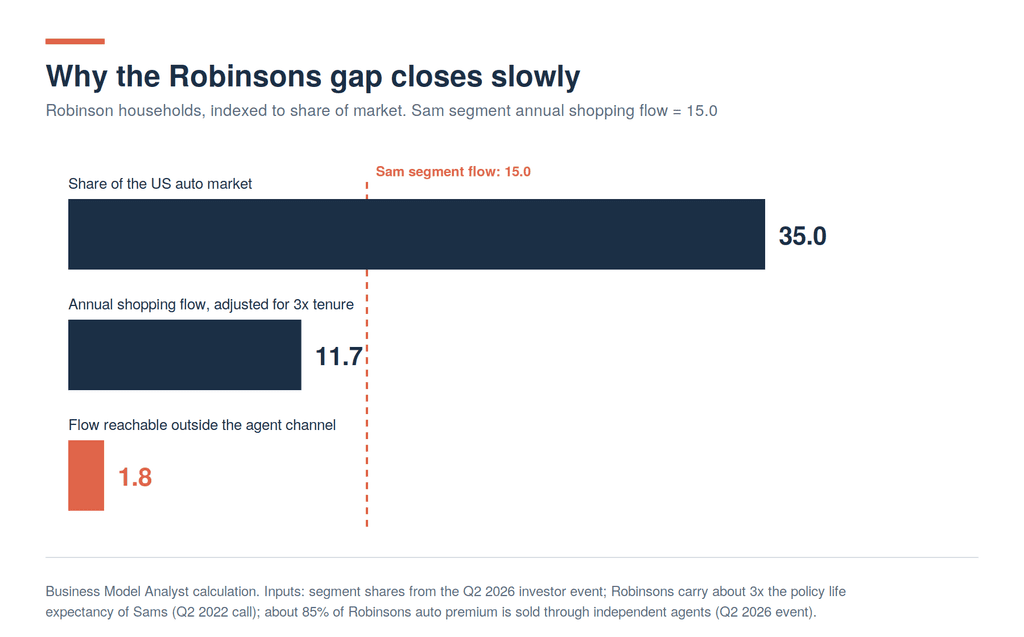
That is a modeled scaling, not a company disclosure, and it leans on a 2022 tenure ratio. But the direction is not in doubt, and it explains something the share numbers alone do not: why Progressive can be simultaneously excellent at pricing and slow at Robinsons. You cannot outbid a household that never enters the auction.
It also explains why Progressive keeps describing personal auto as the front door. Auto renews on six or twelve month terms and gets shopped constantly. Home does not. If you want to reach a bundled household, the auto policy is the only door that opens regularly, which is exactly why Progressive treats its number one auto position as an asset for a market it has not yet won.
The escalators between rungs
Once you see the segments as rungs, Progressive’s product roadmap stops looking like a list of features and starts looking like a set of escalators. The company even uses the word: its FY2017 shareholder letter described the Progressive Advantage Agency’s job as supporting “the graduation to Robinsons,” and management returned to graduation language at the 2026 investor event.
The machinery, rung by rung:
- Sam to Diane. Product model 9.0, rolling out since Q3 2025, introduced embedded renters insurance as an optional endorsement on the auto policy. A renter who buys auto coverage now becomes a multi-product household without ever completing a second purchase. Management framed it at the 2026 investor event as a way to start relationships with young adults before they become homeowners.
- Diane to Wright. Nothing Progressive sells causes this. It is a life event, and the company’s job is to still be there when it happens.
- Wright to Robinson. This is where the money and the friction are. In the agency channel, the Platinum program and the Portfolio quoting system exist to make a bundled quote easy for an agent to produce. In the direct channel, HomeQuote Explorer does the same job, offering 26 property products from 19 carriers, with quote starts compounding at about 27% a year from just under a million to more than six million.
- Sideways. Special lines is the underrated rung. Progressive says it is the market share leader in both motorcycle and boat and one of the largest RV writers, and its R17 model added 27 enhancements to expand segmentation. Toys attach to households that already have a home and a garage, which makes special lines both a margin product and a Robinson detector.
The escalator has one visible fault. Progressive’s FY2024 disclosure noted that personal property retention fell partly because of a mix shift toward renters policies, which carry lower policy life expectancy. Embedded renters makes the auto policy stickier while making the property book less so. That is a trade the company appears willing to make, but it is a trade.
What 2025 actually did to the mix
The FY2025 annual report contains the sharpest single paragraph on Progressive’s target market that anyone published last year, and almost nobody quoted it. In the agency channel, quote volume rose 6% while conversion fell 1%. Every consumer segment saw quote volume rise except Robinsons, who saw a moderate decline. Conversion fell for Robinsons and Wrights, and rose in the low single digits for Sams and Dianes. Wrights delivered strong policy growth on flat new applications. Robinsons delivered flat policy growth on negative new applications.
Progressive attributes the Robinson decline to its own doing: profitability initiatives in the property business, beginning in the second half of 2024 and focused on home and condo coverages, which restricted new homeowners applications and therefore choked the bundle.
Read plainly, 2025 was the year Progressive’s acquisition machine leaned back down the ladder. It bought more Sams and Dianes, held Wrights, and deliberately stopped feeding the segment it says is its future. The company would call that sequencing, and it has a case: you cannot sell bundles in states where you will not write the home policy, and the property book had to be repaired first. Whether the growth cost was worth it is the open question for 2027.
The other target market: five vehicle uses and one giant account
Progressive’s commercial customer is defined by what the vehicle does, not who owns it. The FY2025 10-K lists five business market targets: for-hire specialty, for-hire transportation, tow, contractor, and business auto. The typical customer insures about two vehicles.
This half of the business is nearly the mirror image of personal lines. Roughly 90% of commercial auto premium is written through agents, against 43% in personal vehicle. Progressive has ranked number one in US commercial auto since 2015, in a market of about 340 competitors where the leading firms hold 88% of the premium. The company also sells a business owners policy, available to agents in 46 states, plus workers’ compensation aimed at trucking through a limited broker network, and it runs BusinessQuote Explorer as the direct front door for small operators.
Sitting apart from all of it is the transportation network company book, which is Uber subsidiaries in 14 states, written entirely direct, and worth 14% of Commercial Lines premium. Progressive’s small business target market is therefore barbelled: thousands of two-truck operators reached through agents, and one enormous account reached through a contract.
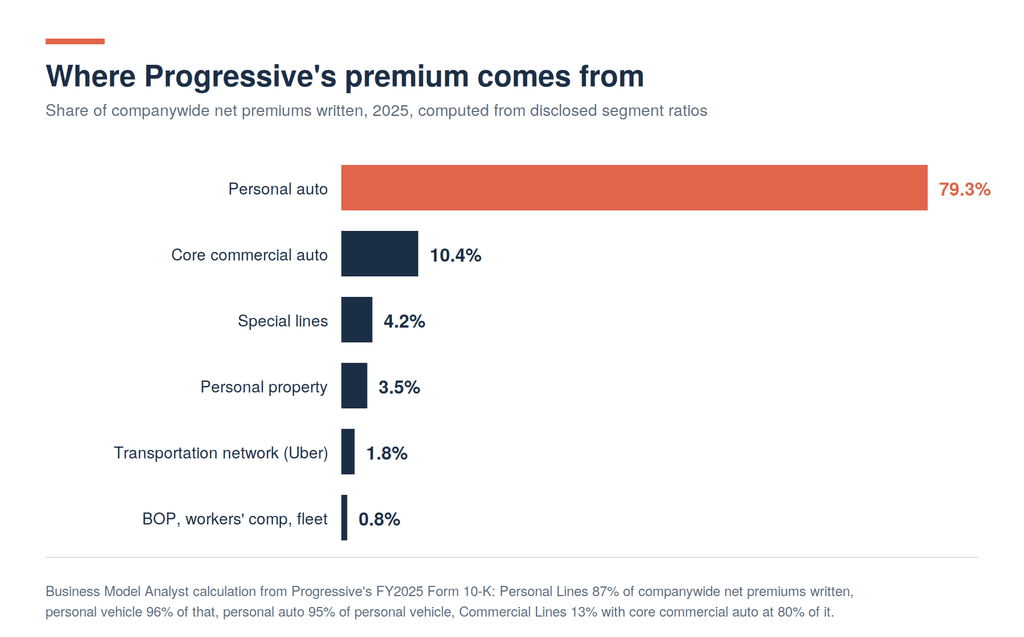
Put the whole company on one chart and the strategic tension is visible. Personal auto is just under 80% of premium. The two products that make the Robinson bundle possible, special lines and personal property, are about 7.7% of premium between them. Progressive is spending a large share of its strategic attention on the smallest slice of its revenue, because that slice is the gate to the largest slice of the market.
Each segment buys in a different place
Target market and distribution are the same question at Progressive, because each segment sits in a different channel.
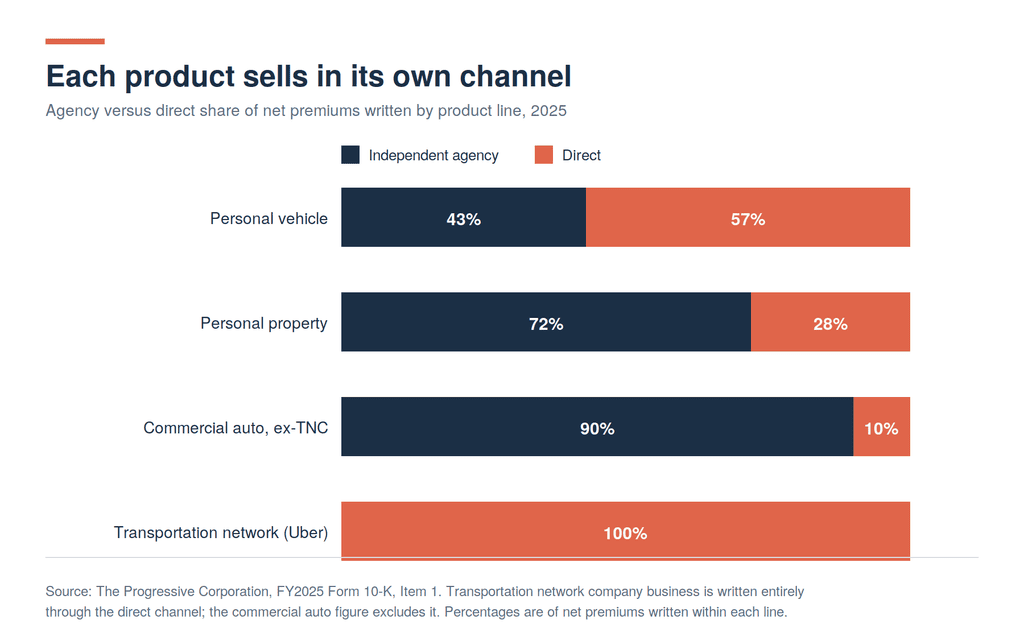
Progressive’s growth has come in the direct channel, where personal vehicle premium moved from 54% to 57% of the mix across 2023 to 2025. Its property book, the Robinson gate, still runs 72% through agents. Its commercial book runs 90% through agents. The segments Progressive wants most are concentrated in the channel where it does not control the relationship, and where its own Platinum roster has been thinning rather than growing.
California deserves a line of its own. Progressive runs a separate agency auto organization there with its own management, and its telematics program is unavailable in the state. For a company whose segmentation depends on behavioral data, the single largest state market is a different business.
Who Progressive does not target
Worth stating plainly, because target market analysis is as much about exclusion as inclusion.
- Large commercial fleets outside its specialty programs. The book is built around two-vehicle operators. Large fleet exists, but as a program, not the core.
- High-value homeowners. Progressive is the twelfth largest homeowners carrier in a market with about 360 competitors. It has spent two years reducing catastrophe-exposed property rather than chasing premium.
- Life and health. Progressive brokers third-party life, pet and specialty car coverage for commission rather than underwriting it. Those products exist to hold the household, not to make money on their own.
- International. Everything is US, with subsidiaries licensed in Bermuda and Canada for structural reasons rather than as a market push.
What the segmentation adds up to
Progressive’s four names describe positions, not people. A household moves between them, and the company’s job is to be present at the moment of movement. That gives Progressive a genuinely unusual growth model for an insurer: it does not need to win new customers so much as re-win existing ones at the moment their life changes.
The catch is that the model has an inverse relationship with value. The households worth the most move the least, and when they do move they move through an agent’s office. Progressive has three responses in flight, all of them expensive and all of them slow: rebuild the property book so agents have something to bundle, use embedded renters to catch households before they become homeowners, and use the auto policy’s high renewal frequency as the only regularly opening door into a bundled home.
None of that is a pricing problem, which is worth sitting with. Progressive spent thirty years turning risk selection into a durable advantage. The next thirty depend on something the pricing engine cannot solve: showing up in a room it does not own, in front of a household that had no plans to shop.
FAQ
Who is Progressive’s target customer? US households that own or lease a vehicle, sorted internally into four segments by insurance continuity and bundling, plus small businesses averaging about two commercial vehicles. Personal auto is just under 80% of premium, so the default customer is an auto buyer.
What do Sams, Dianes, Wrights and Robinsons mean? Per Progressive’s own filings: Sams are inconsistently insured, Dianes are consistently insured non-homeowners, Wrights are homeowners who do not bundle auto and home, and Robinsons are homeowners who do. They are pricing and acquisition categories, not advertising personas.
Which segment is most valuable to Progressive? Robinsons, by a wide margin. Progressive puts their lifetime premium at roughly five times a Sam household and about 70% above a monoline Wright, and they carry materially longer policy life expectancy.
Why does Progressive have such low share among Robinsons? Two reasons. They shop far less often than other segments, so they generate fewer quote opportunities per year, and about 85% of their auto premium is placed through independent agents rather than direct. Progressive also restricted new homeowners applications through 2025 while repairing its property book, which paused the bundle.
Does Progressive still target high-risk drivers? Yes, though the framing has changed. The bottom segment is now defined by inconsistent coverage rather than driving record, and management has said openly that it is happy to keep writing Sams as long as they price to target margins.
What is Progressive’s small business target market? Five commercial auto business market targets defined by vehicle use: for-hire specialty, for-hire transportation, tow, contractor and business auto, sold roughly 90% through independent agents. Separately, its rideshare book with Uber subsidiaries in 14 states is written entirely direct.
How much of the US does Progressive reach? Management told investors in August 2026 that nearly one in four US households hold at least one Progressive personal lines product, up from almost one in five at the end of 2023.
The Business Model Analyst Take
The Robinsons presentation Progressive gave in August 2026 was framed as an opportunity story. Read it as a constraint story instead and it is more interesting.
Progressive built a machine that wins auctions. It is arguably the best in the world at pricing an individual risk and converting a quote at an acceptable acquisition cost. That machine has a hard requirement: an auction has to be happening. For two thirds of the US auto market, one is happening constantly, and Progressive has taken roughly a quarter of it. For the remaining third, auctions are rare, and most of them are held in an independent agent’s office where the agent, not the carrier, controls the invitation list.
So the strategic question is not whether Progressive can price Robinsons competitively. It can. The question is whether a direct-first acquisition engine can be retrofitted into a relationship business, and whether the property book, the smallest and most catastrophe-exposed part of the company, can carry that weight. Twelve years into Destination Era, share is roughly 4%. That is not a failure. It is evidence about how slowly this particular door opens.
Our bet: the embedded renters endorsement is the most underrated line item in the whole 9.0 model. It is the only initiative that catches a household before it reaches the segment where the agents are. Everything else is a fight on somebody else’s ground.