


What is a SWOT analysis? A SWOT analysis sorts a company into four buckets. Strengths and Weaknesses sit inside the business, where management holds the controls. Opportunities and Threats sit outside it, where management can only react. For an insurer the internal side means underwriting skill, distribution, capital and reserves. The external side means competitor pricing, regulation, claim costs, and the parts of the market the company has never reached.
Progressive spent 2023 to 2025 doing what the rest of US personal auto could not: raising price fast enough to stay ahead of claim inflation, then cutting price the moment its own data allowed. Rivals took losses and pulled back. Progressive took share. On the August 4, 2026 investor call, CEO Tricia Griffith said the company captured roughly three quarters of total industry premium growth in 2025 and added 2.8 million policies in the year to Q2 2026, crossing 40 million policies in force for the first time.
The 2026 picture reads differently. Progressive is cutting new-business rates in 30 states covering 63% of countrywide premium, raising advertising 16% year over year, and moving most of its insurance entities to a 3.5-to-1 premium-to-surplus ratio by year end. Three levers, pulled together, into a market where the average number of carriers returning a quote on comparative raters has climbed more than 30% since early 2024.
Progressive is not defending a weak position. It is spending a strong one, and the next leg of growth runs through a customer segment it has never won.
Progressive at a Glance
| Item | Figure |
|---|---|
| Founded | March 10, 1937, Mayfield Village, Ohio |
| CEO | Tricia Griffith |
| FY2025 net premiums written | $83.2 billion |
| FY2025 net premiums earned | $81,661 million |
| FY2025 combined ratio | 87.4 |
| H1 2026 combined ratio | 86.9 |
| Policies in force, July 2026 | 40,304 thousand, up about 7% |
| US private passenger auto share, NAIC data year 2025 | 18.60%, $69.006 billion |
| Distribution | More than 40,000 independent agencies, plus direct |
| Float, December 31, 2025 | $68,529 million |
| Debt to total capital, December 31, 2025 | 18.5%, against a stated ceiling below 30% |
| Stated underwriting objective | A 96 combined ratio or better, meaning at least 4% underwriting profit |
Segment combined ratios, H1 2026: property 78.1, agency auto 84.6, commercial 87.1, direct auto 89.0.
Progressive SWOT Matrix
| Strengths | Weaknesses |
|---|---|
| Segmentation depth on a rolling rating-model cadence: 8.9, 9.0, 9.1 | Average written premium per policy has turned negative |
| Agency and direct run as a deliberate barbell, 84.6 against 89.0 in H1 2026 | About a quarter of the margin cushion comes from prior-year reserve releases |
| 18.60% of US private passenger auto, with scale expense leverage | Property is the smallest segment and the only one with flat policy growth |
| $68.5 billion of float against $30.3 billion of equity | Robinsons share stuck near 4% after years of effort |
| Balance-sheet slack: 18.5% debt to capital, $31.1 billion statutory surplus | Platinum agents fell from nearly 7,100 to nearly 6,000 in a single year |
| Property book repaired: 18 green states to 41, peak modeled loss down a third | Snapshot cannot operate in California, about 13% of the market |
| Opportunities | Threats |
|---|---|
| Robinsons bundled households: about 35% of the auto market, roughly 4% Progressive share | Quote density on comparative raters up more than 30% since early 2024 |
| Captive premium migrating to independent agents, where Progressive has 40,000-plus appointments | Rivals restored to profit are bidding again with capital and rate flexibility |
| HomeQuote Explorer placing 26 products across 19 carriers | Auto frequency down 2.5% and miles driven down 4%, a tailwind that reverses |
| Commercial lines turning, medium fleet policies up 30% year over year | Catastrophe exposure rebuilds as property re-enters weather states |
| AI programs aimed first at loss adjustment expense and the expense ratio | California rating rules block behavioral telematics by statute |
| Rating model 9.1 entering its first state in early 2027 | Unfavorable reserve development would erase the accounting cushion |
Strengths
Pricing granularity, shipped on a schedule
Progressive treats its rating plan as a product with a release cycle. Model 8.9 rolled out from January 2024 and reached 17 states, about 40% of personal auto premium, by that December. Model 9.0 started in Q3 2025 and covered 10 states, about a quarter of companywide personal auto net written premium, by year end. Model 9.1 sits in execution planning for a first state in early 2027.
Each release narrows the price a competitor can match and still profit. The habit runs back to 1956, when Progressive Casualty set up as the industry’s first specialty underwriter of nonstandard risk, and it produced most of the category’s distribution firsts: 1-800-AUTO-PRO comparison rating in 1994, the first auto insurance group website in 1995, the first real-time online policy sale in 1997.
Two channels that earn differently on purpose
Independent agents wrote $15,482 million of H1 2026 net premium at an 84.6 combined ratio. The direct book wrote $21,183 million at 89.0. The channel most observers file as legacy earned 4.4 more points of margin on 27% less premium. Q1 2026 splits the same way: agency underwriting margin 17.2%, direct 11.1%.
Progressive keeps both because they do different jobs. Agency supplies margin and reaches households that shop through a person. Direct supplies unit growth, up 10% in July 2026 against agency’s 7%. Neither channel is a waypoint on the road to the other.
Float, and a balance sheet with room left
Loss and loss adjustment expense reserves of $43,310 million plus unearned premium of $25,219 million gave Progressive $68,529 million of float at December 31, 2025. That equals 2.26 times shareholders’ equity of $30,323 million and 70% of a $97,373 million portfolio. Berkshire Hathaway built an empire on the same mechanic, covered in our Berkshire Hathaway business model breakdown. Progressive holds it in a shorter, safer form: fixed-income duration of 3.4 years, weighted average credit quality AA-minus, and $46.5 billion in short-term instruments and Treasuries at March 31, 2026.
Debt sits at 18.5% of total capital against a self-imposed ceiling below 30%. Statutory surplus reached $31.1 billion in Q1 2026. CFO Andrew Quigg told analysts in August 2026 that most insurance entities should reach a 3.5-to-1 premium-to-surplus ratio by year end, freeing capital the company has already begun returning through buybacks.
A property book that finally works
National property leader John Curtis called the turnaround substantially complete on the August 2026 call. States Progressive rates as healthy and ready for growth went from 18 in May 2025 to 41 by June 2026, covering 82% of the US property insurance market. Since 2022 total insured value rose 30% while the modeled one-in-100-year probable maximum loss fell about 33%, because Progressive rotated the book out of high-weather states and non-renewed older coastal Florida homes. The share of insured value sitting in those risky states dropped 23%. By-peril pricing now runs in all but one state, and a 6.0 property model using aerial imagery launched in June 2026.
Property posted a 78.1 combined ratio in H1 2026, the best of any Progressive segment.
Weaknesses
Growth costs money now, and Progressive is paying in premium
In July 2026 Progressive wrote $7,441 million of net premium, up 5%, while policies in force grew about 7%. Premium per policy went negative. The three-year net written premium series shows the same slope: up 21% in 2024, up 12% in 2025, up 5% in July 2026.
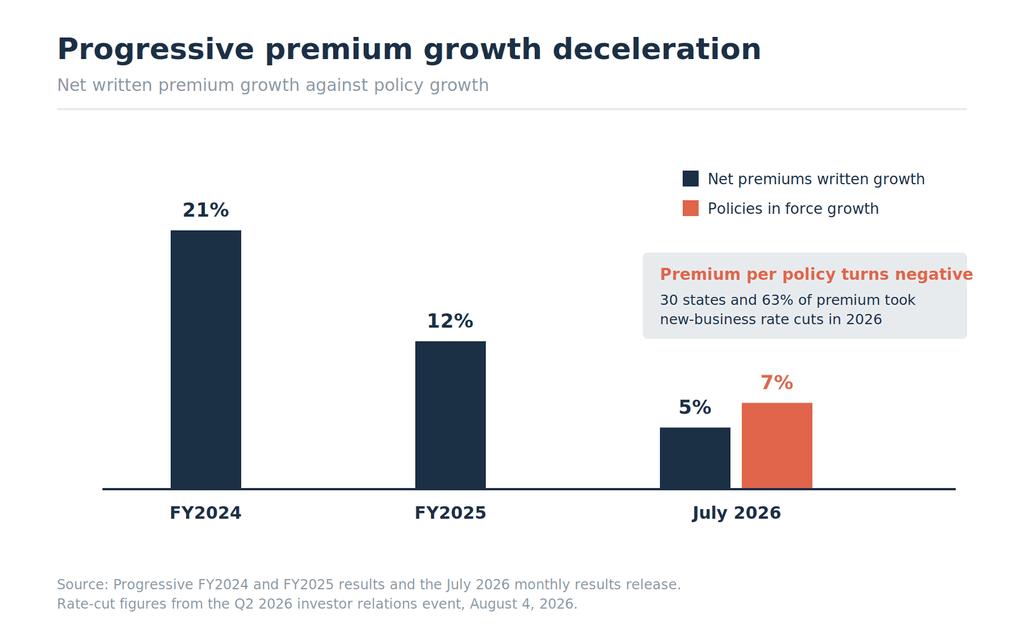
Set that against Q1 2026 advertising of $1.5 billion, up 20%, and Q2 advertising of $1.4 billion, up 16%, and the tempting conclusion is that marketing efficiency broke. That conclusion misses the mechanism. Progressive cut new-business rates in 16 states representing 37% of countrywide net written premium during Q2 alone, and in 30 states representing 63% of premium year to date. Chief personal lines officer Lori Niederst said the company spends on advertising only when cost per sale runs below its target acquisition cost, and that it still does.
The premium decline is a decision. Progressive is converting underwriting margin into price to defend the share it won. The weakness sits in the floor under that strategy: every point of margin handed back moves the combined ratio toward the 96 objective, and the cushion is thinner than the headline suggests.
About a quarter of the cushion is borrowed from earlier accident years
Progressive released $1,002 million of favorable prior-accident-year development in H1 2026 against $42,541 million of net premiums earned. That equals 2.4 combined ratio points. Strip it out and the accident-year combined ratio runs near 89.3 rather than the reported 86.9.
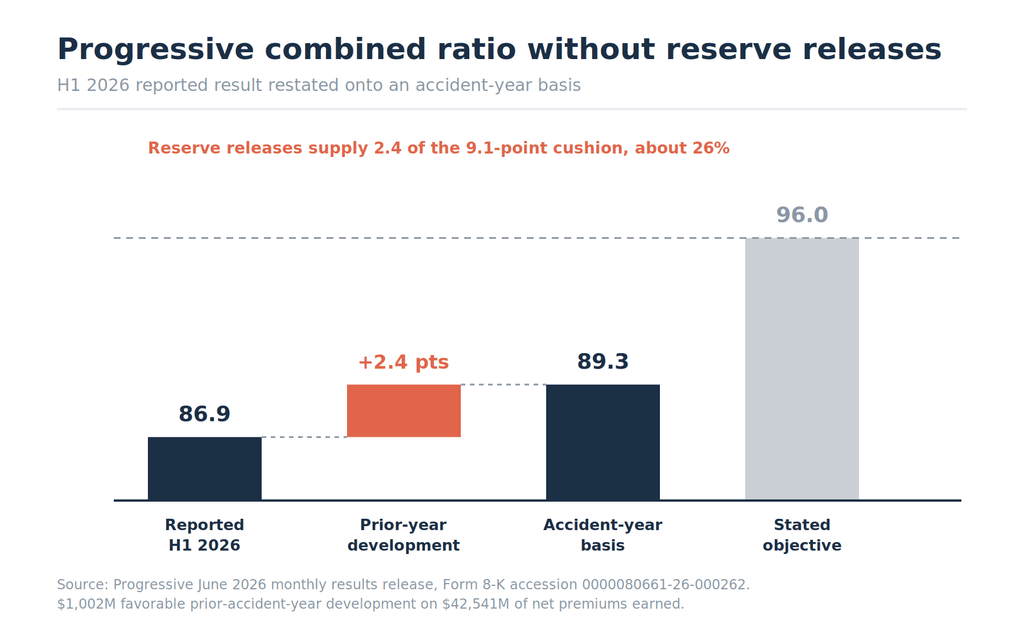
The reported gap to the 96 objective measures 9.1 points. Roughly 26% of it comes from reserves set in earlier years rather than from what Progressive charges today. Conservative reserving produces this outcome and the company has earned the benefit of the doubt on it. Releases are also finite, and they flatter the exact metric management uses to decide how much price it can give away.
Property is the best product and the smallest one
Property carried a 78.1 combined ratio in H1 2026 and 3,635 thousand policies in July, flat year over year. It accounts for about 3.5% of H1 2026 net premium written, against 82.0% for personal lines and 14.5% for commercial.
Progressive needs property to grow because property unlocks bundles. The book is repaired, the state map is open, and policy count has not moved. Each quarter that stays true keeps the bundled-household strategy on the whiteboard.
The Robinsons gap has not closed
Progressive sorts customers into internal names, and Robinsons are the consistently insured households that bundle home and auto. They make up roughly 35% of the US auto market. Progressive’s share of them sits near 4%, against 18.60% of the total private passenger auto market.
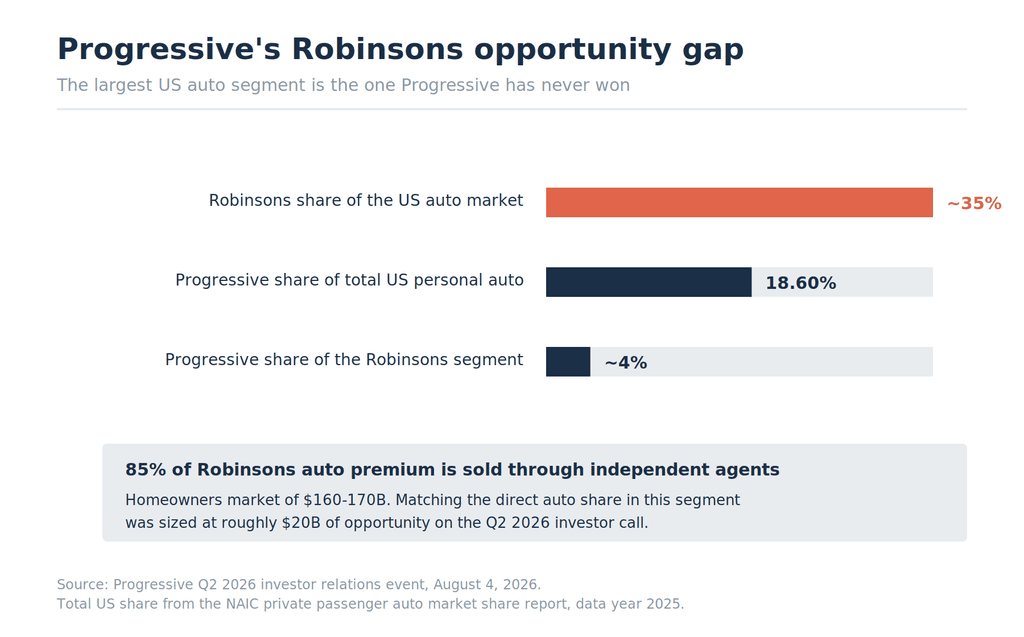
Analysts pressed Griffith on the August call about the delay. She pointed to underinvestment in property segmentation, cost sharing and modeling, plus drag from twelve-month policy terms and the extended Florida non-renewal process. The admission is candid. It also confirms that the largest growth pool available to Progressive has resisted the company’s core weapon for years.
Distribution strain in the channel that matters most
Platinum agents, Progressive’s top independent agency tier, fell from nearly 7,100 at the end of 2024 to nearly 6,000 at the end of 2025. Progressive estimates that 85% of Robinsons auto premium sells through agents.
The company thinned its deepest agency relationships in the same stretch it decided agents were the route to the segment it most wants.
California closes the door on the signature tool
California accounts for about 13.0% of the US private passenger auto market: $48.4 billion of written premium in 2025 against $371.0 billion countrywide. Snapshot does not operate there, and the FY2025 10-K states the exclusion in plain terms.
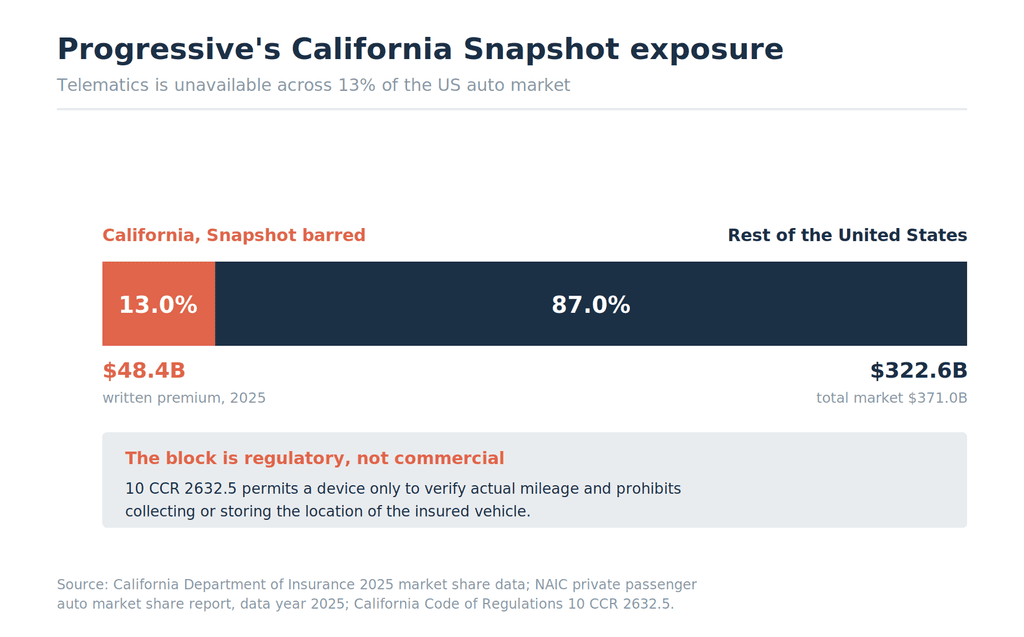
The block is legal rather than commercial. Under 10 CCR 2632.5, California mandates three rating factors in weight order (driving safety record, annual mileage, years of driving experience) ahead of 15 optional ones, and permits a monitoring device only to verify actual mileage while prohibiting collection or storage of the insured vehicle’s location. Behavioral telematics of the kind Snapshot runs cannot enter a California rate. Progressive answered structurally: the 10-K discloses a separate California agency auto organization with its own management and customer relationship systems.
Opportunities
The bundled-household pool
Personal lines president Pat Callahan sized it on the August call. Closing the direct Robinsons share gap to match direct’s auto share would be worth about $20 billion against a $160 billion to $170 billion homeowners market. Direct Robinsons share currently runs near half of direct Wrights share, the adjacent segment.
Progressive now holds the pieces it lacked. The property book is green in 41 states. HomeQuote Explorer places 26 product options across 19 carriers for households Progressive will not underwrite itself. Brand consideration among Robinsons rose 13% over three years.
Captive premium moving to independent agents
Management sees premium migrating from captive-agent carriers toward independent agents and direct. With more than 40,000 agencies appointed, Progressive collects a disproportionate share of anything leaving a captive network. The structural contrast with State Farm’s captive force and mutual ownership is the sharpest one in the category.
Commercial lines turning
Griffith described commercial as reaching a turning point: positive new application growth in Q2, rising trailing-twelve-month policy life expectancy, and medium fleet policies up 30% year over year. Commercial ran an 87.1 combined ratio on $6,498 million of H1 net premium. A commercial book growing again gives Progressive a second engine that does not depend on personal auto price.
AI pointed at expense, not underwriting
Griffith described dozens of generative and agentic AI projects under a new AI strategy council and a responsible AI committee, with the first financial effect expected in loss adjustment expense and the expense ratio. She declined to quantify it and called the story incomplete. For a company competing on cost per policy as much as on rate accuracy, expense-ratio compression is the version of AI benefit that compounds.
Leverage as a growth input
Moving to a 3.5-to-1 premium-to-surplus ratio lets Progressive write more premium off the same capital base. Paired with 18.5% debt to total capital, the company holds two funding sources it has not spent.
Threats
The quote sheet is crowded again
The average number of carriers returning a quote on comparative raters has risen more than 30% since early 2024. That one figure explains most of Progressive’s 2026 experience. Through 2023 and much of 2024, rivals losing money pulled back from rating platforms and cut advertising. Progressive’s price looked good in part because fewer prices appeared beside it. Those carriers repaired their books and returned.
Progressive faces about 230 personal auto competitors, and its own 10-K warns of vigorous competition from large, well-capitalized national companies. The pricing edge survives. It converts to sales at a lower rate.
Falling claim frequency is a borrowed tailwind
Auto frequency fell 2.5% in Q2 2026, which management attributed to mix shift and a 4% decline in vehicle miles traveled. Lower frequency flatters every carrier’s loss ratio, and it is the least durable input in the model. Miles driven recover. Severity trends do not reverse on request.
Catastrophe exposure rebuilds as property grows
Progressive cut its modeled peak loss by a third by leaving weather-exposed states. Growing property means going back. Curtis described slow expansion into higher-weather-risk states as pricing and exposure management mature. Every point of property growth in Florida, Texas or the Gulf adds back volatility the company spent four years removing.
The number-one claim is not settled
Progressive management describes the company as the largest US personal auto writer. Published NAIC data for data year 2025 does not show that. State Farm holds 18.64% and $69.164 billion; Progressive holds 18.60% and $69.006 billion, a gap of $158 million on a $371 billion market. S&P Global Market Intelligence shows Progressive ahead on a trailing-twelve-month basis through March 31, 2026, while noting that its figure includes estimates for two New Jersey-domiciled Progressive subsidiaries that file no public quarterly statements, and that public data still shows State Farm slightly ahead.
The gap collapsed from $7.7 billion in 2024 to $158 million in 2025, so the crossover is arriving. Public filings have not confirmed it. The cash-and-capital dimension of that race runs in our separate piece on how Progressive dethroned State Farm and created a cash problem.
Regulatory ceilings on the pricing model
California blocks behavioral telematics by rule. New York permits Snapshot as a discount only, with no surcharge, 120 days of monitoring, and re-monitoring every 36 months. Snapshot reached 43 states at the end of 2025, about 80% of personal auto premium excluding California. Each state that restricts variable use narrows the segmentation advantage rather than the market.
Reserves cutting the other way
Favorable development added 2.4 points to the H1 2026 combined ratio. If severity on open bodily injury claims outruns the assumptions, the same mechanism subtracts. Progressive would then be defending share with rate cuts while reported margin falls faster than the underlying number.
What the SWOT Adds Up To
Progressive won the last cycle on accuracy. It priced risk better than 230 competitors through the sharpest claim-inflation shock in decades and turned that into 2.8 million policies and a share position that ties or leads the largest personal auto market on earth.
The 2026 question sits elsewhere. Accuracy holds. Conversion changed, because rivals are back on the raters and matching more of Progressive’s quotes. Management’s answer is to spend the surplus it built: cut new-business rates across 63% of premium, raise advertising 16%, lift premium-to-surplus leverage to 3.5-to-1, and aim all of it at bundled households.
Two conditions have to hold for that to work. Property policy count has to move off zero, because the bundle needs a home product Progressive can sell in volume rather than one it sells at an outstanding margin. And the reserve cushion has to stay favorable, because 2.4 of the 9.1 points separating Progressive from its own 96 objective come from prior accident years rather than current pricing.
Meet both and Progressive converts a pricing advantage into a household relationship advantage, which is stickier and far harder to copy than a rating model. Miss either and the company is buying share with borrowed margin in a market that stopped paying for the purchase.
Frequently Asked Questions
Is Progressive the largest auto insurer in the United States? By the most recent published NAIC data, for data year 2025, State Farm still leads with 18.64% of private passenger auto premium against Progressive’s 18.60%, a difference of $158 million. Progressive management describes the company as the largest US personal auto writer, and S&P Global Market Intelligence shows Progressive ahead on a trailing-twelve-month basis through March 2026, though that calculation includes estimates for two Progressive subsidiaries that file no public quarterly statements. Treat the crossover as imminent rather than confirmed.
What is Progressive’s biggest strength? Rating granularity delivered on a schedule. Progressive ships numbered rating models the way software companies ship releases, moving from 8.9 to 9.0 to a 9.1 planned for early 2027. Each release narrows the price a rival can match and still profit, and the effect compounds against roughly 230 personal auto competitors.
Why did Progressive’s premium growth slow in 2026? Net written premium grew 5% in July 2026 against roughly 7% policy growth, so average premium per policy fell. Progressive cut new-business rates in 30 states representing 63% of countrywide premium during 2026. The company is trading price for volume by choice, funded by an underwriting margin running well ahead of its 96 objective.
What are Robinsons, and why do they matter to Progressive? Robinsons is Progressive’s internal name for consistently insured households that bundle home and auto. They represent roughly 35% of the US auto market, and Progressive’s share of them sits near 4%. About 85% of Robinsons auto premium sells through independent agents. Winning that segment is the company’s stated path to its next leg of growth, and the reason it spent four years rebuilding the property book.
Why does Snapshot not work in California? California’s rating regulation, 10 CCR 2632.5, requires three specific rating factors in weight order and permits a monitoring device only to verify actual mileage, while prohibiting collection of the insured vehicle’s location. Behavioral telematics cannot enter a California rate. California represents about 13% of the US private passenger auto market, so Progressive competes there without its signature tool and runs a separate California agency auto organization as a result.
How risky is Progressive’s reliance on reserve releases? Progressive released $1,002 million of favorable prior-year development in H1 2026, worth 2.4 combined ratio points on $42,541 million of earned premium. That accounts for about 26% of the distance between the reported 86.9 combined ratio and the 96 objective. Conservative reserving produces this outcome and Progressive has a long record of it. The exposure is that management reads a flattered margin as room to cut price.
What is the biggest threat to Progressive right now? Competitive convergence. The average number of carriers returning a quote on comparative raters has increased more than 30% since early 2024. Progressive’s pricing edge is intact and it converts into fewer sales per quote, because rivals restored to profitability are bidding again.
The BMA Take
Progressive is the best-run underwriter in US personal auto and this SWOT does not dent that. What it changes is the shape of the bet. For three years the company got paid for being right about loss trend while competitors were wrong. That trade is closing. The average quote sheet carries 30% more carriers than it did in early 2024, and Progressive is paying for share with rate cuts across 63% of its premium base, a 16% advertising increase, and a step up in balance-sheet leverage.
Spending a surplus is a reasonable use of a surplus, and Progressive’s own framework says as much: grow as fast as possible at a 96 combined ratio or better. The company sits at 86.9. The complication is that 2.4 of those points came from prior accident years, so the true operating cushion runs closer to 6.7 points than 9.1.
Watch two lines. Property policy count, parked at 3,635 thousand and flat, has to move, because the bundled-household strategy runs through a home product Progressive can sell at scale rather than one it sells at an excellent margin. And prior-year development has to stay favorable, because the moment it turns, the price giveback and the reported margin move against each other at once.
Who Progressive actually targets, how it names and prices its customer segments, and why the Robinsons pool resisted the company for so long is a separate question. We take it up in our breakdown of Progressive’s target market.
Sources: The Progressive Corporation FY2025 Annual Report and Form 10-K; Q1 2026 Form 10-Q; June 2026 monthly results release (Form 8-K, accession 0000080661-26-000262, July 15, 2026); July 2026 monthly results release, August 19, 2026; Q2 2026 investor relations event and earnings call, August 4, 2026; NAIC Property/Casualty Market Share Report, private passenger auto, data year 2025; California Department of Insurance 2025 market share data; 10 CCR 2632.5; Berkshire Hathaway FY2025 Form 10-K. Figures verified August 2026.


