
The largest US auto insurer just posted another profit beat. The problem: it makes money faster than it can find places to put it, and slowing growth is the reason why.
Progressive has spent two years winning. It out-priced the industry through the inflation shock, stole market share at a pace no rival could match, and this spring it ended State Farm’s 84-year run as America’s biggest auto insurer. The reward for all that winning is an awkward question most companies would kill for: what do you do when your business throws off more cash than it can reinvest? Progressive paid out a record $8 billion to shareholders for 2025 and is on track to do it again. But the size of that payout is not a victory lap. It is a symptom of an engine that has started to downshift.
What Happened
On July 15, Progressive reported second-quarter results that beat Wall Street estimates and, at the same time, confirmed the market’s biggest worry about the company. Net premiums earned rose 6% to $21.57 billion. Net income climbed 4% to $3.31 billion. Policies in force reached 40.1 million, up 7% from a year earlier. By almost any standard, a strong quarter.
The catch is the trajectory. That 6% premium growth is down from 18% in the same quarter of 2025. Policy growth of 7% is roughly half of last year’s 15% pace. Progressive is still expanding, but the rate of expansion has fallen off a cliff in twelve months.
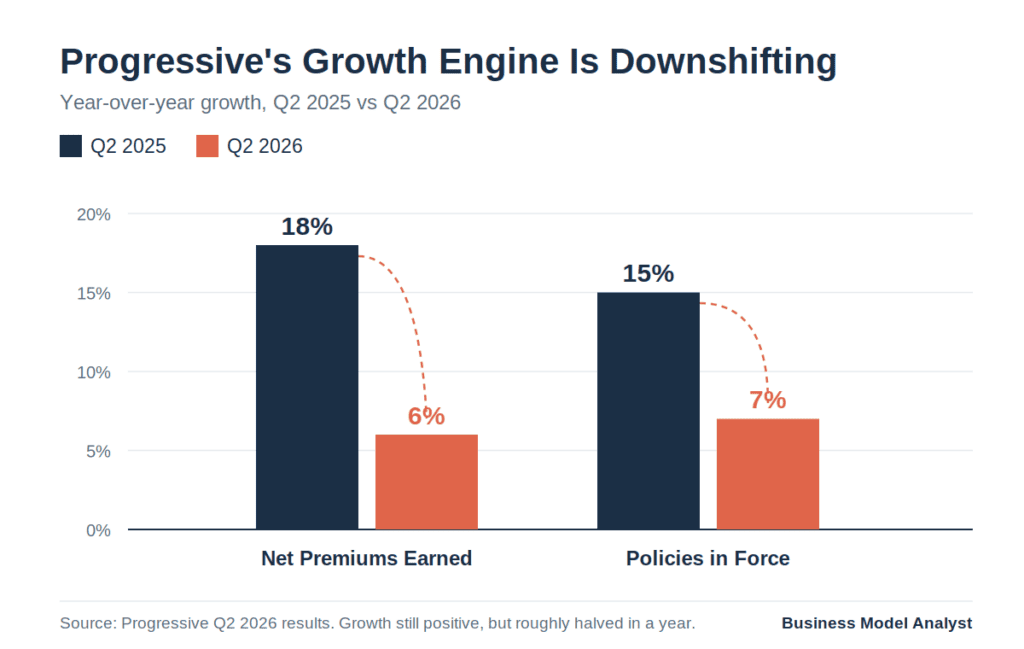
That deceleration has spooked investors. The stock closed at $207.95 on July 17, down about 15% from a year earlier, even as profitability held near record levels. Progressive’s combined ratio, the core measure of underwriting profit, came in at 87.3 for the quarter. Anything under 100 means the company earns money on the insurance itself before a dollar of investment income. Progressive’s own target is 96. It is beating its goal by nearly nine points, which is exactly the situation that leaves it swimming in capital it now struggles to deploy.
Wolfe Research estimates Progressive is sitting on roughly $13 billion in excess capital and will hand back about $6.6 billion in dividends and another $2.3 billion in buybacks. The buyback ramp is the tell. Progressive spent about $170 million repurchasing shares in June alone, up from roughly $4 million in June a year earlier.
The Backstory
To understand why the cash is piling up, you have to understand how Progressive got to the top in the first place.
For 84 years, State Farm was the biggest auto insurer in the country, a position it had held since 1942. In May, S&P Global Market Intelligence estimated that Progressive had overtaken it on a trailing-twelve-month basis, with roughly $70.2 billion in US private auto premiums against State Farm’s $68.7 billion. (The estimate required modeling two non-filing subsidiaries, so the two remain close, but the direction of travel is not in dispute.) The gap in momentum tells the whole story: over that stretch, Progressive’s personal auto premiums grew 11.6% while State Farm’s edged down 0.1%.
Progressive did not win by spending more on ads, though it certainly spends plenty. It won on pricing precision. When post-pandemic inflation sent repair and claims costs soaring, most insurers were caught flat-footed. Progressive, built for decades around data, analytics, and telematics tools like its Snapshot program, re-rated its policies faster and more accurately than almost anyone else. It pulled back hard in 2022 and 2023 when the math did not work, then pressed the accelerator once it did. That agility let it price competitively and profitably at the same moment rivals were still bleeding, and customers flowed in.
State Farm, a captive-agent giant, could not turn the wheel as quickly. That is not a knock on its brand. It is a structural difference in how the two companies are built, and it decided the race.
The Plan
Progressive’s approach to its cash mountain is deliberate and, by its own account, unchanged. The company treats capital return as the last stop, not the first. It looks at reinvesting in growth, then acquisitions, then buybacks, and whatever is left flows out as a variable annual dividend on top of its small fixed quarterly one.
That variable dividend is the mechanism that makes Progressive unusual. Most insurers return capital on a predictable schedule. Progressive lets the number float with performance, which is why the 2025 payout hit $8 billion, or $13.50 a share, three times the 2024 figure. When growth slows and margins stay wide, the variable dividend swells almost automatically. Wolfe expects a variable dividend near $11 a share this time around.
The company has leaned on organic growth over acquisitions and recently secured regulatory approval in key states to hold less capital against its auto policies, which freed up even more to return. Newly installed CFO Andrew Quigg has signaled no change in philosophy: stay disciplined, return the excess.
The Business Model Angle
Here is the part the financial press keeps missing. The $13 billion capital pile is not Progressive’s problem to solve. It is the receipt for a moat.
Insurance is one of the few business models where the product is priced before the cost of goods sold is known. You collect the premium today and find out years later what the claims actually cost. Win that bet consistently and two things happen. First, you underwrite at a profit, which is rare, and Progressive’s sub-88 combined ratio means it is earning money on the insurance itself, not just on investments. Second, you get to hold and invest the float, the pool of premium collected but not yet paid out, which throws off billions in investment income on top. Progressive is running both engines at once, and doing it while growing faster than the industry, a combination that almost never coexists.
That is what excess capital looks like on a balance sheet. It is not idle money. It is proof that the pricing machine is converting risk into profit faster than the business can absorb it back into new policies. A weaker insurer would love to have this problem, because a weaker insurer cannot generate it.
But the same machine reveals its own ceiling. Progressive’s edge came from re-pricing faster during a period of extreme dislocation. That period is ending. As the industry normalizes, the advantage of turning the wheel quickly shrinks, because there is less turning to do. And once you are the biggest player in the market, the law of large numbers takes over. You cannot keep stealing share at 15% a year when you already own the largest book in the country. The deceleration is not a stumble. It is the predictable maturing of a company that ran out of room to run. The capital returns are what a business does when the compounding slows and reinvestment opportunities dry up.
In other words, the $8 billion dividend and the growth slowdown are not two separate stories. They are the same story told from opposite ends.
The Risk
The bull case and the bear case rest on the same fact, which is why the stock is stuck.
Competition is heating up as rivals finally shake off the inflation distortions that hobbled them. The pricing tailwind that carried Progressive is reversing: the consumer price index for auto insurance actually fell 4.1% in June from a year earlier, down from a 6.1% rise the prior year and a 19.5% spike the year before that. Falling premiums across the industry mean less room for Progressive to grow the top line, and more pressure to compete on price rather than precision.
There is also the reinvestment trap that comes with maturity. Returning $9 billion a year to shareholders is fine when you genuinely have no better use for it. It becomes a warning sign if it signals that management sees no growth left to fund. Investors marking the stock down 15% are betting the latter. The risk is not that Progressive stops being profitable. It is that “past peak growth,” as one Wolfe analyst put it, becomes the permanent state, and a company priced for expansion has to be repriced as a cash cow.
For a business that spent two years defined by how fast it could move, the hardest adjustment may be learning to be big and slow instead of small and quick.
Quick Questions
Did Progressive really pass State Farm as the biggest auto insurer? On a trailing-twelve-month basis, yes, according to a May 2026 estimate from S&P Global Market Intelligence, ending State Farm’s run at number one that dated to 1942. The two remain close, and the estimate involved modeling subsidiaries that do not publicly file, but Progressive’s far faster growth made the crossover all but inevitable.
Why does Progressive have so much excess capital? Because it is highly profitable and its growth is slowing at the same time. Wide underwriting margins generate capital quickly, and when there are fewer new policies to reinvest in, that capital accumulates. Wolfe Research pegs the excess at roughly $13 billion.
What is a variable dividend? It is a dividend whose size changes year to year based on performance, paid on top of a fixed regular dividend. Progressive uses it to return whatever capital is left after reinvestment, acquisitions, and buybacks. That is why its 2025 payout tripled to $8 billion.
Why is the stock down if profits are strong? Investors care about growth, not just current profit. Premium growth fell from 18% to 6% and policy growth from 15% to 7% in a year. The market is repricing Progressive from a fast grower toward a slower, cash-returning mature business, and that shift pulled the shares down about 15%.
What made Progressive win in the first place? Pricing speed. Its data, analytics, and telematics let it re-rate policies faster and more accurately than competitors when inflation spiked claims costs, so it could grow profitably while rivals struggled. That agility, not marketing spend, drove the market-share gains.
The Business Model Analyst Take
Progressive is a case study in a truth founders rarely want to hear: the same advantage that makes you win eventually caps how much you can win. Its pricing engine was a scalpel in a market full of hammers, and for two years that precision translated directly into share, profit, and now a cash hoard so large the company cannot spend it fast enough. That is the good problem. The uncomfortable one is that a scalpel is most valuable when everyone else is confused, and the industry is getting less confused by the quarter.
The excess capital is not a sign of a company that has lost its way. It is a company that has arrived. The interesting question for anyone building a business is not “how do I get Progressive’s problem,” but “what happens to my model when I do?” Winning your market changes what your business is for. Progressive is discovering that the machine built to take share is not the same machine you need once you already own the market, and the $8 billion it is shoveling out the door is the sound of that transition happening in real time.
Reporting by Kristin Broughton for The Wall Street Journal, with additional data from S&P Global Market Intelligence, Wolfe Research, Progressive’s Q2 2026 results, and the Bureau of Labor Statistics.