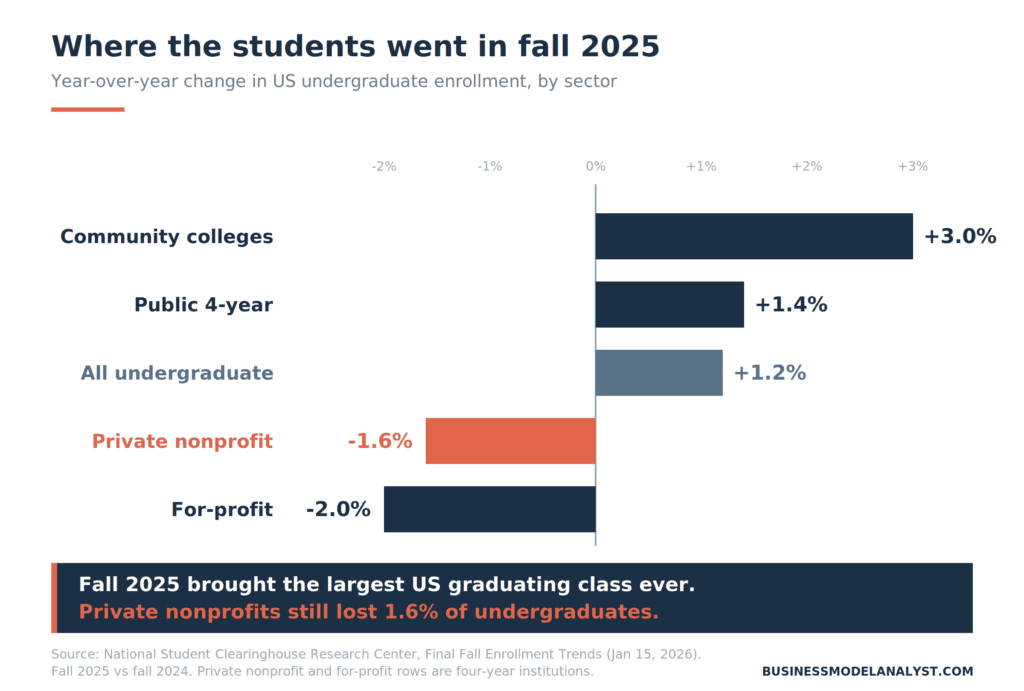
Fall 2025 delivered the largest high school graduating class in American history. Undergraduate enrollment at private nonprofit colleges fell 1.6% anyway. The demographic cliff is taking the blame for a problem that started with price.
Private nonprofit colleges now award 57.1 cents of institutional grant aid for every dollar of published freshman tuition, the deepest discount in the decade of records the sector keeps on itself. Net tuition revenue per undergraduate still fell 1.9% after inflation. Their undergraduate enrollment still dropped 1.6% in a year when total US postsecondary enrollment rose 1.0%. The discount stopped buying students, and no amount of demographic decline explains that, because the demographics were as good as they will ever get.
The nursing program that sold for $1.1 million
On Monday, lawyers for the Sisters of Saint Anne filed a notice in bankruptcy court proposing to sell the nursing program of Anna Maria College to Assumption University, a Catholic school ten miles away in Worcester, Massachusetts. Price: $1.1 million, with $110,000 held back against indemnifiable damages. The sale is scheduled for September 30 as a private, noncompetitive transaction.
Assumption was already receiving 75 of Anna Maria’s nursing students this fall. It did not pay for them. What it bought was curricular material, program documentation, and a faster path through the Massachusetts Board of Registration in Nursing for a nursing program it launched in 2020.
Anna Maria closed on May 10 after 80 years and filed Chapter 11 in late June. President Sean Ryan told the court that net tuition and fee revenue fell from $19.2 million in fiscal 2021 to $14.3 million in fiscal 2025 while total enrollment dropped 18% to 1,520 students. Four straight years of operating losses. Secured debt of $17.7 million against a campus the estate is now trying to sell.
Run the per-student arithmetic and the second leg shows up. An 18% enrollment decline off 1,520 implies roughly 1,854 students in fiscal 2021, so net revenue per student went from about $10,356 to about $9,408. Down 9% in nominal dollars over four years in which US consumer prices rose about a fifth. Anna Maria lost students and got less money from each one it kept. The $1.1 million recovered on the nursing program covers about 117 student-years of that fiscal 2025 net tuition, and 6% of the secured debt.
The National Association of Independent Colleges and Universities counts more than 1,700 private nonprofit institutions with a median four-year enrollment of 1,209 students. Anna Maria was bigger than half the sector.
What happened
The National Association of College and University Business Officers released its 2025 Tuition Discounting Study on June 1. Across 258 participating private nonprofits, the estimated discount rate for first-time, full-time undergraduates in 2025-26 reached 57.1%, up from a finalized 54.5% the prior year. For all undergraduates it hit 51.3%, up from 50.0%. Ninety percent of first-year students received institutional aid, the highest share since 2021-22.
The revenue line moved the other way. In the finalized 2024-25 data, average net tuition and fee revenue fell 1.9% after inflation per undergraduate and 2.2% per first-time, full-time undergraduate.
Enrollment moved the other way too, but only for one group. The National Student Clearinghouse Research Center’s final fall 2025 report counted 19.4 million postsecondary enrollments, up 1.0% and 187,000 students. Undergraduate enrollment rose 1.2%. Community colleges added 3.0%. Public four-year institutions added 1.4%. Private four-year nonprofits lost 1.6%, and four-year for-profits lost 2.0%. Spring 2026 repeated the pattern: total enrollment up 1.0%, community colleges up 3.1%, public four-years up 1.5%.
That happened in the year the Western Interstate Commission for Higher Education identified as the peak. WICHE’s eleventh edition of Knocking at the College Door puts the high school graduating class of 2025 at roughly 3.9 million, the largest on record, declining to about 3.4 million by 2041 for a 13% drop.
The backstory
Discounting is not a crisis response. It is the operating model, and it has been for thirty years.
A private nonprofit college publishes a tuition number, then negotiates almost every seat individually through institutional grant aid. Airlines do the same thing with fare classes. Hotels do it with rack rates. The published price exists to anchor the negotiation and to signal quality, and the aid letter sets the price each family pays.
The mechanics worked while the pool of 18-year-olds grew. Colleges could deepen the discount for price-sensitive students, hold near-sticker pricing for full-pay families, and grow net revenue on volume. College Board data shows how far the gap opened. Published tuition and fees at private nonprofit four-year institutions reached $45,000 in 2025-26, up 4.0% from $43,250. Average net tuition and fees paid by first-time, full-time students at those same institutions: $16,910 in 2025 dollars, down from $19,810 in 2006-07. The list price climbed for two decades while the realized price fell 14.6% in real terms.
The competing product cut harder. Net tuition and fees at public four-year institutions for in-state students now average $2,300, down 48.3% in real terms from the 2012-13 peak of $4,450. Average grant aid has covered community college tuition and fees outright since fall 2009. Institutional grant aid rose from 23% of all undergraduate aid a decade ago to 33% of $205.2 billion in 2024-25.
Two decades of price war, and the private sector’s cuts were half as deep as the public sector’s.
The plan
Colleges are pulling four levers, and only one of them is new.
Discount further. The 2.6-point increase in the first-year discount rate is the sector’s main answer to a shrinking pool. Moody’s expects fierce competition for students as the market contracts.
Cut the cost base. The University of Nebraska board approved cutting low-enrollment programs in July. Minnesota State Mankato is running layoffs and a tuition increase against a $22 million shortfall. Syracuse is working through a budget deficit.
Shorten the product. Virginia and Ohio joined the effort to design three-year bachelor’s degrees in June, following the same logic a manufacturer uses when it takes cost out of a package rather than raising the price. Two higher education groups called the result a stripped-down curriculum.
Buy capacity instead of building it. Assumption paid $1.1 million for an accredited nursing program’s paperwork. Curry College acquired Labouré College’s nursing programs before Labouré closes at the end of this month. Westcliff University bought Pacific College to expand nursing. In a shrinking market, the acquirable asset is regulatory permission to teach a growing subject.
The business model angle
Three things are worth pulling out for anyone running a business with a published price and a private one.
A discount rate is a price, and it compounds against you. Going from a 54.5% discount to 57.1% means the retained share of each published tuition dollar falls from 45.5 cents to 42.9 cents. Holding net revenue per student flat requires a 6.1% increase in the published price. Private nonprofits raised published tuition 4.0%. They underpriced their own discount by about two points before a single student changed their mind, and NACUBO’s panel is not the same panel College Board surveys, so treat the two-point gap as direction rather than a decimal. Direction is enough: the sector took a price cut it did not fund and then lost volume on top of it.
When the substitute is nearly free, deeper discounting is a losing move. A private college cutting from $19,000 net to $16,910 net is competing against a public alternative at $2,300 and a community college at zero. Each additional point of discount costs real money and closes almost none of that gap. The lever the sector keeps pulling has almost no travel left in it, which is why fall 2025 produced record discounting and negative volume in the same year.
Fixed costs turn a mix shift into a solvency event. Moody’s studied its rated colleges with acceptance rates of 60% or higher and enrollments under 3,000, and found tuition and auxiliary revenue supplying an average 71% of their budgets in fiscal 2023. Faculty contracts, buildings, and accreditation do not resize with the freshman class. Moody’s projects sector revenue growing 3.5% against expenses growing 4.4% in fiscal 2026, with small privates at 2.7% revenue growth and mid-sized privates at 2.3%. The agency expects 16% of private institutions to run negative operating margins in 2026, against an estimated 12.2% in 2025 and 7.2% in 2024.
Students are also repricing the product by subject, not only by institution. Computer and information sciences enrollment fell 8.4% at four-year institutions and 11.2% at two-year institutions in spring 2026. Health professions grew for a third straight year and passed two million undergraduates. Buyers who watch the payoff on a degree that closely are not going to be persuaded by a bigger scholarship letter.
The risk
The bear case here has real holes, and three of them deserve stating.
Enrollment is growing. Three consecutive years of undergraduate gains sit awkwardly beside any story about collapsing demand, and the growth is real even if it is landing at community colleges. A sector that adds 187,000 students in a year is not disappearing.
Colleges are extraordinarily hard to kill. Sixteen nonprofit colleges closed in 2025 out of more than 1,700, under 1% of the sector. Roughly 48 public and private nonprofit institutions have closed or announced closures since March 2020. A 2016 study of nearly 500 private nonprofits identified as resource-limited in 1972 found about 85% still operating four decades later. The Philadelphia Fed’s 2024 model puts closures at up to 80 a year only under worst-case enrollment assumptions.
The 13% decline is also slower than the word “cliff” suggests, and it is not evenly distributed. WICHE’s Patrick Lane has warned against institutions planning off the national figure. Hawaii faces roughly a 33% decline through 2041. Washington, D.C., is projected to gain 31%. South Carolina, Tennessee, Idaho, and North Dakota grow. A college in Nashville and a college in Buffalo are reading two different documents.
One caution on the headline number itself. NACUBO’s 57.1% is a preliminary estimate, and last year’s preliminary estimate of 56.3% for 2024-25 was finalized at 54.5%, a 1.8-point revision downward. The participating panel has shrunk from 341 institutions three studies ago to 286 to 258, and participation is voluntary. The direction of the discount is not in doubt. The level probably lands a point or two below the press release.
Quick questions
Is the enrollment cliff already here? The decline in high school graduates starts with the class of 2026. The revenue effect at private nonprofits arrived earlier, showing up as a 1.6% undergraduate enrollment decline in fall 2025 against a 1.0% national increase.
Why do colleges keep raising the sticker price if nobody pays it? The published price sets the ceiling for price discrimination and signals quality. Raising it also funds the discount, which is why a 4.0% increase against a 2.6-point discount increase leaves the institution short.
Does discounting mean college is getting cheaper? For families, yes. Average net tuition and fees at private nonprofits have fallen 14.6% in real terms since 2006-07, and at public four-year institutions 48.3% since 2012-13. The affordability gain and the institutional revenue problem are the same number read from opposite sides.
Which colleges are most exposed? Small, tuition-dependent private nonprofits with acceptance rates above 60%, enrollment under 3,000, and thin endowments, concentrated in the Midwest and Northeast where the graduate decline started first.
What does a closing college sell for? Anna Maria’s nursing program went for $1.1 million against $17.7 million of secured debt. Real estate is the meaningful asset. Programs, curriculum, and accreditation fetch less than one year of net tuition from a hundred students.
The Business Model Analyst take
The Wall Street Journal illustrated its enrollment cliff item with a chart of Ivy League acceptance rates falling since 2006. Those eight schools are the least exposed institutions in American higher education. Their acceptance rates fall because demand exceeds supply by a wider margin every year, which is the exact opposite of the problem killing colleges in Massachusetts. Charting the cliff with the Ivies is like measuring a grocery price shock at a Michelin restaurant.
The lesson generalizes past higher education. If your business runs a published price that almost nobody pays, the discount is not a marketing expense. It is your actual price, and the published number is a story you tell about it. You can keep telling the story while the pool of buyers grows, because volume covers the gap between what you say you charge and what you collect. When the pool stops growing, the only honest number left is net revenue per unit, and the discount that used to buy growth starts buying nothing.
Private colleges spent twenty years cutting their real price by 14.6% while a state-funded competitor cut its own by 48.3% and a community college competitor went to zero. That race was decided before any of the demographics mattered. What arrives in 2026 will not cause the problem. It will remove the last thing that was hiding it.
If you are pricing anything with a list price and a negotiated price, run this test on your own numbers this quarter: hold your discount rate flat, and see how much of last year’s growth survives. If most of it disappears, you were not growing. You were buying volume, and you should find out what it costs before your buyers get scarce.