
The American Dream used to have a rough price tag: a steady job, a house with a yard, two kids, a car in the driveway. In 2026, that picture is still recognizable. What has changed is the number underneath it.
Run the math on that classic dream today, a family of four that owns their home, raises two children, keeps two cars on the road, insures everyone and puts something aside, and the income it demands has crossed a line that would have sounded absurd a decade ago. In every one of the 50 states, the American Dream now requires a six-figure household income. The floor sits at roughly $134,000 in West Virginia. The ceiling reaches about $273,000 in Hawaii. The typical state lands near $166,000.
Set that against what families actually earn and the story sharpens into something uncomfortable. There is no state, not one, where the median household income is enough to buy the full dream outright. The gap runs from 1.9 times the local median in the friendliest states to 2.8 times in the least forgiving. The dream is not gone. It has simply repriced itself above the middle of the middle class.
What “the price of the American Dream” actually means
The 2026 American Dream cost The annual household income a family needs to comfortably afford the traditional package of American middle-class life in a given state: owning a typical home, raising two children, running two vehicles, carrying health insurance, covering everyday essentials, and still funding savings and a little discretionary spending. We express it as the gross income required, then compare it to what households in that state actually earn.
This is not a survival budget. It is the “comfortable” version of the dream, the one that includes retirement contributions and a family vacation rather than just keeping the lights on. That framing matters, because it is the difference between what it costs to get by and what it costs to arrive.
How we built the 2026 numbers
Every figure here is reproducible from public data. The model works the same way for all 50 states, so the ranking is a fair fight.
- Housing is the annual mortgage on a typical home, using each state’s Zillow Home Value Index, a 20 percent down payment, and the Freddie Mac 30-year fixed rate of 6.43 percent as of early July 2026. Property tax is layered on top using each state’s effective rate.
- Non-housing needs cover childcare for two children, groceries for a family of four, health insurance and out-of-pocket care, two vehicles, utilities and household costs, and one pet. These are set at a national baseline and scaled by each state’s cost of living.
- Income needed applies the standard 50/30/20 rule: necessities should not exceed half of gross income. So the total annual cost of the dream is doubled to find the salary that carries it comfortably.
- The gap divides the income the dream requires by the actual median household income for that state (U.S. Census, 2024).
One honest caveat on the biggest swing factor. Childcare for two children is the single most volatile line in any calculation like this, and reasonable people model it differently. We use a blended national baseline rather than assuming both children sit in full-time center care for years on end, which keeps the estimate on the conservative side. Nudge that assumption up and every number below rises with it.
The full ranking: what the American Dream costs in all 50 states
Ranked from the most expensive dream to the most affordable, here is the income a family needs in 2026, and how far that sits above the local median.
| Rank | State | Typical home value | Income needed for the dream | Median household income | Dream-to-income gap |
|---|---|---|---|---|---|
| 1 | Hawaii | $974,000 | $273,000 | $99,000 | 2.76x |
| 2 | California | $809,000 | $246,000 | $98,000 | 2.50x |
| 3 | Massachusetts | $686,000 | $231,000 | $103,000 | 2.24x |
| 4 | New Jersey | $589,000 | $226,000 | $104,000 | 2.18x |
| 5 | Washington | $627,000 | $215,000 | $97,000 | 2.21x |
| 6 | New Hampshire | $528,000 | $209,000 | $98,000 | 2.14x |
| 7 | New York | $488,000 | $206,000 | $83,000 | 2.48x |
| 8 | Rhode Island | $507,000 | $202,000 | $86,000 | 2.35x |
| 9 | Connecticut | $466,000 | $202,000 | $94,000 | 2.15x |
| 10 | Oregon | $515,000 | $200,000 | $81,000 | 2.47x |
| 11 | Colorado | $568,000 | $197,000 | $95,000 | 2.08x |
| 12 | Alaska | $395,000 | $194,000 | $90,000 | 2.16x |
| 13 | Vermont | $407,000 | $190,000 | $81,000 | 2.35x |
| 14 | Utah | $547,000 | $189,000 | $93,000 | 2.03x |
| 15 | Maryland | $451,000 | $189,000 | $102,000 | 1.86x |
| 16 | Maine | $414,000 | $186,000 | $74,000 | 2.52x |
| 17 | Nevada | $472,000 | $184,000 | $76,000 | 2.42x |
| 18 | Montana | $467,000 | $183,000 | $73,000 | 2.52x |
| 19 | Idaho | $465,000 | $179,000 | $75,000 | 2.41x |
| 20 | Arizona | $440,000 | $179,000 | $77,000 | 2.32x |
| 21 | Virginia | $417,000 | $177,000 | $91,000 | 1.93x |
| 22 | Florida | $405,000 | $176,000 | $73,000 | 2.40x |
| 23 | Delaware | $406,000 | $172,000 | $84,000 | 2.05x |
| 24 | Minnesota | $358,000 | $171,000 | $90,000 | 1.90x |
| 25 | Wisconsin | $335,000 | $167,000 | $77,000 | 2.15x |
| 26 | Wyoming | $367,000 | $166,000 | $75,000 | 2.22x |
| 27 | Illinois | $292,000 | $165,000 | $81,000 | 2.03x |
| 28 | Texas | $308,000 | $164,000 | $76,000 | 2.14x |
| 29 | South Dakota | $321,000 | $162,000 | $72,000 | 2.25x |
| 30 | Pennsylvania | $286,000 | $161,000 | $76,000 | 2.12x |
| 31 | North Carolina | $339,000 | $161,000 | $71,000 | 2.28x |
| 32 | Georgia | $339,000 | $161,000 | $77,000 | 2.10x |
| 33 | Tennessee | $336,000 | $158,000 | $69,000 | 2.27x |
| 34 | New Mexico | $317,000 | $157,000 | $63,000 | 2.51x |
| 35 | North Dakota | $290,000 | $157,000 | $79,000 | 1.99x |
| 36 | Nebraska | $277,000 | $156,000 | $77,000 | 2.04x |
| 37 | South Carolina | $307,000 | $154,000 | $68,000 | 2.27x |
| 38 | Michigan | $260,000 | $153,000 | $71,000 | 2.16x |
| 39 | Ohio | $246,000 | $151,000 | $70,000 | 2.15x |
| 40 | Missouri | $265,000 | $148,000 | $71,000 | 2.09x |
| 41 | Iowa | $237,000 | $148,000 | $75,000 | 1.98x |
| 42 | Indiana | $255,000 | $148,000 | $71,000 | 2.07x |
| 43 | Kansas | $243,000 | $147,000 | $74,000 | 1.98x |
| 44 | Kentucky | $225,000 | $142,000 | $63,000 | 2.28x |
| 45 | Louisiana | $213,000 | $142,000 | $60,000 | 2.36x |
| 46 | Alabama | $232,000 | $141,000 | $62,000 | 2.27x |
| 47 | Oklahoma | $219,000 | $140,000 | $64,000 | 2.21x |
| 48 | Arkansas | $220,000 | $138,000 | $59,000 | 2.36x |
| 49 | Mississippi | $190,000 | $135,000 | $57,000 | 2.37x |
| 50 | West Virginia | $170,000 | $134,000 | $58,000 | 2.31x |
The most expensive states: where the dream costs a small fortune
The top of the table is a coastline. Hawaii, California, Massachusetts, New Jersey and Washington lead, and the common thread is not lifestyle or luxury. It is the price of a roof.
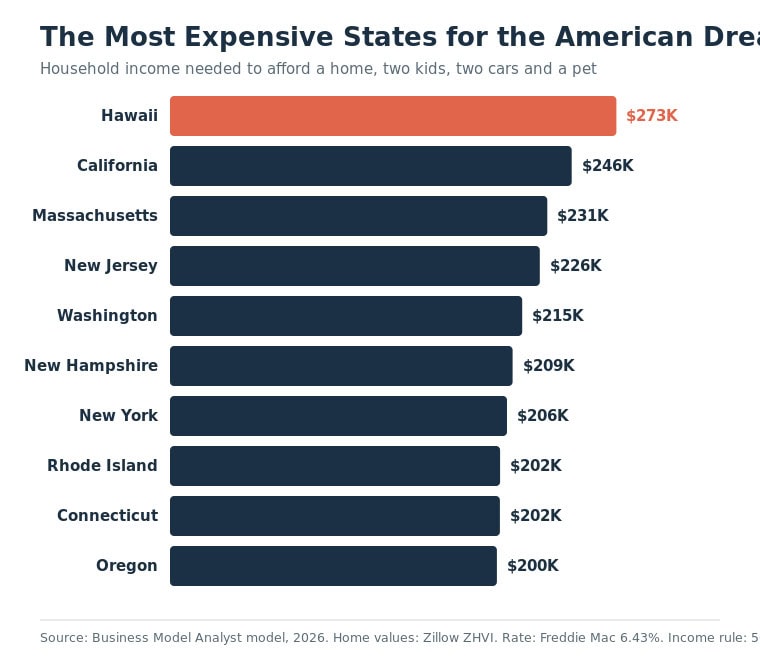
Hawaii is in a category of its own. The mortgage on a typical Hawaiian home runs about $59,000 a year before a single other bill arrives, which is more than the entire non-housing budget of a family in most of the country. That one line is why the dream in Hawaii costs $273,000, nearly $30,000 more than second-place California.
New Jersey is the instructive one. Its homes are not the most expensive in the country, yet it ranks fourth. The reason is property tax. New Jersey homeowners pay roughly $13,000 a year in property taxes on that typical home, the highest in the nation, and that single cost vaults the state ahead of markets with pricier houses. The lesson repeats across the ranking: the sticker price of a home is only half of what ownership actually costs.
The most affordable states: where six figures still buys the dream
At the other end, the dream gets a lot cheaper, but it never gets cheap. The five most affordable states cluster in Appalachia and the Deep South, and even there the entry price is six figures.
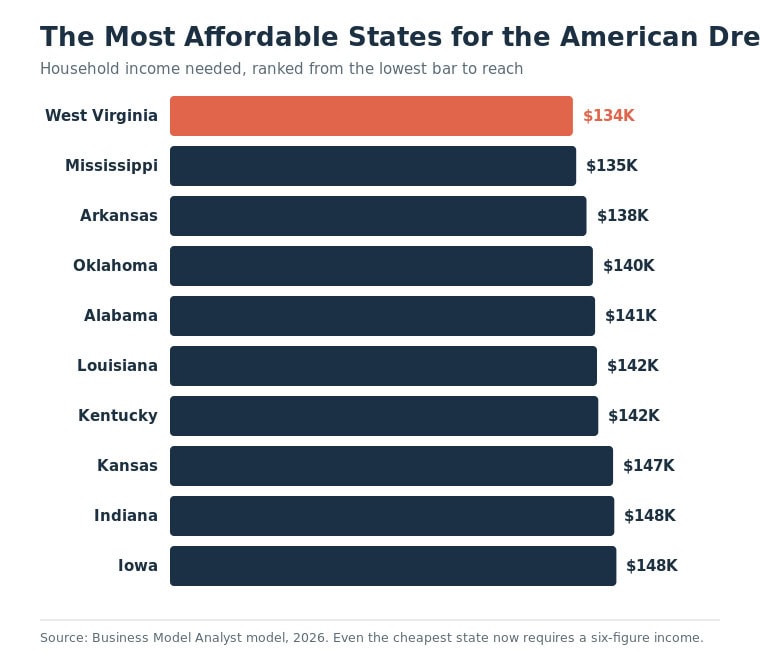
West Virginia is the most affordable state in the country for the American Dream, and it still asks for about $134,000 in household income. Mississippi, Arkansas, Oklahoma and Alabama round out the bottom five, all under $142,000. These are the places where a typical home costs less than $232,000 and property taxes stay modest, so housing stops dominating the budget the way it does on the coasts.
The distance from cheapest to most expensive is stark. The gap between West Virginia and Hawaii is about $139,000 a year in required income, and almost all of it traces back to home prices. Move the family, keep everything else identical, and the dream can nearly triple in cost.
The affordability gap: the number that matters most
Here is where raw cost rankings mislead. A state can have a modest dream price and still be brutally hard to reach if local incomes are low. The truer measure is the gap: how far the required income sits above what households actually earn.
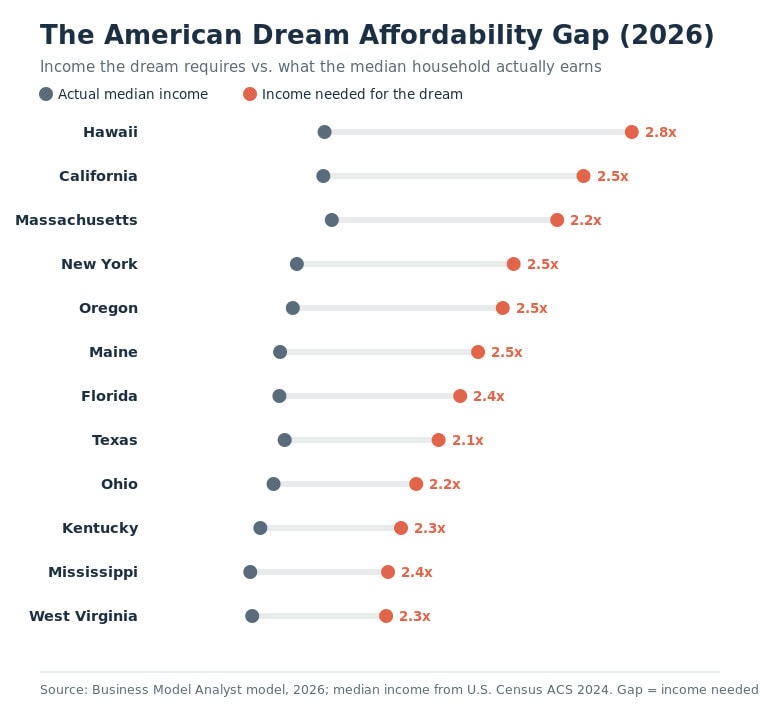
The finding is blunt. In no state does the median household earn enough to afford the full American Dream. The most attainable state in the country is Maryland, and even there the dream costs 1.86 times the median income. The least attainable is Hawaii at 2.76 times, followed by Maine, Montana, New Mexico and California, all near or above 2.5 times.
This reframes the whole map. The genuinely attainable states are not the cheapest ones. They are the ones where incomes have kept pace with costs. Maryland, Minnesota, Virginia, Iowa, Kansas and North Dakota all land near or below a 2.0 gap, because they pair moderate housing with strong household earnings. Meanwhile several “cheap” states in the Deep South carry gaps above 2.3, because low home prices sit on top of even lower incomes. Affordable and attainable are not the same thing, and this is the distinction most cost-of-the-dream rankings miss entirely.
Where the money actually goes
Strip the dream down to its parts and you can see why it costs what it does. In a typical state, the full dream runs about $166,000 in required income, and only half of that is pure necessity. The other half is what turns a survival budget into a “dream”: retirement savings and some room to actually live.

Two lines dominate the necessities half: the mortgage and childcare. In most states these two costs alone rival everything else combined. That is the quiet engine of the affordability squeeze. Housing has gotten more expensive because of prices and rates, and childcare has climbed independently, and a family absorbs both at the same stage of life, usually in their thirties, usually while their careers are still building. For a fuller picture of the household spending baseline behind all this, our breakdown of living off dividends in 2026 pegs average annual U.S. household spending at about $78,535, which lines up closely with the necessities half of the dream modeled here.
The regional map of the dream
Three patterns organize the whole ranking:
The coastal premium is real and it is almost entirely a housing story. The Pacific and Northeast coasts hold nearly every spot in the top ten, driven by home values that run two to five times those in the interior. Nothing else in the budget varies enough to explain the spread.
The property-tax reshuffle scrambles the map. States with cheaper homes but aggressive property taxes punch above their price. New Jersey, Illinois and Texas all sit higher in the cost ranking than their home prices alone would predict. Texas is the cleanest example: its typical home costs about $308,000, cheaper than 18 other states, yet its no-income-tax reputation hides a property-tax bill near $5,000 a year that keeps the dream at $164,000.
The income-lag belt is the one that stings. Parts of the Deep South and Mountain West look affordable on the home-price column but carry some of the widest gaps, because paychecks there have not kept up. This is where the dream is technically cheap and practically distant, and it is a big part of why “just move somewhere cheaper” is weaker advice than it sounds.
Is the American Dream still attainable?
Yes, but the definition of who can reach it has narrowed. In 2025, studies were noting that $100,000 no longer covered the dream in any major city. In 2026, the floor has moved again: not a single state comes in under $130,000, and the typical state now sits near $166,000.
The households actually reaching the full dream are increasingly dual high earners, or families who bought their homes years ago at lower prices and lower rates and are now insulated from today’s market. For everyone starting fresh, the path runs through the income side of the equation as much as the cost side. Which is why the honest companion question to “what does the dream cost” is “how do you earn enough to afford it,” and why routes like the highest-paying entry-level jobs for 2026 and hard-nosed thinking about education return on investment by major matter more than they used to.
Frequently asked questions
What is the cheapest state to afford the American Dream in 2026? West Virginia, at roughly $134,000 in required household income. Mississippi and Arkansas are close behind. Even so, the dream costs more than double the median income in each of them.
What is the most expensive state? Hawaii, at about $273,000, driven almost entirely by home prices. California is second at roughly $246,000, and Massachusetts third at about $231,000.
Why does the American Dream require six figures everywhere now? Two forces stacked on top of each other. Home prices remain near record highs while mortgage rates sit above 6 percent, and childcare and health costs have climbed on their own track. Because the model requires necessities to stay under half of income, those elevated costs get effectively doubled to find the salary that carries them comfortably.
Does a low home price make a state affordable? Not by itself. Property taxes can erase the advantage, as in New Jersey, Illinois and Texas, and low local incomes can make a cheap-looking state hard to actually reach, as across much of the Deep South. The affordability gap, income needed versus income earned, is the better guide than the sticker price of the dream.
Which states are genuinely the most attainable? The ones where incomes keep pace with costs: Maryland, Minnesota, Virginia, Iowa, Kansas and North Dakota all show the smallest gaps between the dream’s price and what households earn.
The Business Model Analyst Take
The American Dream did not disappear. It got repriced, and the repricing tells you something specific about the U.S. economy in 2026.
The story every headline reaches for is the coastal one, the $273,000 dream in Hawaii, the $246,000 dream in California. That is the eye-catching number, but it is the least interesting finding, because it is almost pure housing and everyone already knows the coasts are expensive. The real signal is in two places most rankings skip.
First, the necessities half of the dream is now dominated by two costs, the mortgage and childcare, that both land on the same household at the same moment in life. That is a structural squeeze, not a lifestyle problem, and it explains why two-earner families who feel like they are doing everything right still feel underwater. Second, and more important, is the gap. There is no state where the median household earns enough to buy the full dream, and the most attainable states are not the cheap ones, they are the ones where wages kept up. That distinction, affordable versus attainable, is the whole game. It is why relocation advice built purely on home prices tends to disappoint, and why the income side of the ledger deserves at least as much attention as the cost side.
For anyone building around this reality, whether that is a household planning a move or a business selling to the American middle class, the operative fact is that the middle of the market has been priced out of its own aspiration. The dream is now an upper-middle-class product. Whoever figures out how to profitably serve the households sitting in that 1.9-to-2.8 times gap, the ones who want the dream and earn most but not all of the way to it, is looking at the defining consumer opportunity of the decade.