
Net sales rose 3% in fiscal 2026, and most of that was currency. Organic volume contributed nothing. Now a $1 billion cost bill lands in 2027.
Procter & Gamble closed fiscal 2026 with $87.0 billion in net sales, up 3%. Two of those points came from foreign exchange and one came from higher prices. Volume and mix contributed nothing across the full year. In the June quarter, organic sales were flat, with volume, pricing and mix all landing at zero. Between fiscal 2023 and fiscal 2026, pricing supplied 13 points of organic growth. Volume supplied a net zero. The pricing lever that carried P&G through the inflation years has stopped moving, and management now expects an 8% earnings drag in fiscal 2027 from commodity, energy and transport costs.
CFO Andre Schulten gave an interview to The Wall Street Journal the morning P&G reported, and described the American shopper as “muted, but stable.” He is right, and that phrasing does a lot of work. A muted, stable consumer is one who keeps buying the same amount of Tide at a slightly higher price. For four years, that was enough. The June quarter is where it stopped being enough.
What Happened
P&G reported fourth quarter net sales of $21.2 billion, up 2%, with foreign exchange and rounding each supplying a point. Volume, pricing and mix had a neutral impact on sales growth for the quarter, and organic sales were unchanged versus the prior year. Diluted earnings per share fell 15% to $1.26. Core EPS fell 3% to $1.43, and on a currency-neutral basis core EPS dropped 5%.
The full year looks steadier only because currency flattered it. Net sales of $87.0 billion rose 3%, built from a two-point foreign exchange benefit and a one-point pricing benefit, with volume and mix unchanged. Organic sales rose 1%, entirely from higher pricing. Core EPS reached $6.89, up 1%, and currency-neutral core EPS finished flat.
Across the whole of fiscal 2026, P&G posted volume growth in a single quarter. In the June quarter, only two segments moved units. Beauty grew volume 3%. Fabric and home care, the division that houses Tide and Swiffer, managed 1%.
CEO Shailesh Jejurikar framed the year around a “challenging geopolitical and economic environment.” The company also said he adds the board chairmanship on August 1.
The Backstory
Look at where P&G’s growth has come from since 2022 and the June quarter stops being a blip.
In fiscal 2023, organic sales rose 7%, with pricing contributing seven points and shipment volumes subtracting one. Fiscal 2024 delivered 4% organic growth, all four points from pricing, with volume and mix flat. Fiscal 2025 slowed to 2%, split evenly between price and volume. Fiscal 2026 came in at 1%, again all pricing.
Add the pricing column across those four years and you get 13 points. Add the volume column and you get roughly nothing.
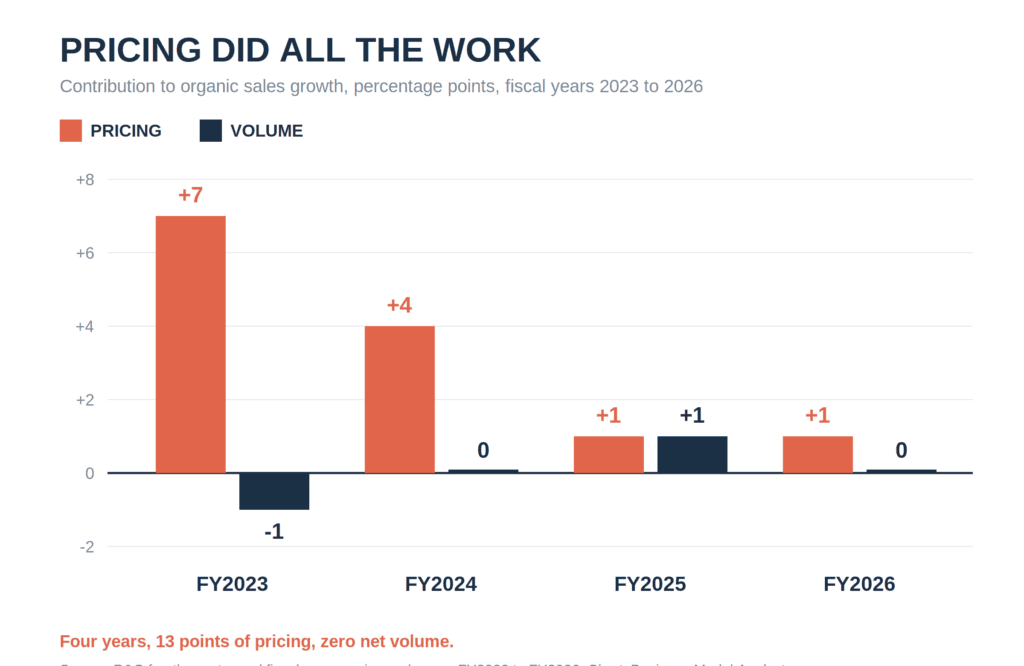
That is a company holding its unit base steady while raising the check size. It works while shoppers absorb the increases. It stops working the moment they trade down, and P&G’s own guidance says the increases are now colliding with a cost shock rather than an inflation window it can pass along.
The Plan
Management guided fiscal 2027 to all-in sales growth of 1% to 3% and organic growth of 1% to 3%, with 30 to 50 basis points of that eaten by brand, product form and go-to-market discontinuations. Core EPS lands in a range of $6.89 to $7.11, a midpoint of $7.00, or growth of about 1.5%.
Underneath that guidance sits a stack of costs. P&G expects roughly $1 billion after tax from higher raw materials, energy and transportation, another $150 million from net interest expense, $150 million from lower non-operating income and $50 million from unfavorable currency. Combined, that is $0.56 per share, an 8% drag on core EPS growth. Schulten has tied the raw material line to oil, and the guidance assumes a barrel around $90.
The offset comes from cost. The portfolio and productivity plan announced in June 2025 removes up to 7,000 non-manufacturing roles by the end of fiscal 2027 and carries $1 billion to $1.6 billion of before-tax restructuring charges, over half of which P&G booked in fiscal 2026.
On pricing, the company has signalled it will avoid a portfolio-wide increase and concentrate rises on premium products. In China, where P&G grew share for the first time in 15 quarters against a market still running below flat, Schulten credits a distributor replacement programme, tighter geographic focus, a slimmer brand lineup and a media model rebuilt around social content.
The Business Model Angle
P&G’s model has one load-bearing assumption: shoppers will pay a premium over the store brand because the product performs better. The company calls it superiority across product, packaging, communication, retail execution and value. Everything else, the R&D budget, the advertising scale, the shelf negotiation, exists to defend that premium.
Price discrimination is how P&G harvests it. Not through the shelf price, which is visible and politically loaded, but through pack architecture. Schulten described two shoppers to the WSJ. The one with cash trades up to bigger packs, which lowers price per wash and raises basket value at the same time. The one living paycheck to paycheck buys the small pack, which raises price per wash while lowering the cash outlay at the till, and keeps a Tide bottle in the cart instead of a Great Value one.
Same brand, two price ladders, sorted by how much cash the shopper has on the day. That is P&G running a K-shaped consumer through a single supply chain.
The catch is what that costs to operate. More pack sizes means more manufacturing changeovers, more inventory complexity, more SKUs to argue for at shelf. P&G is scaling that complexity in the same fiscal year it strips out 7,000 overhead roles and books restructuring charges to fund the productivity programme. Those two projects pull in opposite directions, and the guidance assumes both land.
The second change is quieter and probably more durable. P&G built modern brand management on bought reach: enormous, fixed advertising spend that only the largest advertiser could afford, which then locked out challengers. Rebuilding the China media model around social and creator content swaps that fixed cost for a variable, faster-cycle one. It is cheaper. It also erodes the moat, because a DTC upstart can buy the same creators. If China becomes the template, P&G trades a structural advantage for a cost saving. Worth watching in the fiscal 2027 numbers.
The Risk
Retailers own the trade-down. Every mechanism P&G uses to capture the value-seeking shopper, Walmart, Amazon and Costco can run with a better cost base and no advertising budget. Kirkland Signature does not need to defend a premium.
The oil assumption is the guidance. P&G’s inputs are largely petrochemical derivatives, so the $1 billion figure moves with Brent. A barrel meaningfully above $90 forces a choice between margin and another price increase, aimed at a consumer who already stopped buying more units.
The productivity maths is tight. Carrying an 8% headwind while guiding to 1.5% core EPS growth means the cost programme has to deliver roughly ten points of offset. A shortfall puts pressure on a company with 69 consecutive years of dividend increases behind it.
The counter-read, which deserves a hearing. Flat volume in a market that is itself flat is share defence, not decline. One percent organic growth on $87 billion is still close to $900 million of incremental revenue, and P&G generated $19.6 billion of operating cash flow in fiscal 2026, which funds the dividend and the buyback whether or not units grow. Pack-price architecture is also not a crisis response; P&G has run tiered pricing for decades, and its scale lets it manufacture at twelve pack sizes where a private-label supplier cannot. The bear case is not that P&G breaks. It is that the growth algorithm the stock is priced on no longer has a working engine.
Quick Questions
Did P&G’s sales actually grow? Reported net sales rose 3% for fiscal 2026. Strip out currency and acquisitions and organic sales rose 1%, all of it from pricing. In the June quarter, organic sales were flat.
How much of the four-year growth came from price? Pricing contributed 13 percentage points of organic growth between fiscal 2023 and fiscal 2026. Volume contributed a net zero.
What is the $1 billion headwind? An after-tax estimate for fiscal 2027 covering raw materials, energy and transportation, assuming oil near $90 a barrel. With interest, non-operating income and currency, the total drag is $0.56 per share, or 8% of core EPS growth.
Is China finally working? P&G grew share there for the first time in 15 quarters, though the market itself is still running below flat. The turnaround came from replacing distributors, narrowing geographic focus, cutting brands and shifting media spend toward social.
Who benefits if P&G keeps pricing? Private label and retailer store brands, plus the mid-tier challengers listed among P&G’s main competitors.
The Business Model Analyst Take
P&G spent four years proving that a portfolio of daily-use brands can convert inflation into revenue. That was a real achievement and the numbers back it. The trouble is that it taught the organisation the wrong lesson. Pricing power is a windfall, not an engine, and P&G ran it as an engine until the fuel ran out in the June quarter.
Zero volume, zero price, zero mix in a single quarter is not a demand problem the company can fix with better advertising. It marks the point where the premium hit the ceiling of what the bottom half of the consumer base will pay. Pack architecture buys time by letting P&G charge two prices for the same detergent. It does not create a new unit of demand; it re-sorts the ones already there.
The interesting number in fiscal 2027 will not be organic sales. It will be volume by segment. If beauty and fabric care keep moving units while the rest sit flat, P&G is a premium business with a value-tier problem, and the Gillette playbook of defending a shrinking premium against cheaper competition is the closest map it has. If volume goes negative while prices hold, the productivity programme becomes the whole story, and cost-cutting has never been a growth algorithm.
Schulten told the WSJ that P&G has to earn its value every day now. The candour is welcome. The business model question is whether a company built to charge a premium can win a fight where the prize is being the affordable option.