
Temu’s owner reported a 12% profit drop that the market read as heavy spending. The spending barely moved. The line that prints the margin did.
PDD Holdings reported second-quarter revenue of RMB112.36 billion, up 8.1%, and net profit of RMB27.18 billion, down 12% but well ahead of the RMB24.40 billion analysts had modelled. Underneath that headline, transaction services grew 13% while online marketing services, the advertising line that built the company, grew about 3.8%. Sales and marketing spending held at roughly 26% of revenue and adjusted operating profit rose 5%. The profit fell somewhere other than the subsidy budget.
Every wire story on PDD for the past two years has run the same sentence: profit is falling because the company is spending to defend its merchants. PDD encourages the reading. Its finance chief said again on Monday that the company stepped up ecosystem investments during the quarter. The number underneath that sentence moved by a quarter of a percentage point of revenue.
Something else moved by a lot.
What Happened
PDD Holdings, which operates Pinduoduo in China and Temu everywhere else, released second-quarter results before the US open on Monday, August 24. Revenue for the three months to June 30 reached RMB112.36 billion, equivalent to about $16.6 billion, an 8.1% increase on RMB104.0 billion a year earlier. The FactSet consensus called for RMB115.41 billion, so PDD delivered 97.4% of the revenue Wall Street had penciled in.
Profit went the other way. Net income attributable to ordinary shareholders came in at RMB27.18 billion, or roughly $4.04 billion, a 12% decline against a consensus of RMB24.40 billion. Adjusted earnings of RMB19.33 per ADS beat the RMB18.35 analysts expected by 5.3%. Shares rose about 1% before the bell after falling 1.27% in the prior session, with the American depositary receipts still more than 20% down for the year after touching a 2026 low in June.
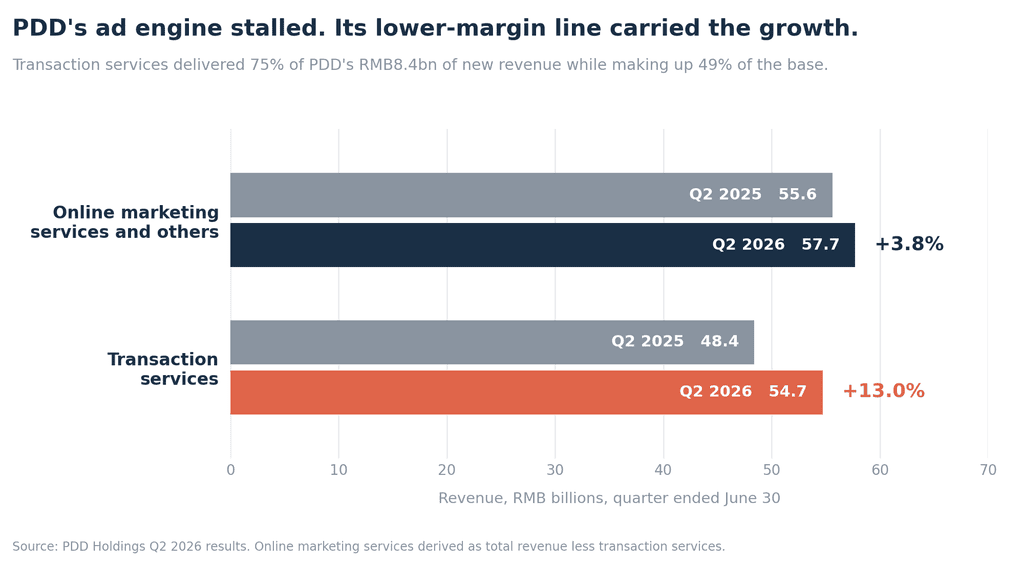
The split inside the revenue table is where the quarter gets interesting. PDD reports two lines. Transaction services, which covers commissions and the fees Temu collects from its sellers, reached RMB54.7 billion, up 13%. Online marketing services and others, the auction-based advertising business that merchants bid into for placement, is the residual: RMB112.4 billion of total revenue less RMB54.7 billion of transaction services leaves roughly RMB57.7 billion, against about RMB55.6 billion a year earlier. Growth of 3.8%.
That derivation holds up against a second route. PDD disclosed online marketing revenue of RMB49.1 billion in the second quarter of 2024, and Morningstar recorded the line growing 13% in the second quarter of 2025, which puts the base at RMB55.5 billion. The two methods land within a rounding error of each other.
So of the RMB8.4 billion PDD added to its top line, RMB6.3 billion came from transaction services and RMB2.1 billion came from advertising. The smaller line delivered three quarters of the growth.
The Backstory
The advertising line has been slowing for six quarters, and the slope is steep. It grew 29% in the second quarter of 2024, 13% in the second quarter of 2025, 8% in the third, 5% in the fourth, and 2.5% in the first quarter of 2026. Monday’s 3.8% is an improvement on that first-quarter trough and still less than a seventh of where the line was two years ago.
Transaction services ran the opposite pattern. It stalled at about 1% growth in the second quarter of 2025, the quarter the United States suspended de minimis treatment for Chinese parcels and Temu cut its American advertising to the bone. It came back at 19% in the fourth quarter and 20% in the first, and now 13%.
The result of those two curves crossing is a different company. In the fourth quarter of 2025, transaction services out-earned advertising for the first time in a full quarter, RMB63.9 billion against RMB60.0 billion. Full-year 2025 revenue reached RMB431.8 billion, up 10%, while net income fell 12% to RMB99.4 billion. First-quarter 2026 revenue grew 11% and net income fell 15%, and the stock dropped 10.4% that day to $86.61.
Two forces are pressing on the ad line at once. Douyin and Xiaohongshu have been taking Chinese merchants’ attention and budget, and Douyin published nine merchant support measures in March 2025 that included fee reductions of its own. Analysts put Douyin’s 2024 gross merchandise value near RMB3.5 trillion against Pinduoduo’s estimated RMB5.2 trillion, though neither platform has disclosed official GMV since 2020.
The second force is administrative. China’s Administrative Measures on Tax-Related Information Reporting by Internet Platform Enterprises took effect on June 20, 2025 and required platforms to file merchant identity and income data quarterly, with the first full submission due October 31, 2025. More than 4,100 platforms including Pinduoduo had filed by mid-October, and tax revenue linked to e-commerce rose 12.7% year on year in the third quarter. Deutsche Bank, writing before the print, flagged the tighter reporting regime as a continuing drag on PDD’s revenue growth. It also criticized the company for never returning capital and for disclosure it judged inadequate.
The Plan
PDD’s stated answer is to spend its way down the supply chain. Co-chairman and co-chief executive Jiazhen Zhao told analysts in May that supply chain investment would be the company’s core strategic priority for the coming decade. The company set up a dedicated first-party brand business in Changan with an opening cash injection of RMB15 billion against a total planned commitment of RMB100 billion over several years. That runs alongside the Hundred Billion Support Program of merchant subsidies, agricultural sourcing and rural logistics.
The cash is there. PDD held RMB436.1 billion in cash, equivalents and short-term investments at the end of March, and generated RMB25.7 billion of operating cash flow in the June quarter against RMB21.6 billion a year earlier. Nothing about the balance sheet limits how long this can run.
What the second quarter did not show is the spending. Sales and marketing expenses reached RMB29.7 billion against RMB27.2 billion, growth of 9.2% on revenue growth of 8.1%. As a share of revenue the line moved from 26.15% to 26.42%. Total operating expenses of RMB36.6 billion rose 13%, so the acceleration sits in the smaller research and administrative lines rather than in subsidies. Adjusted operating profit rose 5% to RMB29.1 billion.
Operations, in other words, got better. Adjusted net income fell 13% to RMB28.5 billion.
That gap is the second finding of the quarter, and it is arithmetic. A year ago PDD’s adjusted net income exceeded its adjusted operating profit by RMB5.0 billion, which is what happens when interest on a RMB400 billion cash pile outruns the tax bill. This quarter net income came in RMB0.6 billion below operating profit. The swing below the operating line is RMB5.6 billion. Operations added RMB1.4 billion. Everything under operations took away four times as much.
PDD does not break out what changed. Falling Chinese deposit rates on that cash balance, investment marks and the effective tax rate are all candidates, and the release gives an outside reader no way to separate them. Deutsche Bank’s complaint about disclosure was published a few days early and landed on the exact line item that decided the quarter.
The Business Model Angle
Two things in PDD’s revenue table are both called revenue, and they are different businesses.
Online marketing services is an auction. Merchants bid for placement, PDD serves an impression, and close to the whole ticket falls to gross profit. There is no inventory, no van, no warehouse. That line is why PDD once out-earned Alibaba on a fraction of the gross merchandise value.
Transaction services is a toll on physical movement. PDD’s own releases name the costs that ride with it: fulfillment fees, bandwidth and server costs, payment processing. In the fourth quarter of 2025 and again in the first quarter of 2026, cost of revenues grew 15% while total revenue grew 12% and 11%. The cost line tracks the growing revenue line, because they are the same activity.
So PDD’s reported growth rate is intact while its composition converts. An advertising business with structurally high incremental margin is being replaced by a logistics and commission business with structurally lower incremental margin, and the swap happens inside one table with one total at the bottom.
The advertising stall is also the more precise signal of the two. Ad revenue on a marketplace is the product of merchandise volume and monetization rate. When it flattens, either merchants are selling less through you or you are charging them less to reach buyers, and PDD has spent two years announcing that it is charging them less. Take rate is the single most powerful lever a marketplace has, and PDD has been pulling it in the direction almost no platform pulls it voluntarily.
That choice is invisible on the expense side. A subsidy shows up as a cost you can cut next quarter. A fee reduction shows up as revenue that never arrives, and reversing it means telling 15 million merchants their prices are going back up while Douyin is running the opposite promotion. Investors reading PDD’s income statement for a subsidy line they can model going away are reading the wrong side of the page.
Temu carries the same tension in a different currency. The platform has spent three years converting from a cross-border consignment model into local and semi-managed fulfillment across the US and Europe, and that conversion pushes revenue toward the transaction line by construction. Part of PDD’s mix shift is a Temu accounting consequence rather than a domestic pricing decision. The company gives no split, so nobody outside can size it.
The Risk
The near-term risk is European and it has a date on it. The European Commission fined Temu 200 million euros on May 28, the largest penalty issued under the Digital Services Act and the first aimed at illegal products on a marketplace. Investigators ran a mystery shopping exercise and found a high share of tested chargers failing basic safety checks and baby toys carrying excessive chemicals and detachable parts. The Commission faulted Temu’s 2024 risk assessment for leaning on generic e-commerce sector data instead of evidence from its own service, and for failing to consider how its recommendation engine and affiliate promotions amplify the problem.
The fine is not the exposure. It works out to about RMB1.6 billion, roughly 0.38% of 2025 revenue, or a day and a half of sales. The DSA ceiling is 6% of worldwide annual turnover, which on PDD’s 2025 revenue would be around RMB25.9 billion, sixteen times what Brussels charged. Temu has until August 28 to file an Article 75 action plan setting out its remedy. The European Board for Digital Services then has a month to opine and the Commission a further month to decide. Non-compliance opens the door to periodic penalty payments of up to 5% of average daily turnover.
The domestic risk is that the mix conversion is permanent rather than cyclical. Merchants leaving for Douyin and Xiaohongshu do not come back because PDD announces a supply chain program, and the tax reporting regime raises the floor cost of being a small Chinese seller regardless of which platform hosts them. If the advertising line settles at low single digits, PDD’s cost of revenue keeps growing faster than its revenue, and the company that trades on a single-digit multiple deserves it.
The counterargument is that PDD chose all of this and can afford it indefinitely. Operating cash flow rose. The cash balance keeps building. Morningstar’s read after the third quarter of 2025 was that reduced subsidies at Pinduoduo were already helping operating profit, which is exactly the dial the company can turn back the other way. A firm with RMB436 billion in the bank and no dividend to defend can spend a decade buying supply.
Quick Questions
Did PDD beat or miss? Both. It beat on profit by 11% and missed revenue by 2.6% against the FactSet consensus. For a company whose expense lines are discretionary, the revenue miss is the more informative half.
Is the advertising figure official? No. PDD discloses transaction services and total revenue in its release highlights, and online marketing services is the difference. The subtraction cross-checks against the 2024 base and the 2025 growth rate, but it is a derived number.
Why did transaction services fall sequentially? It came in at RMB54.7 billion against RMB56.3 billion in the first quarter, which is unusual for a June quarter carrying the 618 festival. Without segment detail on Temu, the cause is unreadable from outside.
Is Temu profitable yet? PDD has never disclosed Temu’s standalone economics, and the second-quarter release does not change that.
What about Shein? Temu’s closest competitor is heading for a Hong Kong listing at roughly a quarter of its peak private valuation, having disclosed what happens when the rules under a cross-border model get rewritten. Both companies are now paying for the same regulatory shift in different currencies.
The Business Model Analyst Take
PDD is being valued as a company with a spending problem it can stop having. The second quarter says the spending was flat and the ad business was not.
For founders running anything with more than one revenue line, the transferable point is that a blended growth rate hides the only question that matters. PDD grew 8.1%. One of its two businesses grew 3.8% and the other grew 13%, and they have different gross margins, different cost structures and different competitive positions. A single number at the bottom of a table can stay respectable for years while the composition underneath it turns into a different company. Investors will notice when the margin arrives, which is one to two years after the mix changed.
The second point is about how platforms disguise price cuts. Cutting what you charge suppliers is the most expensive form of investment a marketplace can make, and it is the only one that never appears as a cost. It sits in the revenue you failed to collect, where no analyst models it and no board reviews it as a line item. PDD has run that play for two years and called it ecosystem investment. Both descriptions are accurate. Only one of them is on the income statement.