
Advent built a payments empire by buying pieces out of bigger companies. It walked away from buying one whole, three weeks after PayPal said it would start reporting its three units separately.
Advent International and Stripe have dropped their pursuit of PayPal, ending what would have been one of the largest leveraged buyouts ever attempted. Their July offer of $60.50 a share valued PayPal at more than $53 billion and was rejected as inadequate. The number everyone is arguing about is the price. The more useful number is what PayPal earns on new business versus old business, because those two figures are moving in opposite directions and the company is three weeks away from publishing them separately for the first time in its life as a public company.
Here is the sequence, because the sequence is the story. On April 29, PayPal split itself into three operating units. On July 15, a consortium bid for all three at one price. On August 5, PayPal’s chief executive said he would replace what he called monolithic reporting with separate targets for each unit. On August 16, Stripe agreed to spend more than $7 billion on an AI model gateway. On August 27, the consortium walked.
What Happened
Bloomberg reported on Thursday that the group of Advent International and Stripe is no longer pursuing PayPal, citing people familiar with the matter. PayPal shares fell more than 15% in premarket trading on Friday to $52.50, having closed at $61.81 on Wednesday. The stock had climbed more than 42% over the quarter on the expectation that a deal would be agreed.
The consortium offered $60.50 a share in July, valuing PayPal at more than $53 billion. PayPal’s board considered the offer inadequate and, according to Reuters, also flagged regulatory and financing hurdles. The company never formally responded to the proposal. Bloomberg’s sources said the buyers could return if circumstances change. PayPal did not immediately respond to a request for comment, Stripe said it does not comment on rumors or speculation, and Advent declined to comment.
One detail from the earlier reporting matters more than it looks. Reuters has said that Block, Stripe and Advent first approached PayPal together in April, and that Block left the consortium before an offer was submitted. Three buyers went in. Two came out. Then none.
The Backstory
PayPal has been a company looking for a shape for three years. Alex Chriss was ousted in February 2026 after a run of missed targets. Bloomberg reported that same month that Stripe was weighing an acquisition of PayPal or of parts of it, naming Braintree and Venmo as the assets in question. The board hired Enrique Lores, who had run HP Inc. for six years, a company that exists in its current form only because it was cut in half.
Lores moved fast. On April 29 he announced a three business operating model: Checkout Solutions and PayPal, Consumer Financial Services and Venmo, and Payment Services and Crypto, the last of which houses Braintree, small business processing and the PYUSD stablecoin. In May he committed to cutting 20% of the workforce over two to three years and at least $1.5 billion of gross run rate savings. In June PayPal wound down its venture arm. In August he told an interviewer that PayPal would set revenue targets for each of the three units for the first time, and that the new segmented format would give investors visibility into each business.
At the time he said it, he and the board were sitting on a $53 billion offer.
The Plan
Look at what the buyers actually are, because a consortium is a structure and structures are confessions.
Advent’s payments franchise was not built by buying payment companies. It was built by carving them out of other people’s balance sheets. Worldpay came out of Royal Bank of Scotland in 2010. Vantiv came out of Fifth Third. Nets, Planet, Prisma, Xplor and myPOS followed the same pattern of separation. Advent’s own published payments sector report describes its landmark deals in exactly these terms, and notes that the carve-outs were complex and that separating the businesses was the work. This is a firm whose entire edge in the category is knowing what a payments asset is worth once you pull it out of a parent that was strangling it.
Stripe wants something narrower. It runs the largest independent acquiring business on the internet and it needs neither PayPal’s consumer wallet nor its brand. What it plausibly wants is Braintree’s enterprise processing relationships, Venmo’s checkout button, and a route to less dependence on the card networks. Bloomberg said as much in February.
So the offer that reached PayPal’s board was a whole company bid assembled by two parties who wanted different fractions of it, after a third party who presumably wanted a third fraction had already left. A sponsor takes the consolidated cash flow, underwrites the debt, and sells the strategic the piece it came for. That is not a takeover. It is a break-up with a single wrapper on the front, and it is only cheap for the buyers while nobody outside the room can price the pieces.
The Business Model Angle
PayPal has reported as one segment since it separated from eBay in 2015. Its filings say the chief operating decision maker reviews results on a consolidated basis, so the company operates as one segment and has one reportable segment. Every outside estimate of what Venmo alone is worth, or what Braintree alone earns, has been a guess built from scraps management chose to mention on calls.
That single number hides a company pulling in two directions, and the arithmetic is stark once you separate new business from old.
In the second quarter, PayPal processed $486.45 billion of payment volume, up from $443.5 billion a year earlier. That is $42.95 billion of new volume. Transaction revenue rose 5% to $7.83 billion, which is $373 million of new revenue. Transaction margin excluding interest on customer balances rose 3% to $3,619 million, which is $105 million of new margin.
Run those against each other. The average dollar of volume in the quarter carried 161 basis points of transaction revenue, matching the 1.61% take rate PayPal reported. The marginal dollar, the volume that was not there a year ago, carried 87 basis points. At the margin line the gap widens: 74 basis points on the average dollar against 24 basis points on the new one. New volume earns about a third of what existing volume earns.
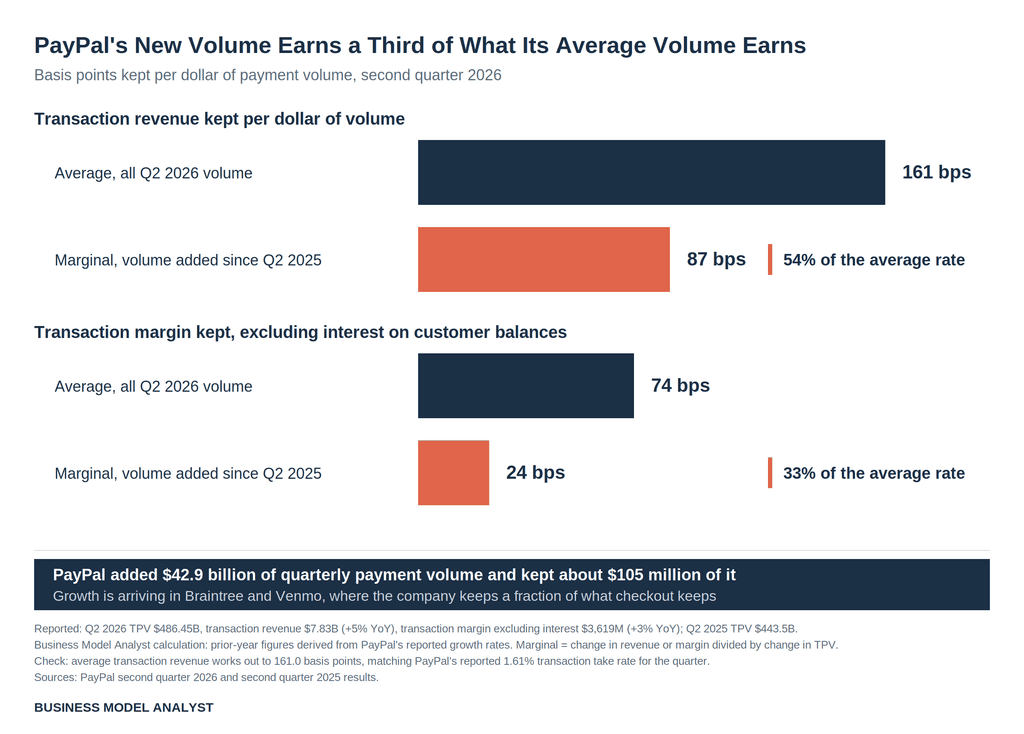
The reason is not mysterious and management does not hide it. Branded checkout, the high margin business, grew 2% on a currency neutral basis. Venmo and Braintree grew in the mid teens. Growth is arriving almost entirely in the units where PayPal keeps the least, which is why revenue grew 5% while transaction margin grew 1%, and why non-GAAP operating margin fell 248 basis points in a quarter the company described as ahead of expectations.
Now the point. Under US segment reporting rules, reportable segments follow how the chief executive actually manages the business and allocates resources. Lores changed that on April 29 and then said in August that he would publish targets for each unit. Once he does, the buried trade becomes public property. Anyone will be able to see which of the three businesses is a growing consumer franchise, which is a commodity processing utility, and which is a high margin annuity in slow decline, and price each accordingly.
A whole company bid is worth the most to a buyer at the exact moment nobody else can do that sum. That window was closing.
None of which means the board was being noble. It had its own arithmetic. PayPal guides to roughly $6 billion of buybacks against at least $6 billion of adjusted free cash flow this year. Before the bid was known, the stock was in the low forties, which puts the market value near $37 billion. Six billion dollars of repurchases at that price retires about 16% of the company annually and lifts per share claims on the rest by roughly 19% if the multiple holds. The 39% premium the consortium offered over the unaffected price was worth about two years of PayPal doing nothing at all except buying its own stock. A board with that option prices a takeover against itself, and its own bid never expires.
The Risk
Three explanations compete with this one, and two of them are strong.
The first is that the price simply ran away. PayPal’s unaffected share price can be reconstructed two ways that agree: the stock closed at $61.81 on Wednesday after a quarterly gain of more than 42%, which implies a June 30 level near $43.53, and the observed trading average between mid May and mid June was $43.24. At $61.81, any respectable premium means an equity cheque near $70 billion. For a leveraged buyout of a business whose transaction margin is growing 1%, that is a different transaction from the one that was underwritten in July. This explanation needs no thesis at all, and it is probably part of the answer.
The second is antitrust. Stripe moved roughly $1.9 trillion of volume in 2025 and PayPal is moving close to the same. Combining the two largest independent online payment platforms is a two year review at best, and Stripe is a private company with an IPO to think about. PayPal’s own board reportedly raised regulatory and financing concerns alongside price.
The third cuts against me directly, and it deserves stating plainly. If separate disclosure makes the parts easier to price, it should make a bid for one part easier, not harder. That is the falsification test for everything above. If the reading here is right, the next approach to PayPal is not for the company. It is for Venmo, or for Braintree, and it arrives after the first quarter of segmented numbers. If instead nothing comes and PayPal is still whole in a year, the simpler story wins: the buyers just could not make the debt work at $60 a share.
Worth holding onto as well: the currencies in this deal were not symmetrical. PayPal’s price is set every day by a public market. Stripe’s $159 billion valuation comes from tender offers it runs itself, and it has been paying for acquisitions in cash and stock. Nobody disclosed the mix on the PayPal bid. A board being asked to swap an audited public quote for a partly self marked private one has a reason to take its time that has nothing to do with the number on the cover.
One last data point, because it is a revealed preference. On August 16, eleven days before walking away from PayPal, Stripe agreed to pay more than $7 billion for OpenRouter, an AI model gateway with roughly $140 million of annualized fee revenue. Stripe had a spending decision to make and it made it. The token stack won.
Quick Questions
Did PayPal’s board turn down a good price? On a multiple basis, $53 billion is about 3.4 times PayPal’s guided 2026 transaction margin dollars, on a business generating at least $6 billion of adjusted free cash flow. Against the 16% free cash flow yield the board could harvest through buybacks at the unaffected price, refusing was defensible. Against a business whose marginal dollar earns a third of its average dollar, so was bidding low.
Has the market given the deal premium back? Not most of it. At $52.50, PayPal is still about 21% above the reconstructed pre bid level, which is roughly $9 a share, or close to $7.7 billion of market value the market is declining to hand back. That is the price of the option that somebody returns.
Why did Block leave the consortium? Neither Block nor the other parties have said. What is on the record is that all three approached PayPal in April and that Block exited before the offer went in.
Is a break-up now more likely? Lores has said the three businesses are stronger together and that he intends to keep the company intact. He has also spent five months building the exact disclosure architecture a break-up would require, at a company he joined from one that split itself in two. Watch the first quarter of segmented reporting rather than the statements.
What was PayPal worth at its peak? The stock’s record close was $305.88 in July 2021. Peak market value has been reported at figures ranging from $280 billion to roughly $360 billion. Even the low end of that range is more than five times the offer the board just refused.
The Business Model Analyst Take
The lesson here is not about payments. It is about what disclosure does to price.
A conglomerate discount is usually described as a market failure, as if investors were being lazy. It is more accurate to call it an information price. When a company reports one number for several businesses, outsiders cannot tell which parts are compounding and which are melting, so they mark the whole thing at something close to the worst part. That discount is a cost to shareholders. It is also an asset, and the people it belongs to are buyers who have done the segmentation privately and can therefore pay a premium to the consolidated multiple while paying a discount to the sum of the parts.
Every founder running more than one business model under one P&L is holding this trade, usually without knowing it. The question to ask is not whether the businesses share customers or infrastructure. It is whether anyone outside can tell them apart. If they cannot, the first sophisticated buyer through the door gets to price the confusion, and they will price it in their favor.
PayPal spent five months dismantling its own information advantage against itself. Whether that was the plan or an accident, the effect was the same: it made the company harder to buy cheaply and easier to take apart in public. The bid did not survive it.
Watch what arrives after the first set of three numbers. That is when we find out whether PayPal built a better disclosure or just a better prospectus.