
Patagonia Value Chain Analysis at a Glance
What it is: A breakdown of the primary and support activities Patagonia, Inc. uses to turn raw fiber into a $1.47 billion outdoor apparel business, and an audit of where along that chain the company creates value versus where it captures it.
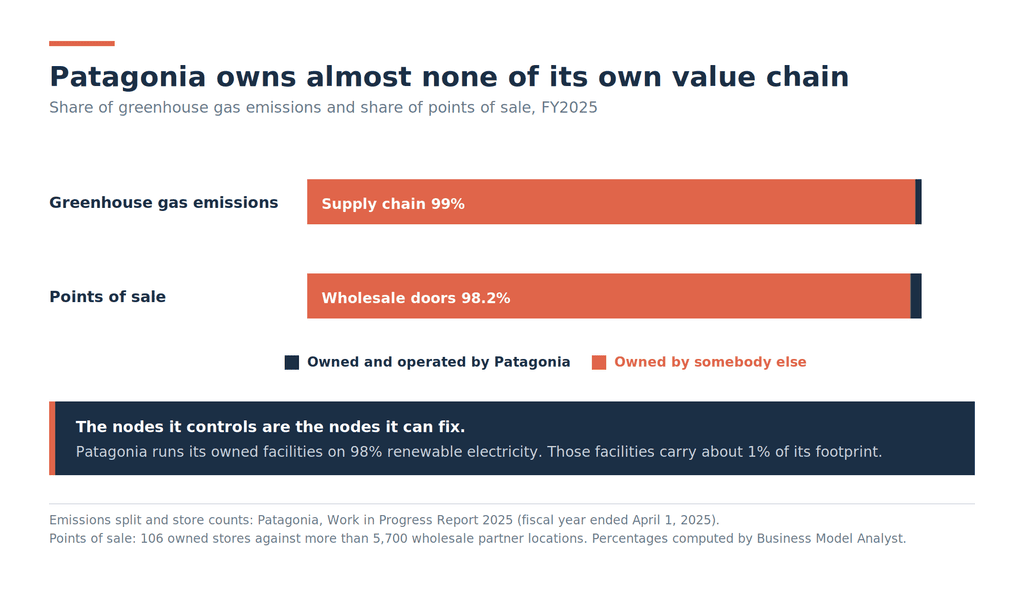
The core finding: Patagonia owns no factories, no mills and no farms. About 99% of its emissions and 98% of its points of sale sit inside businesses somebody else owns. What Patagonia owns outright is the product specification, the audit apparatus, the aftermarket and the brand. Its competitive advantage lives in those four places and stops at their edges.
Key 2026 takeaway: Patagonia buys from 50 finished-goods factories in 11 countries, roughly $29 million of annual revenue per factory against Nike’s $116 million. It is a small customer everywhere it buys. The leverage comes from selection and from paying for the governance itself, not from purchasing power.
Most value chain analyses of an apparel brand end up describing the same nine boxes Michael Porter drew in 1985 and calling it strategy. Patagonia deserves a harder look, because the company publishes more about its own supply chain than any comparable brand and the disclosures contradict the story most people tell about it.
Two documents drive this analysis. The first is the Work in Progress Report 2025, Patagonia’s debut impact report, published in November 2025 and covering the fiscal year ended April 1, 2025. The second is Patagonia Works’ Statement on Forced Labor, Modern Slavery, Child Labor, signed by General Counsel Hilary Dessouky on May 30, 2026, covering May 2025 through April 2026. The second document contains a number almost nobody has quoted, and it changes the picture. For the wider strategic context, pair this with our Patagonia business model breakdown and our Patagonia SWOT analysis.
What a value chain analysis asks
Porter split a company into five primary activities (inbound logistics, operations, outbound logistics, marketing and sales, service) and four support activities (firm infrastructure, human resource management, technology development, procurement). The margin is whatever the customer pays above the cost of running all nine.
The framework carries an assumption that fits 1985 better than 2026: the company performs the activities. Patagonia performs almost none of them. Sorting the chain by owner rather than by activity gives a sharper read.
| Value chain node | Who owns the asset | Patagonia’s control instrument |
|---|---|---|
| Fiber and farms | Independent growers and processors | Fibers Sourcing Policy, certification standards |
| Mills and trim (Tier 2) | 22 countries of material suppliers | Audits covering 80%+ of material cost, bluesign, Higg |
| Cut and sew (Tier 1) | 50 independent factories | Code of Conduct, 100% audit coverage, Fair Trade nomination |
| Inbound freight and DCs | Third-party carriers, Patagonia’s Reno DC | Direct ownership of the Reno facility |
| Wholesale doors | 5,700+ retail partners | Dealer terms, allocation |
| Owned retail and e-commerce | Patagonia (106 stores) | Direct ownership |
| Repair and resale | Patagonia (Reno repair center, Worn Wear) | Direct ownership |
| Design and specification | Patagonia (Ventura, California) | Direct ownership |
Read the right-hand column and the strategy shows up. Patagonia governs what it does not own by writing the specification, paying for the inspection and refusing to buy from anyone who will not take the terms.
Inbound logistics and procurement: the specification is the lever
Patagonia’s material inputs generate most of its footprint, and the company changed them without buying a single mill. By the Fall 2025 line, 86% of fabrics and trims by weight were preferred materials, used across 99% of products. 93% of the polyester and 89% of the nylon are recycled. From Spring 2025 onward, 100% of new styles carry no intentionally added PFAS, closing out roughly two decades of reformulation work.
None of that required capital expenditure on production assets. Patagonia wrote different specifications in Ventura and refused orders that missed them. A brand that owns nothing can still dictate chemistry, because the buyer defines the bill of materials.
The limit of that power shows up in one number. Patagonia targets 50% of its synthetic fabric from secondary waste such as textile scrap and ocean-bound nets. It sits at 6%. Recycled polyester from drink bottles is abundant and cheap, so the spec moved fast. Textile-to-textile recycled fiber barely exists at commercial volume, so the spec has nowhere to point. Specification power runs into upstream supply, and no amount of purchasing discipline conjures a fiber that nobody makes yet.
The procurement function also carries a policy most brands skip. Patagonia formalized a Fibers Sourcing Policy in 2020 that bars suppliers from buying cotton grown in China, Turkmenistan or Uzbekistan, and from running any manufacturing process in Xinjiang. Factory partners sign an acknowledgment. That is a procurement rule doing the work a compliance department usually does after the fact.
Operations: 50 factories, none of them Patagonia’s
Patagonia’s May 2026 filing gives the cleanest picture of its manufacturing base anyone has published:
| Manufacturing base | 2026 figure |
|---|---|
| Finished-goods factories | 50 |
| Countries with finished-goods factories | 11 |
| Countries with material suppliers | 22 |
| Material-supplier countries with only one or two suppliers | 8 |
| “Key” material-supplier countries | 14 |
| Fair Trade Certified factories | 30+ |
| Share of styles made in a Fair Trade Certified factory (FY2026) | Over 95% |
| Finished-goods factories audited | 100% |
| Share of material cost covered by Tier 2 audits | Over 80% |
| Full-time field managers monitoring the chain | 5 |
Five people cover 50 factories plus the key mills. Ten factories each, supported by third-party monitoring firms, NGO partners and the Fair Labor Association’s own sampling. The governance layer running Patagonia’s most-praised competitive asset would fit around one conference table.
The purchasing arithmetic is where the received wisdom breaks. Divide FY2025 sales of $1.47 billion across 50 factories and Patagonia buys roughly $29.4 million of output per factory per year. Nike’s FY2025 10-K discloses 97 finished-goods footwear factories in 11 countries and 303 finished-goods apparel factories in 34 countries, 400 in total, against roughly $46.3 billion of revenue. That is about $115.8 million per factory, close to four times Patagonia’s figure.
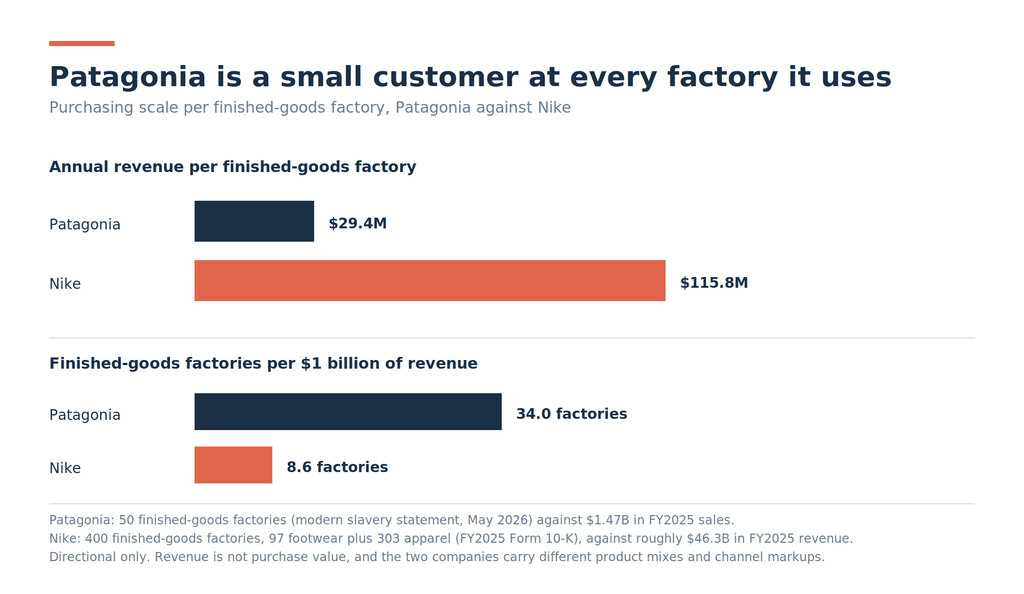
Patagonia is the smaller account in the room. It cannot threaten a factory with the loss of a quarter of its capacity, because it rarely represents a quarter of anyone’s capacity. So the leverage has to come from somewhere else, and it does:
- Selection with veto rights. Since the mid-2000s Patagonia has run a “4-fold” pre-screen in which its sourcing, quality, social responsibility and environmental teams each hold veto power over a new factory. The group meets weekly. In 2011 the company extended the same screen to fabric and trim suppliers. A factory that will not meet the terms never gets the order.
- Paying for the inspection. Patagonia funds the social audits it schedules, contributes to factory training programs and pays for a multi-channel worker grievance hotline run by a third party in workers’ native languages.
- Constraining its own buying behavior. The Responsible Purchasing Practices program, formalized in 2011 under FLA Principle 8, commits Patagonia to avoid the things brands routinely do to factories: last-minute order changes, unreasonably low price negotiation, compressed lead times, late fabric deliveries. Those buyer behaviors are what produce forced overtime and falsified payroll downstream. Patagonia treats its own purchase order as a labor-conditions instrument.
- Staying put. The company operates an FLA-approved responsible exit policy and cut its primary factory count in half years ago to deepen the remaining relationships rather than shop for price.
One more operational choice deserves attention because it cuts against industry orthodoxy. Patagonia schedules most of its audits by appointment. The company states in its 2026 filing that unannounced audits have not produced higher rates of findings and tend to encourage supplier secrecy. Reasonable people disagree with that position. It is a deliberate trade of surprise for candor, and it tells you the company is optimizing the audit for remediation rather than for catching people out.
The certification gap nobody quotes
Over 95% of Patagonia styles are made in a Fair Trade Certified factory. Patagonia has paid more than $43 million in premiums into worker-controlled accounts since the program began in 2014, reaching more than 90,000 workers across 10 countries. Both facts appear in almost every article about the company.
The Work in Progress Report contains the other half. 39% of the factories making Patagonia products pay a living wage. Another 29% pay about 80% of one. The rest pay roughly half.
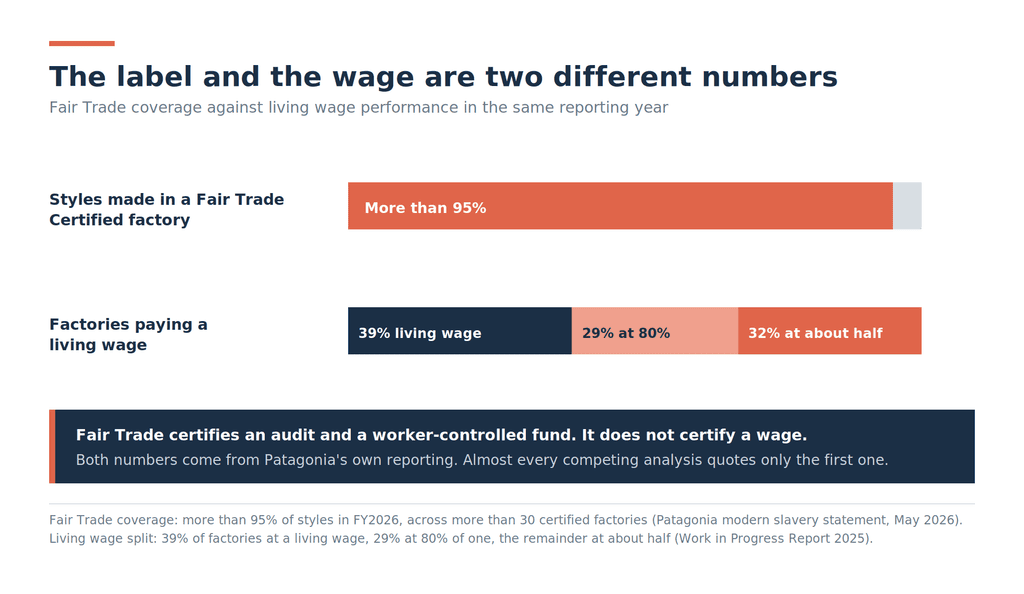
Those two numbers sit in the same company’s disclosures for the same period and they measure different things. Fair Trade USA certifies an audited workplace, a worker-management committee and a fund the workers control. It sets the premium based on the gap between factory pay and the local living wage, then routes the money to a bank account workers govern. Workers vote on how to spend it, choosing cash bonuses, childcare, health programs or store vouchers.
A premium paid into a community fund is not a wage. Patagonia says so on its own website, in language most summaries drop: the company does not own the factories, so it has limited control over what workers get paid, and Fair Trade is described as a step toward a living wage rather than the achievement of one.
For anyone reading a competitor’s Patagonia page, that distinction is the difference between a supply chain that pays fairly and a supply chain that funds a committee. Patagonia is doing more than its peers on both counts. It has not solved the wage problem, and it does not claim to have.
Outbound logistics and distribution: a chain that ends in someone else’s store
Patagonia ships from its Reno, Nevada distribution center, one of the few large physical assets it owns. Sales reach customers through three routes: 106 company-owned stores, patagonia.com, and wholesale distributors in more than 40 countries feeding over 5,700 partner locations. FY2025 sales split 61% United States, 39% international, across 45 countries where products are available and 25 with an owned or partner presence.
Owned doors account for 1.8% of the physical footprint. For a brand whose merchandising, staff training and price discipline carry so much of the value proposition, handing 98.2% of the shelf to third parties is a structural leak. Every wholesale door is a place where the story gets told by someone Patagonia does not employ, and where the markdown calendar belongs to someone else. Our Patagonia target market analysis covers who is standing in front of those shelves.
Marketing and sales: activism in place of ad spend
Patagonia substitutes campaign spending with position-taking. The company refuses to advertise on Meta, funds grassroots organizations through Patagonia Action Works, and built its most famous piece of marketing around telling people not to buy a jacket.
The cost line that replaces advertising is the 1% for the Planet Earth tax, levied on sales rather than profit. Patagonia routed close to $15 million in the FY2025 period and about $240 million across four decades of giving. A levy on revenue behaves like a royalty. It sits above the margin line, survives a bad year and cannot be trimmed by a CFO managing to an earnings number. That is the point of putting it there.
Service: the aftermarket is real, and it is 1% of the business
Patagonia has repaired gear since 1976 and built a dedicated repairs team in 1998. The Reno repair center is the largest apparel repair facility in North America. Worn Wear launched in 2013 as trade-in, resale and repair under one roof, backed by more than 100 care and repair guides co-published with iFixit.
Repair volume has grown from roughly 30,000 pieces a year in 2015 to 174,799 products repaired globally in FY2025. Worn Wear generated $13 million in the same year, about 0.9% of sales.
The reason that number stays small is structural rather than strategic. Repair is the one node in the chain Patagonia never outsourced. A Reno technician completes about five to six repairs a day. Across a repairs organization of roughly 115 people, the arithmetic lands near 1,500 repairs per person per year, which is close to what the company’s throughput implies. Doubling new-product volume means writing a larger purchase order against somebody else’s capital. Doubling repair volume means hiring and training a hundred more technicians on Patagonia’s payroll.
New production scales through other people’s factories. The aftermarket scales through Patagonia’s headcount. That asymmetry, more than any marketing decision, is why the most mission-aligned node in the value chain remains a rounding error on the income statement, while 85% to 90% of products still have no end-of-life solution.
Support activities: infrastructure, people, technology
Firm infrastructure. Patagonia Works is the holding company for Patagonia, Inc. (apparel and equipment), GPIW (retail stores) and associated entities. Since September 2022 the Patagonia Purpose Trust holds 2% of the stock and all voting control, and the Holdfast Collective holds the other 98%. The structure functions as a capital allocation rule: profit not reinvested leaves as a dividend to fund climate work. Worth noting for anyone auditing the disclosures, the modern slavery statement does not yet cover Patagonia Provisions or Fletcher Chouinard Designs, so the transparency perimeter is narrower than the corporate one.
Human resource management. Patagonia employed 3,716 people globally in FY2025, and 98% of the electricity in its owned and operated facilities is renewable. Both figures describe the sliver of the chain the company employs and powers directly. The other 100,000-plus people making Patagonia products work for somebody else.
Technology development. Material science is Patagonia’s R&D, and its output is a specification rather than a patent portfolio. Recycled synthetics engineered to match virgin durability, traceable down verified from parent farm forward, PFAS-free durable water repellency. The Footprint Chronicles, launched in 2007, turned the supply chain map itself into a technology asset by publishing factory locations, worker counts and tenure.
Procurement. Covered above, and the most underrated function in the company. Patagonia’s buyers hold veto power alongside its sustainability staff, which is an unusual reporting structure and the reason the standards survive contact with a cost target.
Where the value gets captured
A value chain analysis has to answer where the surplus lands. Patagonia’s is unusual because the company publishes enough to work it out.
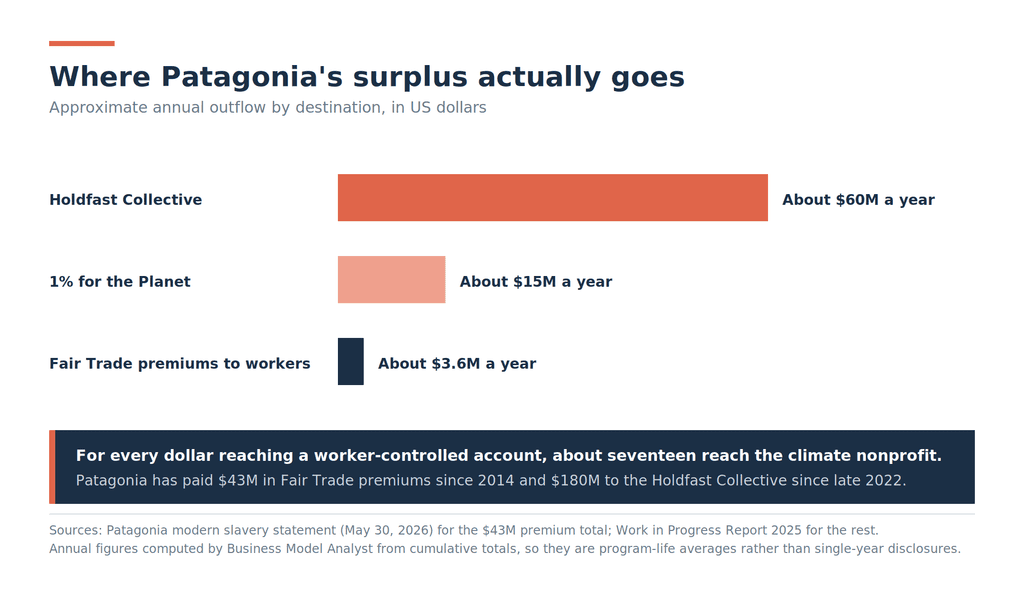
Spread $43 million across twelve years and more than 90,000 workers and the cumulative premium works out under $500 per worker for the life of the program. Against a single year of sales, the entire twelve-year premium total equals 2.9%.
For every dollar Patagonia routes to a worker-controlled account, roughly seventeen dollars go to the climate nonprofit. Both flows are voluntary and neither exists at most competitors. The ratio is a statement of priority, and it is consistent with a company whose stated purpose is the planet rather than the workforce. Read alongside the 39% living wage figure, it explains why progress on wages has been slower than progress on materials: the money is going somewhere else, by design.
The ownership change accelerated the giving sharply. Roughly $240 million across four decades works out near $6 million a year. The Holdfast dividend runs around $60 million. Yvon Chouinard’s 2022 transfer multiplied the outflow by about ten. Whether that surplus could have been split differently is a governance question, not a supply chain one, and our piece on whether Patagonia is profitable covers the earnings side.
Patagonia value chain by the numbers
| Metric | Figure | Source period |
|---|---|---|
| Sales | $1.47 billion | FY ended April 1, 2025 |
| US / international split | 61% / 39% | FY2025 |
| Finished-goods factories | 50 in 11 countries | May 2026 |
| Material-supplier countries | 22 | May 2026 |
| Owned stores / wholesale doors | 106 / 5,700+ | FY2025 |
| Global employees | 3,716 | FY2025 |
| Emissions in the supply chain | About 99% | FY2025 |
| Renewable electricity, owned facilities | 98% | FY2025 |
| Preferred materials by weight | 86% of Fall 2025 line | Fall 2025 |
| Recycled polyester / nylon | 93% / 89% | 2025 |
| Synthetics from secondary waste | 6% against a 50% target | FY2025 |
| Factories paying a living wage | 39% | FY2025 |
| Fair Trade premiums paid | $43M+ since 2014 | Through April 2026 |
| Products repaired | 174,799 | FY2025 |
| Worn Wear revenue | $13M, about 0.9% of sales | FY2025 |
Frequently Asked Questions
Does Patagonia own its factories? No. Patagonia states plainly that it owns no factories. Products come from 50 independent finished-goods factories in 11 countries, supplied by material suppliers in 22 more. The company owns its Ventura headquarters, its Reno distribution and repair center and 106 retail stores.
What is the strongest link in Patagonia’s value chain? Product specification. Patagonia changed the chemistry of its entire line, reaching 93% recycled polyester and eliminating intentionally added PFAS from new styles, without owning a mill. The buyer writes the bill of materials, and that is the lever.
What is the weakest link? Wages at the cut-and-sew stage. Patagonia’s own reporting puts 39% of its factories at a living wage. The Fair Trade premium reaches worker-controlled funds but does not raise base pay, and with roughly $29 million of annual purchases per factory the company lacks the volume leverage to force the issue alone.
How does Patagonia control a supply chain it does not own? Through four instruments it does own: the specification, a four-department veto over which factories get orders, audit and grievance infrastructure it pays for, and a purchasing-practices policy that restricts its own buyers from squeezing suppliers on price and lead time.
Is Worn Wear a meaningful business line? Not yet, at $13 million against $1.47 billion in FY2025. Repair capacity scales with technicians on Patagonia’s payroll rather than with third-party factory capacity, which caps how fast the aftermarket can grow.
The Business Model Analyst Take
Patagonia is a design, specification and brand company that rents the rest of its value chain and governs it with paperwork. That structure explains both the wins and the stalls with a single logic.
Where a written standard is enough, Patagonia moves fast. Materials chemistry, PFAS, traceable down, recycled synthetics, factory transparency. Ventura writes it, buyers enforce it, factories comply or lose the order.
Where the outcome depends on money changing hands at the bottom of the chain, progress slows. Wages need volume leverage Patagonia does not have, or a premium far larger than the one it pays. Textile-to-textile recycling needs an upstream industry that does not exist. End-of-life solutions need a collection and reprocessing network nobody has built. A specification cannot summon capacity.
The useful lesson for anyone building a supply chain runs against the usual reading of this company. Patagonia’s advantage did not come from buying power or from vertical integration. It came from being willing to fund the governance layer itself, to give its sustainability staff a veto over its sourcing staff, and to restrict its own purchase orders in ways that cost money. Those are cheap decisions in absolute dollars and expensive ones politically, which is exactly why competitors with ten times the purchasing scale have not copied them.
The open question for 2026 and beyond is whether a company that hands 98% of its emissions and 98% of its shelf space to other people can hit a 2040 net zero target on the strength of a specification and five field managers. Patagonia titled its first impact report Work in Progress. The value chain is why.