
Every competing analysis says tightening sustainability regulation favors the company that got there first. The 2026 rulebook says the opposite. Brussels withdrew the law that would have forced Patagonia’s rivals to catch up, then kept the law that governs what Patagonia is allowed to say.
Patagonia sold $1.47 billion of outdoor apparel in the fiscal year ended April 1, 2025, from 3,716 employees, 106 owned stores and more than 5,700 wholesale doors across 45 countries. Since September 2022 the Patagonia Purpose Trust has held all voting stock and the Holdfast Collective, a 501(c)(4) nonprofit, has held the other 98%. That structure decides what the macro environment does to this company, because it means Patagonia cannot raise equity to absorb a compliance shock and cannot dilute a claim without damaging the asset the claim sits on.
Run a standard PESTLE on Patagonia and you get a list of tailwinds. Run it against the calendar for the next thirty-six months and you get something less comfortable.
What a PESTLE analysis is
A PESTLE analysis maps the six external forces a company cannot control: Political, Economic, Social, Technological, Legal and Environmental. Unlike a SWOT, which mixes internal and external factors, PESTLE covers only the outside world. For the framework itself, see our guide to what a PESTLE analysis is and our breakdown of the environmental factors affecting business.
The six forces at a glance
| Force | The move that matters in 2026 | Direction for Patagonia |
|---|---|---|
| Political | US import duty rebuilt four times in eighteen months, now priced by country tier | Negative, and indifferent to supplier diligence |
| Economic | No equity market, no debt appetite, growth capital competes with the donation | Structurally constrained |
| Social | Brand-as-identity cuts both ways, as the Pattie Gonia suit showed | Mixed, with reputational tail risk |
| Technological | Textile-to-textile recycling still absent at scale; PFAS chemistry solved early | Mixed |
| Legal | EU claim rules bind September 27, 2026; EU conduct rules slip to 2029 | Negative, and asymmetric |
| Environmental | Emissions rose 2% in FY2025 against a required 10% annual cut | Negative |
The setup: two regulatory clocks, running at different speeds
Between now and the end of 2029, Patagonia faces two families of rules.
The first family governs what the company says and what it must publish. California’s SB 707 already required it to register with a textile producer responsibility organization by July 1, 2026. The EU’s Empowering Consumers for the Green Transition Directive starts applying on September 27, 2026, banning generic environmental claims and product-level “climate neutral” labels that rest on offsets. California’s SB 253 wants Scope 1 and 2 emissions filed by November 10, 2026, with Scope 3 the following year.
The second family governs what apparel companies must physically do about their supply chains. That family got pushed back. The European Commission announced in June 2025 that it would withdraw the Green Claims Directive. In February 2026 the Council adopted the Omnibus I Directive, which raised the Corporate Sustainability Due Diligence Directive’s threshold to 5,000 employees and EUR 1.5 billion of turnover, cut the population in scope from roughly 13,000 companies to roughly 6,000, deleted the mandatory climate transition plan, removed the EU-wide civil liability regime, and moved the compliance date to July 26, 2029.
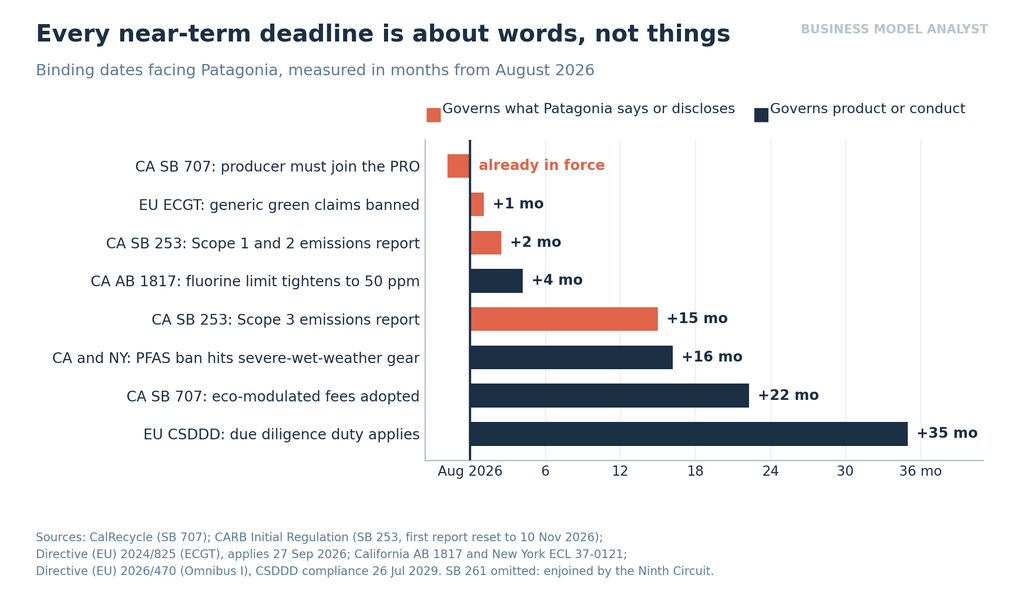
Every coral bar lands inside fifteen months. Every navy bar lands after. That gap is the analysis.
Political
Patagonia does not own a single factory. It buys finished goods from 50 factories in eleven countries and materials from suppliers in twenty-two more, which makes US trade policy a direct input cost rather than a background condition.
That input cost has been rebuilt four times since April 2025. The Supreme Court struck down the IEEPA tariffs on February 20, 2026 in Learning Resources, Inc. v. Trump, and collection stopped four days later. A temporary 10% Section 122 surcharge ran from February 24 to its 150-day statutory expiry on July 24, 2026. USTR replaced it the same minute with Section 301 forced-labor tariffs on sixty economies, set at a country tier of 10% or 12.5%.
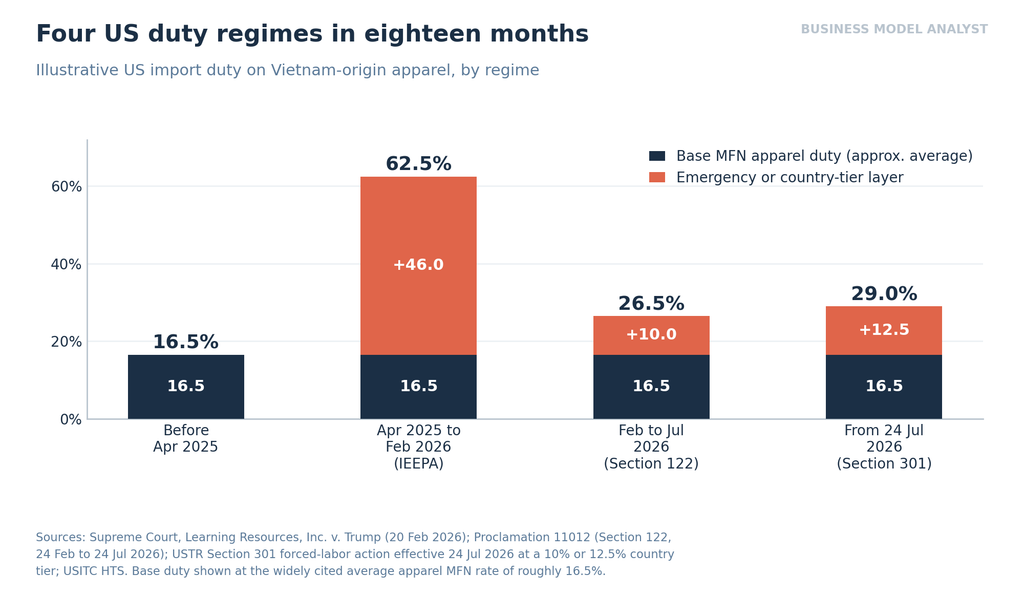
Read the last bar again. Washington now prices forced-labor risk, and it prices it by passport.
Patagonia audits 100% of its finished-goods factories and the material suppliers covering more than 80% of its material cost. It keeps five full-time field managers in Asia. It bans cotton from China, Turkmenistan and Uzbekistan and any processing in Xinjiang. More than 90,000 workers sit inside its Fair Trade program. None of that changes the tariff by a single basis point, because the rate attaches to the country of origin and not to the importer’s conduct.
Size the gap. Assume 61% of sales land in the US, matching the split Patagonia publishes, and assume landed first cost runs between 25% and 35% of net revenue, which brackets a brand selling through both owned retail and wholesale. The Section 301 layer alone then costs somewhere between $22 million and $39 million a year. Patagonia’s Earth tax, the 1% of sales it has paid since 1985, runs near $15 million. The tariff that exists because of labor conditions in Asia costs this company between one and a half and two and a half times what it voluntarily donates to the planet, and buys it nothing in return.
The other political variable is demand-side. Roughly $1.2 trillion of US outdoor recreation spending depends on access to public land, and 2026 brought the next phase of Roadless Rule rescission plus continued proposals to dispose of federal acreage. Patagonia’s owner is a 501(c)(4), a vehicle that may spend on political advocacy in ways a 501(c)(3) may not. Owning a brand through a political entity converts every campaign into a balance-sheet question about the brand.
Economic
Patagonia has no share price, no analyst coverage and no equity to issue. The Holdfast Collective takes what the company does not reinvest, which puts growth capital and the donation on the same line of the same page. Our is Patagonia profitable breakdown covers the mechanics; the macro point is that any external cost shock has to be paid out of retained earnings or out of the grant.
Three cost lines moved in 2026.
Tariffs. Covered above. Columbia Sportswear, the closest listed comparator at roughly $3.47 billion of guided FY2026 revenue, raised its gross margin guidance in April 2026 on the strength of lower-than-planned US tariffs, which tells you how much of an apparel P&L the duty layer swings.
Compliance. Substantiating an environmental claim costs about the same in absolute dollars whether the claim sits on a $1.5 billion revenue base or a $46 billion one.
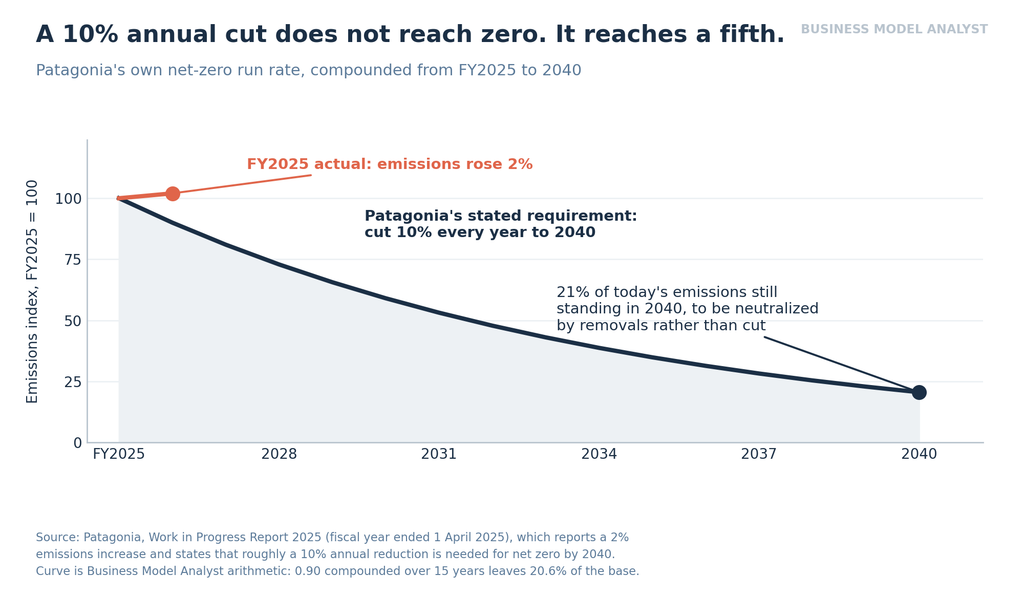
The regulation is written per company. The revenue is not. Patagonia rests more of its positioning on environmental claims than any of the three brands to its right, and has 3.2% of Nike’s revenue to spread the substantiation cost across.
Repair labor. Patagonia repaired 174,799 products in FY2025 and turned $13 million through Worn Wear, about 0.9% of sales. Doubling new production means writing a larger purchase order against somebody else’s capital. Doubling repair means putting a hundred more technicians on Patagonia’s own payroll at US wages, while production stays denominated in Vietnamese dong. Our Patagonia value chain analysis works through why the most mission-aligned node in the business stays stuck near one percent of revenue.
Social
The brand’s strength is that customers treat it as identity rather than product. Our target market analysis found an audience that would sooner buy nothing than substitute a competitor. Identity-grade loyalty comes with a bill.
On January 21, 2026, Patagonia sued Wyn Wiley, the drag performer and climate activist known as Pattie Gonia, in the Central District of California for trademark infringement. Wiley had filed to register PATTIE GONIA for apparel and marketing services in September 2025. Patagonia asked for $1 in damages plus fees and said it cannot enforce its marks selectively without losing the ability to stop oil and gas lobbyists, counterfeiters or hate groups from using them. Wiley rejected a settlement in late May, told two million followers the company was trying to take her name, and framed the suit as a betrayal of Patagonia’s mission. Trial is set for June 2027.
The legal position is defensible. The social position is expensive. Both sides of that dispute recruit from the same audience, and an audience that buys a jacket as a political statement will read a lawsuit as one too.
Two other social currents are worth tracking. Consumer skepticism toward environmental marketing keeps rising, which is what the EU regulation is responding to, and which erodes the value of any claim including a true one. And Patagonia’s fleece vest became a finance-industry uniform, a drift the company tried to slow in 2019 by restricting corporate co-branding. Brand meaning does not stay where the founder left it.
Technological
Patagonia’s specification power has done what specification power can do. Recycled content reached 93% of polyester and 89% of nylon. It zeroed intentionally added PFAS in new styles from Spring 2025.
That PFAS decision deserves attention, because California’s AB 1817 and New York’s apparel ban both carve out severe-wet-weather outdoor gear until January 1, 2028. Patagonia gave up its own grace period roughly three years early, in the exact product category where the chemistry trade-off is hardest, and now sells wet-weather shells against competitors still allowed to use the older finish. Leading a technology transition means eating the performance gap before your rivals have to.
Where specification runs out is upstream supply. Synthetics made from secondary waste sit at 6% against a 50% target, because textile-to-textile fiber recycling does not exist at commercial scale. Between 85% and 90% of Patagonia products have no end-of-life solution at all. No purchase order fixes either problem.
The EU is building the infrastructure that would make durability legible. The ESPR working plan schedules a textiles delegated act for around 2027, with digital product passport obligations following roughly eighteen months later. When it lands, brands will have to publish material composition, tier-two traceability and repairability data. Patagonia already publishes its full factory list. That advantage arrives in 2028 or 2029.
Legal
The legal section is where the asymmetry gets sharp.
| Instrument | What it binds | Applies to Patagonia? | Bites |
|---|---|---|---|
| EU ECGT (Directive 2024/825) | Environmental claims and labels | Yes | Sep 27, 2026 |
| California SB 253 | Scope 1, 2 emissions disclosure | Yes, revenue above $1B | Nov 10, 2026 |
| California SB 261 | Climate risk report | Yes, revenue above $500M | Enjoined |
| California SB 707 | Textile EPR fees and data | Yes | Registered Jul 1, 2026 |
| California AB 1817 / NY ECL 37-0121 | PFAS in textiles | Yes | In force; 50 ppm Jan 2027 |
| EU CSDDD (post-Omnibus) | Supply chain due diligence conduct | No | Jul 26, 2029 |
| FTC Green Guides revision | US environmental claims | Yes, when it exists | Pending since 2022 |
Patagonia falls outside CSDDD on both tests. It has 3,716 employees against a 5,000 threshold and $1.47 billion of global revenue against an EUR 1.5 billion EU-turnover test. Nike and adidas sit inside. So the mandatory due diligence regime that would have obliged Patagonia’s largest rivals to build what Patagonia spent twenty years building now arrives in 2029, without the EU-wide civil liability that gave it teeth, and Patagonia gets no compliance credit for being early because it was never in scope.
Meanwhile the ECGT reaches every trader. From September 27, 2026 it bans generic claims, bans product-level carbon-neutrality claims that rest on offsetting, and bans sustainability labels that do not rest on a certification scheme or a public authority. B Lab rebuilt the entire B Corp standard partly to survive that provision, replacing the old 80-point assessment with seven mandatory impact topics and third-party audit, and told EU-facing B Corps to submit for audit by mid-2026.
The US federal position is a vacuum. The FTC opened its Green Guides review in December 2022 and has published nothing. States filled the gap, which is why at least eighteen of them now restrict PFAS in consumer products and why plaintiff firms started sending demand letters in 2026. Patagonia’s own claims are the most testable in the industry, because it publishes the underlying numbers. Precision creates a target.
Environmental
Patagonia’s FY2025 report shows emissions rising 2%, against a stated need to cut roughly 10% every year to reach net zero by 2040. Roughly 99% of those emissions sit inside businesses Patagonia does not own.
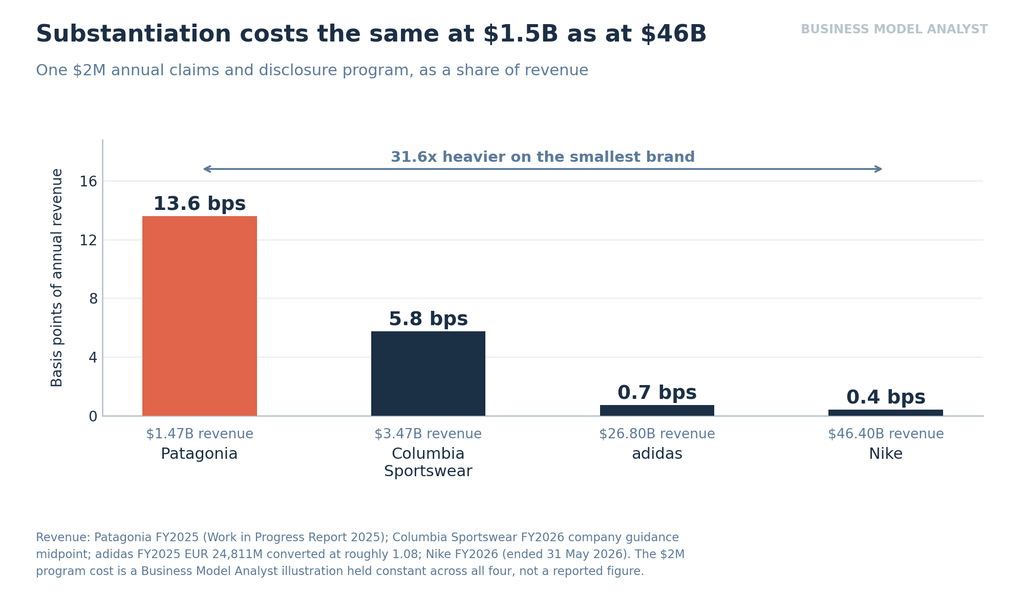
Compound that 10% for fifteen years and you land at 20.6% of the FY2025 base, not zero. “Net zero” carries the difference, which means removals or offsets for a fifth of today’s footprint. The ECGT bans offset-based neutrality claims at product level from September 27, 2026. Patagonia can still buy removals; it will have a harder time saying so on a hangtag in Europe.
The FY2025 miss costs less than it looks. One year at +2% raises the run rate required over the remaining fourteen years from 10.0% to about 10.8%. A second and third miss is what compounds.
Then there is physical risk. Patagonia’s finished-goods base sits in eleven Asian countries exposed to heat, flooding and cyclone disruption, and its product mix skews to insulated outerwear sold into warming Northern Hemisphere winters. Climate change is a cost line on both ends of this business.
Where this analysis could be wrong
Three counterarguments deserve a hearing.
The ECGT is a moat, not a tax. A rule that bans vague green claims destroys competitors’ cheap marketing and leaves substantiated claims standing. Patagonia has the receipts. Fair, and it may prove the dominant effect in Europe. The counterweight: enforcement runs post-market through national consumer authorities, and a famous brand with published numbers makes a better test case than an anonymous one.
CSDDD scope is a gift. Staying out of a compliance regime while Nike and adidas fall inside it looks like a competitive win. It is, on cost. It is not, on signal. When rivals publish audited due diligence because the law demands it, Patagonia’s voluntary version stops distinguishing anything.
Patagonia does not need to grow. With no shareholders, the company can absorb a margin hit that a listed competitor could not. True, and it is the strongest thing in this analysis. The limit is that the absorbed cost comes out of the Holdfast grant, so a compliance dollar is a conservation dollar.
What a founder should take from this
Three transferable lessons.
Regulation arrives on your speech before it arrives on your operations, because writing a disclosure rule is cheaper for a legislature than writing a conduct rule and survives lobbying better. If your differentiation lives in what you claim, price the substantiation, not the claim.
Compliance is a fixed cost, which makes it regressive. Any rule written per company transfers advantage to the largest company in the category. Audit which of your obligations scale with revenue and which do not.
Being early buys goodwill, not legal credit. Patagonia dropped PFAS three years before its category deadline and gets no regulatory benefit for it. Voluntary standards become table stakes the moment they become mandatory for someone else.
FAQ
Is regulation good or bad for Patagonia in 2026? Mixed, and the timing decides it. The rules governing claims and disclosure bind within fifteen months and apply to Patagonia in full. The rules governing supply chain conduct arrive in 2029, exclude Patagonia on size, and lost their civil liability regime in the February 2026 Omnibus.
Does the EU Green Claims Directive still apply? No. The Commission announced its withdrawal in June 2025. The Empowering Consumers for the Green Transition Directive, a separate and already adopted instrument, applies from September 27, 2026 and carries most of the substance.
How much do tariffs cost Patagonia? The company does not disclose it. Applying the Section 301 forced-labor tier of 10% to 12.5% to a modeled US import base gives a range of roughly $22 million to $39 million a year on top of normal apparel duties.
Is Patagonia in scope for California’s climate disclosure laws? Yes on revenue. SB 253 covers companies above $1 billion doing business in California, and CARB reset the first Scope 1 and 2 deadline to November 10, 2026. SB 261, which covers companies above $500 million, remains enjoined by the Ninth Circuit.
Who owns Patagonia? The Patagonia Purpose Trust holds 2% of the stock and all voting control. The Holdfast Collective, a 501(c)(4), holds the remaining 98%. See our Patagonia business model breakdown for how that structure routes profit.
What is the biggest external threat? Not any single rule. The combination of a claim-heavy brand, a fixed compliance cost base and a $1.47 billion revenue line to absorb it, arriving at the same time as a tariff regime that ignores the labor spending Patagonia’s brand is built on.
The Business Model Analyst Take
Patagonia built a fifty-year advantage by voluntarily doing things regulators had not yet required. That advantage was always going to decay in one of two ways: the rules would catch up and commoditize it, or the rules would stall and reward the free riders.
2026 delivered a third outcome nobody planned for. The conduct rules stalled, and the speech rules did not. Brussels dropped the directive that would have made Nike and adidas prove their supply chains, kept the directive that polices what any brand may print on a hangtag, and set the due diligence deadline three years out with the liability clause removed. California did the same in miniature, requiring Patagonia to publish its emissions in November while deferring the eco-modulated EPR fees that would pay it for building repairable products until 2028.
The result is a company being asked to document a differentiation the market is no longer forcing anyone else to build. Its per-firm labor diligence earns nothing at the border, where the tariff is set by country. Its published numbers make it the easiest greenwashing case in the industry to test. Its compliance bill lands at 31.6 times the revenue intensity Nike carries for identical work.
None of that is fatal. Patagonia answers to a trust rather than to shareholders, which means it can pay costs a listed rival would refuse. But that money has one alternative use, and it is the grant to Holdfast. For the next three years, every dollar Patagonia spends proving it is what it says it is comes out of the conservation budget. That is the trade this macro environment is forcing, and no PESTLE written before February 2026 sees it.