Brussels waved through the biggest media merger in a decade. A US courtroom is the only thing still standing between Paramount and a 200-million-subscriber streaming empire.
The European Union approved Paramount Skydance’s $81 billion takeover of Warner Bros. Discovery on July 22, 2026, after Paramount agreed to unwind a film-distribution venture it shared with Universal. The clearance removes one of the deal’s biggest international obstacles. It does nothing about the US court order and the twelve-state antitrust lawsuit still blocking the deal from closing.
Here is the part that gets lost in the “biggest merger ever” headlines: winning the regulators was always the solvable problem. Paramount can negotiate concessions, sell off a joint venture, promise to behave for ten years. What it cannot negotiate with is a federal judge who has already hit pause, or a prize that may not be worth the roughly $54 billion in debt it takes to buy.
What Happened
The European Commission cleared Paramount’s acquisition of Warner Bros. Discovery on Wednesday, ruling that the deal could go ahead so long as Paramount fully honors the commitments it offered. Those commitments were specific and structural. Paramount agreed to terminate its stake in United International Pictures, the film-distribution joint venture it runs with Universal Pictures across the European Economic Area, within 13 months of the deal closing. It also pledged not to strike any film co-distribution agreement with Universal’s parent, NBCUniversal, in the region for ten years.
The Commission’s reasoning was narrow. It concluded that enough studios would remain competing in film production across Europe, so its real worry was distribution. Paramount’s concessions addressed that worry, and the deal cleared.
That makes the EU the second major regulator to step aside. The US Department of Justice closed its own investigation in June without demanding a single concession. On paper, the two biggest antitrust gatekeepers in the Western world have now both blinked.
The Backstory
This deal exists because Paramount muscled its way into someone else’s wedding.
Warner Bros. Discovery spent much of 2025 shopping itself after years of disappointing results and a heavy debt load. In December 2025, it agreed to sell its studio and streaming businesses to Netflix. That deal was signed. Then Paramount Skydance, the company David Ellison assembled after merging Skydance with the old Paramount Global in 2024, showed up three days later with an all-cash counteroffer and refused to leave.
What followed was a bidding war Netflix ultimately declined to win. Paramount raised its offer to $31.00 per share in cash, backed by roughly $41 billion in equity from the Ellison family and RedBird Capital and about $54 billion in debt from Bank of America, Citi, and Apollo. It agreed to cover the $2.8 billion breakup fee Warner owed Netflix, and layered on a $7 billion regulatory termination fee as insurance. Netflix walked. In February 2026, the Warner board flipped, and the deal was on.
The total enterprise value lands near $110 billion once debt is counted. That is the number that matters, and it is the number the “biggest media merger” coverage keeps burying.
The Plan
Ellison’s thesis is scale. Combine Paramount+ and HBO Max, he told analysts, and you get a platform with more than 200 million direct-to-consumer subscribers across 100-plus countries, big enough to “compete effectively with the leading streaming services.”
The logic is not crazy. Streaming is a fixed-cost business. Content is expensive to make and cheap to distribute one more time, so the more subscribers you spread that content spend across, the better the math works. Legacy media does not have a growth problem so much as a scale problem, and consolidation is the blunt instrument that fixes it.
So the plan is to fold two streaming services, two of Hollywood’s oldest studios, HBO, CBS, CNN, and a wall of cable networks under one roof, cut the overlap, and point the combined weight at Netflix. Ellison has already signaled he wants to keep the HBO brand intact inside the merged app rather than blowing it up, a nod to how badly the last owner mangled that exact rebrand.
The Business Model Angle
Here is where the story turns, and where the chart matters. That “200 million subscribers” figure is a marketing number. It counts every Paramount+ account and every HBO Max account as separate people, when a large share of subscribers pay for both. Strip the double-counting and the honest combined tally is closer to 219.6 million total subscriptions.
That number does something inconvenient. It puts the merged giant in a statistical dead heat with Disney’s 219.8 million across Disney+, Hulu, and ESPN+, and it leaves both of them roughly 100 million subscribers behind Netflix’s 325 million-plus. In other words, the biggest media merger in a generation buys Paramount a tie for second place. It does not buy first.
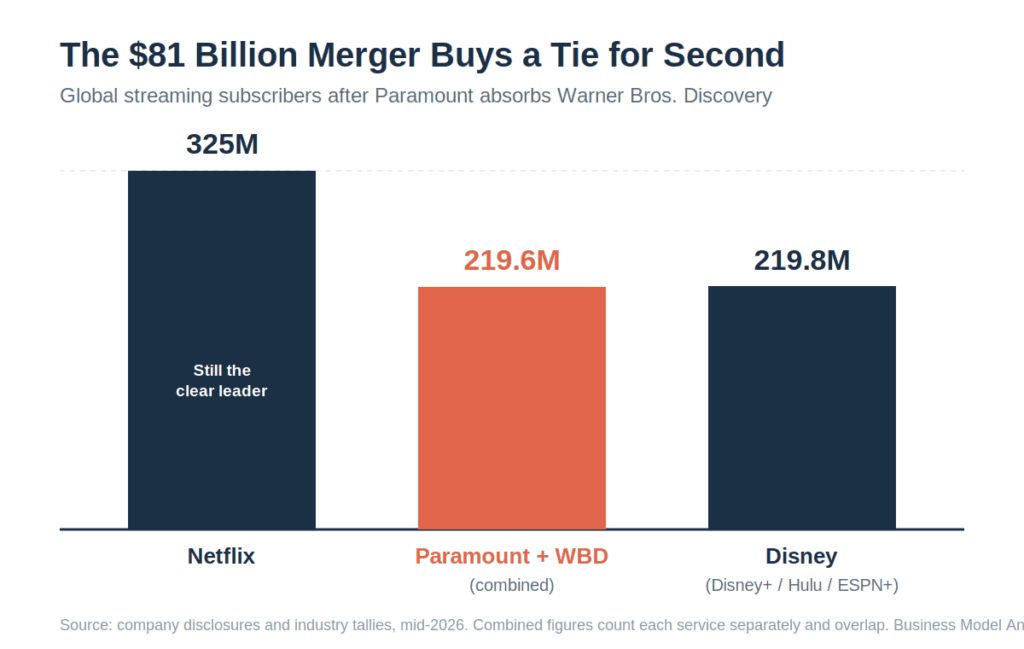
Now stack the balance sheet against that. Paramount Skydance posted a net loss in 2025 on revenue of about $29 billion. The company is taking on roughly $54 billion in fresh debt to win a subscriber base that lands it next to Disney, not ahead of Netflix. Scale is real, but scale bought on this much leverage only works if the combined platform can lift revenue per subscriber and hold onto members through a messy app migration. Netflix, meanwhile, is the only streamer in the industry reliably printing profit, and it is not standing still.
If you want the counter-case for why scale is still the right bet, it lives in the twelve-state lawsuit breakdown: in a business with high fixed costs and thin differentiation, size genuinely is the model. Both things can be true. Scale is necessary and scale is not sufficient.
The Risk
The regulators were the easy part. The hard part is a US courtroom.
A dozen states, led by names like California and New York, have sued to block the merger on antitrust grounds. On Monday, a California federal judge granted a 14-day restraining order that flatly prohibits the companies from closing. In the United Kingdom, Culture Secretary Lisa Nandy has said she is “minded to intervene” on public-interest grounds. So while Brussels and the DOJ have cleared out, the deal still cannot legally close.
And the clock is the real weapon. Starting after September 30, 2026, Paramount owes a ticking fee of about $0.25 per share each quarter the deal stays open, which works out to roughly $650 million every three months. Every week a judge keeps the deal frozen is a week that fee compounds against a company already loading up on debt. “Eventually” is probably still the base case for this merger closing. But eventually has rarely been this expensive.
There is also the ghost in the room: AT&T bought Time Warner in 2018 on a similar scale-through-consolidation logic, drowned in debt and integration pain, and spun it back out four years later at a loss. The HBO asset at the center of this deal is the same one that broke last time. Ellison is betting he runs the playbook better. History is not on his side.
Quick Questions
Did the EU approve the Paramount Warner Bros. deal? Yes. On July 22, 2026, the European Commission cleared the acquisition, conditional on Paramount honoring commitments including terminating its United International Pictures distribution venture with Universal in Europe within 13 months of closing.
Is the deal now allowed to close? No. A US federal judge in California issued a 14-day restraining order on July 20, 2026, blocking the deal, and a twelve-state antitrust lawsuit is still active. UK regulators may also intervene.
How big is the combined company? About $81 billion in equity value, or roughly $110 billion counting debt. The merged streaming business would have around 219.6 million total subscriptions, second to Netflix’s 325 million-plus.
Who owns Paramount Skydance? Control sits with David Ellison and Larry Ellison, with RedBird Capital as a minority partner. David Ellison is chairman and CEO.
Why did the EU require concessions? The Commission was concerned about film distribution in Europe, specifically Paramount’s joint venture with Universal. Ending that venture and pledging no similar deal for ten years resolved the concern.
The Business Model Analyst Take
Strip away the “largest media merger” framing and this is a leveraged bet that scale cures streaming economics. It might. Legacy media really does have a scale problem, and a combined Paramount-WBD really is a more serious competitor than either half alone.
But the numbers should temper the triumphalism. The deal buys a tie for second, not a shot at first, and it does so with roughly $54 billion of debt strapped to a company that lost money last year. The winner of the streaming wars is not whoever assembles the most subscribers. It is whoever converts them into durable, profitable engagement, and on that metric Netflix is not just ahead, it is the only one keeping consistent score.
The tell to watch is not subscriber count. It is churn during the app migration and revenue per user afterward. If Ellison can hold members and lift yield while folding two libraries into one product, this becomes the rare consolidation that worked. If subscribers bleed out during the transition, this is AT&T and Time Warner with a fresh coat of paint. Regulators just cleared the runway. Whether there is a plane worth flying is a business-model question, and that answer will not come from Brussels.