Paramount wanted to close this week. Instead a federal court hit pause, and the real fight now comes down to one deceptively simple question: what business is Paramount actually in?
A federal judge on Monday temporarily blocked Paramount from completing its $111 billion purchase of Warner Bros. Discovery, siding for now with 12 states that sued to stop it. The 14-day restraining order freezes a deal Paramount hoped to close by July 22, and sets up an August 3 hearing that could stall the merger for months.
The clock Paramount built to force this deal through is now ticking against a deal that cannot move.
When Paramount agreed to buy Warner Bros. Discovery, it wrote a penalty into the contract to keep everyone motivated: if the transaction is not wrapped by September 30, Paramount owes Warner shareholders roughly $7 million a day, more than $600 million a quarter. That fee was supposed to be leverage. As of Monday, it is a liability attached to a merger a court will not let close.
What Happened
Judge Araceli Martínez-Olguín of the U.S. District Court for the Northern District of California granted a temporary restraining order barring Paramount and Warner Bros. Discovery from closing the deal or taking any step to integrate operations. The order runs 14 days and can be extended to 28. A hearing on the states’ request for a preliminary injunction, the ruling that would actually freeze the deal for the length of the lawsuit, is set for August 3.
The judge’s language mattered more than the pause itself. She wrote that the states had raised “serious questions going to the merits,” and that the public interest in antitrust enforcement tipped the balance toward blocking. Translated out of legalese: a court just decided the states’ theory is credible enough to stop one of the largest media deals in history in its tracks.
Paramount, notably, did not fight hard. It had already offered to delay closing to mid-August, and in a statement called itself “grateful for the court’s swift order,” framing the pause as simply preserving the status quo. But it drew a hard line on the underlying case, insisting the states’ antitrust arguments have “no basis in modern market realities.”
That phrase is the whole ballgame.
The Backstory
The striking part is who brought this fight. The U.S. Department of Justice already cleared this merger back in June. Regulators in Australia and China signed off too. By the normal playbook, a deal with federal antitrust clearance is close to home free.
Instead, a coalition of 12 Democratic state attorneys general, led by California’s Rob Bonta, filed suit on July 13 to block it anyway, citing Section 7 of the Clayton Antitrust Act. This is the newer wrinkle in dealmaking: state AGs stepping into the gap when Washington waves a deal through. Bonta called Monday’s order a “critical first win” in a case aimed at ensuring the merger “never sees the light of day.”
The deal itself would hand David Ellison, son of Oracle billionaire Larry Ellison, control of a media empire stitched together from two of Hollywood’s five remaining major studios, the streaming services HBO Max and Paramount+, and the news networks CBS and CNN under one roof.
The Plan
Paramount’s strategy has two moving parts, and they are now in tension.
The first is speed. Close before September 30, dodge the ticking fee, and start capturing the roughly $6 billion in promised cost synergies. The second is the legal defense: argue that in a world of Netflix, Amazon, and YouTube, old-fashioned market definitions like “wide-release theatrical films” are relics. On Paramount’s telling, this is not a giant swallowing a rival. It is two struggling legacy players combining so they can survive the streaming era at all.
That survival argument is not spin. It is the actual logic of the deal. In a business with high fixed content costs and thin differentiation, scale stops being a vanity metric and becomes the moat.
The Business Model Angle
Here is the part every founder should sit with, because it is a clean lesson in how markets get defined and why it decides everything.
This entire case turns on one question: which market is Paramount competing in? Both sides have a completely defensible answer, and they lead to opposite conclusions.
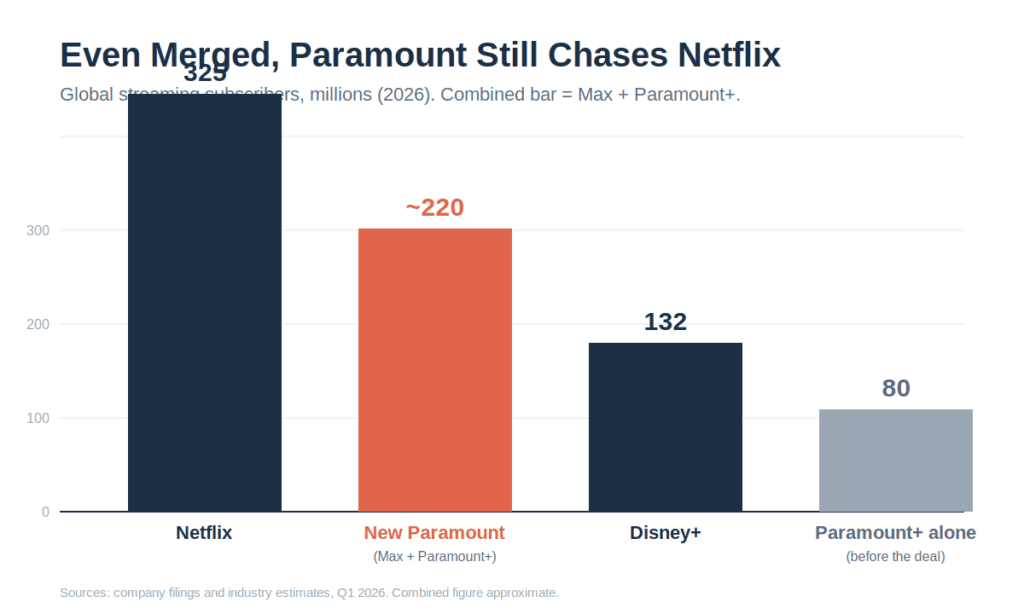
Frame it as streaming, and Paramount looks like an underdog. Even after absorbing Warner Bros., the combined streaming operation lands around 220 million subscribers, still a distant second to Netflix’s 325 million and only roughly level with Amazon. In that market, this merger produces a stronger challenger, not a monopoly.
Frame it as theatrical film distribution and basic cable, which is exactly what the states did, and the picture inverts. The complaint alleges that post-merger, four companies would control more than 90% of blockbuster distribution, taking the majors from five down to four at the very top of the market. That is the kind of concentration number that makes antitrust lawyers reach for the structural presumption, the legal shortcut that says a market this consolidated is presumed harmful.
Same company. Same deal. Two market definitions, two verdicts. The court is not really refereeing a merger. It is deciding which business Paramount is allowed to say it is in.
And this is the trap that defines legacy media right now. Scale is the only survival strategy left in a fixed-cost, low-differentiation business. But the scale that saves you in streaming is the same scale that triggers antitrust in theatrical. The move that keeps you alive is the move that invites the challenge.
The Risk
For Paramount, the meter is running in the worst possible way. Every day the deal sits frozen is a day closer to that September 30 deadline, and the ticking fee is now a cost with no offsetting progress. Underneath it sits a balance sheet already stretched: the combined company is projected to carry close to $80 billion in net debt, around 6.5 times earnings, serviced largely by cable networks shrinking nearly 10% a year while the streaming payoff analysts expect is still five or more years out.
There is also precedent working against them. A separate media deal, the $6.2 billion Nexstar-Tegna tie-up, was already paused by a similar state-driven lawsuit and a granted injunction. State-AG antitrust is not a long-shot tactic anymore. It is a proven one.
The broader risk is structural. If a coalition of states can freeze a federally cleared merger, then federal approval stops being the finish line for any large deal. Every future megamerger inherits a second gauntlet, and the calendar becomes the weapon.
Quick Questions
What did the judge actually rule? She granted a temporary restraining order that blocks Paramount from closing the deal or integrating operations for 14 days, and found the states raised “serious questions” worth a fuller hearing.
How long is the deal frozen? The order lasts 14 days and can stretch to 28. The bigger decision comes at an August 3 hearing on a preliminary injunction, which could hold the deal for the length of the lawsuit, potentially months.
Why are states suing if the DOJ already approved it? Federal clearance does not bind state attorneys general. These 12 states are using their own authority under the Clayton Act to challenge a deal Washington chose not to block.
Why does the delay cost Paramount so much? A contract clause requires Paramount to pay Warner shareholders about $7 million a day, over $600 million a quarter, if the deal is not closed by September 30.
Could the merger still go through? Yes. Paramount can defend the case, appeal, or reach a settlement, and it has already secured federal and several international approvals. The August 3 ruling is the next real signal.
The Business Model Analyst Take
The headline is a court freezing a merger. The lesson is about market definition, and it is one of the most underrated forces in business strategy.
Paramount’s entire defense rests on drawing its market as wide as possible: we are a small fish in the streaming ocean. The states’ entire case rests on drawing it as narrow as possible: you are a giant in theatrical and cable. Whoever wins that definitional fight wins the case, because in antitrust, the market you are judged in determines whether you are a survivor or a threat.
That is not a media-industry quirk. It is the question sitting under every consolidation play in every maturing industry. When growth stalls and fixed costs dominate, scale becomes the last available moat, and companies merge to get it. But the same merger looks like survival from inside the boardroom and like monopoly from inside a regulator’s market definition. Both can be true at once.
For founders and operators, the takeaway is sharper than “antitrust is a risk.” It is this: your regulatory exposure is set less by what you do than by how narrowly someone can define the market you do it in. In a consolidating industry, the winning strategic move and the move that draws the lawsuit are frequently the exact same move. Paramount is about to find out which one this was.