
David Ellison promised no cost cuts and no asset sales. The math behind $80 billion in debt says otherwise.
Paramount Skydance will close its $81 billion Warner Bros. Discovery deal carrying roughly $80 billion in net debt, about 6.5 times EBITDA. The catch: the cable networks that generate most of the cash to service that debt are shrinking nearly 10% a year, while the streaming payoff analysts expect is at least five years out.
David Ellison unveiled the Warner deal as the start of a new golden era for Hollywood, built on scale, technology, and a promise to put at least 30 movies in theaters a year. The pitch was ambition. The balance sheet is a different story. When a company borrows this much against a business that is contracting on schedule, the strategy stops being about content and starts being about timing.
What Happened
Paramount is set to emerge from its Warner Bros. Discovery acquisition with close to $80 billion in net debt, a load projected to equal roughly 6.5 times annual earnings before interest, taxes, depreciation, and amortization once the deal closes, which could happen as soon as this month. Analysts at MoffettNathanson called the figure staggering in a note published shortly after the deal was struck.
The combined company will house two of Hollywood’s founding studios, plus CNN, CBS, MTV, and Nickelodeon, and a streaming operation stitched together from Paramount+, Pluto TV, and HBO Max. Paramount projects about $69 billion in annual revenue, roughly $18 billion in adjusted EBITDA after synergies, and a content budget north of $30 billion at closing.
The credit market has already registered its verdict. Fitch Ratings cut Paramount Skydance’s debt to junk status in early 2026, citing limited visibility into the post-deal capital structure. Ellison, meanwhile, has promised there will be no asset sales and no cuts to content spending. The Justice Department has cleared the deal, and the company is still seeking regulatory sign-off in Europe.
The Backstory
This deal exists because Ellison outlasted a bidding war. In February 2026, Netflix and Paramount were both chasing Warner’s studio and streaming assets. Netflix walked on February 26. One day later, Paramount signed a definitive agreement at $31.00 a share, valuing Warner’s equity at roughly $77 billion and the whole transaction, debt included, at more than $111 billion. The DOJ later cleared that $111 billion deal, removing the biggest regulatory hurdle.
To fund it, the Ellison family and RedBird Capital committed around $47 billion in equity, and a syndicate of 18 banks and financial institutions, including Citigroup, Bank of America, Apollo, and JPMorgan, put up roughly $50 billion in debt financing. On top of the new borrowing, Paramount inherits about $33 billion of debt already sitting on Warner’s books. Add it up and you get the near-$80 billion figure hanging over the combined company.
Both sides arrive at this deal already lean. Warner spent years under former CEO David Zaslav cutting its way toward lower leverage, laying off thousands and scrapping high-profile projects along the way. Paramount has run through its own repeated cost-cutting cycles, before and after Skydance took control. Many current and former Warner executives say the obvious savings are already gone, which raises an uncomfortable question about where the next round comes from.
The Plan
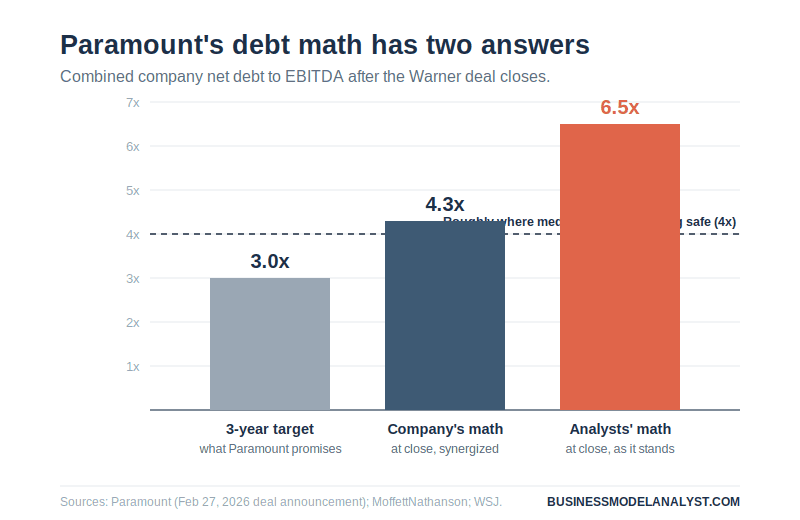
Paramount’s answer is synergies. The company has told investors it will extract about $6 billion in cost savings within three years and bring net leverage down to three times EBITDA over the same window. Most of those savings are supposed to come from consolidating the two companies’ streaming technology platforms and eliminating overlapping operations, a process the company acknowledges will result in significant job cuts.
The growth side of the plan is the streaming roll-up. By folding Paramount+ and Pluto TV together with Warner’s HBO Max, Ellison is betting he can build a service large enough to compete with Netflix and Disney on subscriber scale and content spend. Publicly, Paramount frames the whole exercise as offense, not defense. “This transaction is premised on growth, not cost-cutting,” the company said, calling the approach the same proven playbook it has run at Paramount.
The Business Model Angle
Here is the tension the golden-era pitch glosses over. Paramount is borrowing a fixed, senior claim of $80 billion against a business whose cash flows are in structural decline. The network holdings, including CNN, CBS, MTV, and Nickelodeon, still throw off around $35 billion a year, but Moody’s estimates that revenue will fall at an average rate of nearly 10% annually for the foreseeable future. Debt does not shrink with cord-cutting. The collateral does. That means the leverage ratio gets worse on its own, even if management does nothing, because the denominator keeps contracting.
There is also a quiet gap in how the debt gets described. When the deal was announced, Paramount pointed to net leverage of 4.3 times EBITDA on a fully synergized basis. Analysts looking at the balance sheet as it actually stands put the figure at 6.5 times. The difference between those two numbers is the $6 billion in synergies, and synergies are a promise, not cash in the bank. The market is pricing the 6.5, not the 4.3, which is why the debt is rated junk. And junk pricing matters: on an $80 billion balance, even a modest premium in borrowing costs runs into hundreds of millions a year.
Then there is the timing mismatch, which is the real heart of the bet. Moody’s estimates it will take at least five years before the combined streaming business earns at the scale of the legacy TV operation. So for roughly half a decade, Paramount has to service junk-rated debt using cash from the shrinking side of the house while it waits for the growing side to catch up. This is consolidation as a survival strategy, not a growth strategy. In a fixed-cost business with thin differentiation, scale stops being a vanity metric and becomes the actual moat, which is exactly why Ellison is willing to lever up to get it.
The last piece is the rhetorical one. Ellison promises no asset sales and no content cuts, while the synergy math depends entirely on eliminating overlap and consolidating platforms. You cannot pull $6 billion out of two merged companies by leaving everything in place. The “growth, not cost-cutting” line and the “$6 billion in synergies” line cannot both be fully true, and the balance sheet will eventually decide which one gives.
The Risk
The biggest near-term risk is what nobody has seen yet. Until the deal closes, Paramount has only a partial view of Warner’s operations. Warner learned this lesson the hard way after its own 2022 merger, when Discovery executives uncovered the costs of the short-lived streaming service CNN+ only after taking control. Buying a company this size with restricted access to its books means the real number could be worse than $80 billion.
The assets meant to pay down the debt are themselves under pressure from cord-cutting and ad declines. The content business adds its own volatility, since a single box-office miss can raise the cost of capital on an entire franchise, not just one film. Sports-rights costs keep climbing, and the streaming market is more competitive than ever, including from a Netflix that walked away from this same deal and is now free to spend its firepower elsewhere.
There is also a clock. Under the deal terms, a ticking fee kicks in if the transaction has not closed by the end of September, a cost S&P Global estimated could run around $650 million a quarter. That creates pressure to close fast, which is not always the same as closing carefully.
Quick Questions
How much debt will the combined Paramount-Warner company have?
Roughly $80 billion in net debt, or about 6.5 times annual EBITDA, a level analysts consider high for a media company.
Why is the debt a problem if the company is so large?
Because most of the cash used to service it comes from cable TV networks, and Moody’s expects that revenue to fall nearly 10% a year for the foreseeable future. The debt is fixed while the cash flow behind it shrinks.
Did Paramount promise layoffs?
Not directly. Ellison promised no asset sales and no content cuts. But the plan calls for $6 billion in synergies from consolidating streaming platforms and eliminating overlap, which the company admits will mean significant job cuts.
Is the deal approved and when does it close?
The Justice Department has cleared it, and European regulators are still reviewing it. Paramount expects the deal to close as soon as this month.
What did the rating agencies say?
Fitch cut Paramount Skydance’s debt to junk status in early 2026, and MoffettNathanson called the projected leverage staggering. Both flagged the gap between the plan and the balance sheet.
What is Paramount’s plan to bring the debt down?
Deliver $6 billion in synergies and cut leverage to three times EBITDA within three years, while merging Paramount+, Pluto TV, and HBO Max into a larger streaming service. MoffettNathanson called the three-year target too optimistic.
The Business Model Analyst Take
The Warner deal is sold as a bet on content, but it is really a bet on time. Ellison is borrowing against a business that shrinks predictably to fund a business that grows unpredictably, and the whole thesis rests on the second one arriving before the first one gives out. If synergies land on schedule and the combined streamer scales, this looks visionary in five years. If either slips, $80 billion of junk-rated debt sitting on a melting EBITDA base is precisely how a company with good assets turns into a forced seller. Which is worth remembering, because “no asset sales” is exactly the kind of promise that leverage tends to break. The most interesting number in this deal is not the $81 billion price or the 30 movies a year. It is the five years Paramount has to survive before the math is supposed to work.
Based on reporting from The Wall Street Journal, with additional data from Paramount’s February 27, 2026 deal announcement, MoffettNathanson, Moody’s Ratings, Fitch Ratings, and S&P Global.