
Paramount Skydance spent eight months convincing the Trump administration that swallowing Warner Bros. Discovery would be good for Hollywood. On June 12, it worked: the Justice Department’s Antitrust Division closed its review and declined to challenge the deal. David Ellison had his clearance. The largest media merger in Hollywood history was, by all appearances, a formality away from closing.
Then, on Monday, July 13, a coalition of 12 state attorneys general led by California’s Rob Bonta filed suit in the U.S. District Court for the Northern District of California to stop it. That evening, they went further and filed an emergency motion for a temporary restraining order and preliminary injunction, asking the court to act by July 22.
Federal antitrust enforcement stood down. The states did not. That gap is the whole story, and it is about to become an expensive one for Paramount.
What Happened
The lawsuit alleges the $111 billion acquisition violates Section 7 of the Clayton Act, the 1914 statute that prohibits mergers likely to substantially lessen competition or tend to create a monopoly. Bonta announced it standing in front of the Hollywood sign, calling antitrust enforcement “democracy’s check on oligarchy” and arguing the deal would drive up prices, degrade content quality, and shrink the annual output of films and shows.
The coalition is California, Arizona, Colorado, Connecticut, Massachusetts, Minnesota, Nevada, New Jersey, New Mexico, New York, Oregon, and Washington. All are led by Democratic attorneys general, which is a fact the deal’s defenders have already seized on.
The states asked Paramount and Warner Bros. to voluntarily hold off on closing until the case is resolved. The companies declined. So the states filed for a TRO the same night.
Paramount’s response was immediate and unusually sharp. The company said the suit, “in the most generous light, reflects a fundamentally flawed application of the antitrust laws and is wrong on both the facts and the law.” It has promised to fight.
Key Numbers
| Metric | Figure |
|---|---|
| Deal value | ~$111 billion (roughly $31 per WBD share, all cash) |
| DOJ clearance | June 12, 2026, after an eight-month review |
| States suing | 12, led by California AG Rob Bonta |
| Statute invoked | Section 7, Clayton Act |
| Ticking fee | $0.25 per WBD share per quarter, starting Sept. 30, 2026 |
| Cost of that fee | ~$650 million per quarter, or ~$7 million per day |
| Merger outside date | March 4, 2027, extending to June 4, 2027 if antitrust review is pending |
| TRO deadline requested | July 22, 2026 |
| Netflix termination fee already paid | $2.8 billion |
The Three Markets at the Heart of the Case
The states did not sue over CNN. This matters, and it is where a lot of the commentary has gone wrong.
The complaint defines three relevant markets, all of them entertainment and distribution, none of them news:
- Wide-release theatrical film distribution. The market for getting films into thousands of screens at once.
- Anticipated top-grossing theatrical film distribution. Effectively the blockbuster market, where studios bid for the tentpoles that anchor a theater’s calendar.
- Basic cable television channel licensing. The bundle negotiations where a programmer sells a package of channels to a distributor.
The theory of harm on cable is the most concrete thing in the filing. Post-merger, a distributor that refuses the combined company’s fee demands would risk losing CNN, Nickelodeon, Cartoon Network, HGTV, Food Network, TNT, and TBS in a single stroke. The states argue distributors would have little choice but to pay, and that those fees land on consumer bills.
Movie theaters agree. Cinema United, the exhibitor trade group, welcomed the lawsuit. Fewer studios means fewer films, thinner release calendars, and less negotiating leverage for a theatrical business that has spent five years fighting for its life.
The Concentration Math the States Are Betting On
The complaint’s numbers are the case. Here is what the states allege the industry looks like the day after closing.
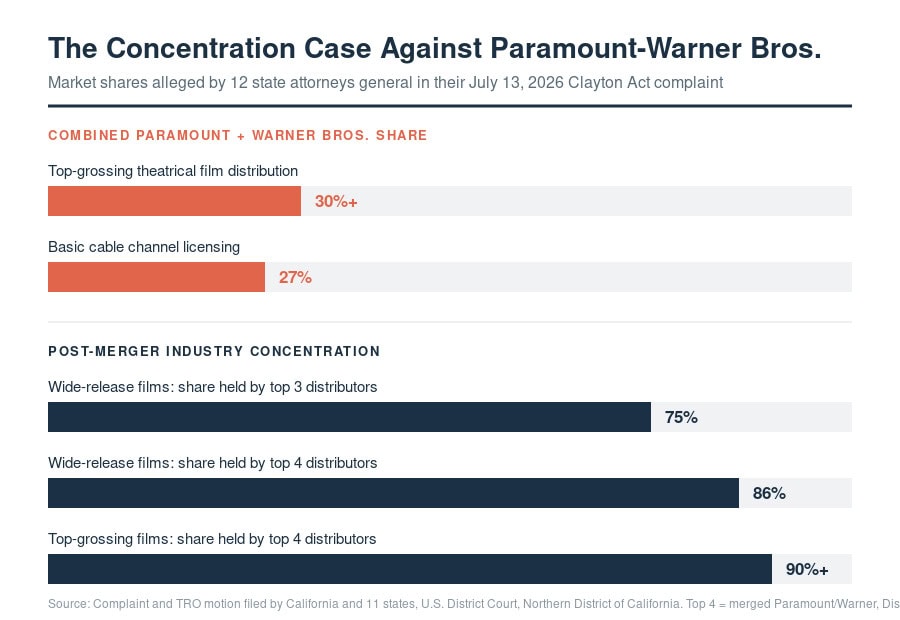
The structural argument is straightforward: this merger takes five major studios down to four, and it does so at the top of the market rather than the bottom. In blockbuster distribution, the states claim four companies would control more than 90% of films. That is the kind of number that makes antitrust lawyers reach for the structural presumption.
Whether a judge agrees that “anticipated top-grossing theatrical film distribution” is a real market, as opposed to a gerrymandered one built to produce a scary share, is the entire ballgame.
The Clock Is the Real Weapon
Here is the part that should interest anyone who cares about deal structure more than deal politics.
Paramount agreed to a ticking fee. Starting September 30, 2026, WBD shareholders collect $0.25 per share per quarter for every quarter the deal has not closed. That works out to roughly $650 million a quarter, or about $7 million a day.
Paramount put that fee in the offer as a signal of confidence. It was a way of telling WBD’s board that Paramount’s regulatory path was cleaner than Netflix’s, and it was willing to bet real money on speed. It worked. WBD took the money.
Now that same clause is a loaded gun pointed at Paramount’s own balance sheet, and the states know it. Their TRO motion says so almost gleefully. They point out that the merger agreement contemplates an outside date of March 2027, extendable to June 2027 if antitrust review is still pending, which means the parties themselves budgeted for more than eight months of accumulated ticking fees as the price of a deal that might draw scrutiny. Their conclusion: “Paramount’s interest in completing the Transaction now to spare it the costs of its own agreement is not a cognizable equity interest.”
Translated: you priced this risk yourself, so stop telling the court that delay is unfair.
A Reuters review found comparable federal merger cases take an average of eight months to reach a decision. Eight months of ticking fees is well north of $1.5 billion, on top of a deal already financed with heavy debt and an Ellison family equity guarantee, and on top of the $2.8 billion Paramount already paid Netflix to break the prior agreement.
Paramount’s Defense
Paramount’s counterargument is the one every horizontal media merger has made since roughly 2018, and it is not stupid.
The company says the relevant market is not “five studios.” It is the global attention economy, where Netflix, Amazon, Apple, and YouTube set the terms and where legacy studios are the ones being squeezed. Merging two subscale players, on this view, creates a competitor rather than eliminating one. Ellison has promised 30 theatrical releases a year post-merger, a combined Paramount+ and HBO Max, and a merged CBS Sports and TNT Sports.
Paramount also went straight for the states’ soft spot: jobs. “Delaying this transaction will only harm entertainment workers who have already suffered over recent years as technology has disrupted their livelihood and cost California tens of thousands of entertainment jobs.” That is a pointed thing to say to the attorney general of California.
There is a harder-edged version of this fight too. Advisers to Ellison have reportedly floated moving Paramount’s operations out of California entirely if the state moves against the deal. Whether that is a genuine plan or a negotiating posture, it tells you how the company reads the politics.
The Nexstar-Tegna Precedent
This is the case Paramount’s lawyers do not want cited, and it is the first one everyone cites.
In March 2026, a similar coalition of state AGs, Bonta among them, sued to block Nexstar’s acquisition of Tegna. A judge granted a TRO eight days later. That merger is still frozen, with trial now set for July 2027.
Eight days. If the Paramount timeline runs the same way, the deal is on ice well before the ticking fee starts.
The obvious rebuttal: local broadcast station overlap is a far cleaner antitrust story than film distribution. Nexstar and Tegna owned rival stations in the same designated market areas. Paramount and Warner compete for the same audiences in a market that also contains Netflix, YouTube, and TikTok. Antitrust experts quoted by the Wall Street Journal called the states’ case coherent but nowhere near a slam dunk.
Why the DOJ Said Yes and the States Said No
The most interesting thing about this case is not the merits. It is the institutional split.
The DOJ ran an eight-month Second Request review, took depositions, held meetings, and concluded there was no threat to competition worth challenging. The states, looking at the same industry, concluded the opposite and rushed to court within a month.
Two readings, and you should hold both:
The cynical one. Federal antitrust under this administration cleared a deal backed by the Ellisons, and Democratic AGs are suing a company that is about to own CNN and CBS News. Conservative commentators including Katie Miller and Clay Travis said exactly that on Monday. The lawsuit’s markets may be about film, but Bonta himself brought up “fewer journalists informing the electorate” at the press conference, which is not a Clayton Act argument.
The structural one. State AGs have quietly become the real merger enforcers in the U.S. They have standing, they have parens patriae authority, they do not need the DOJ, and they have now proven twice in one year that they can freeze a mega-deal with a TRO. Federal clearance is no longer the finish line. It is a checkpoint.
For anyone modeling M&A risk, the second reading is the one that changes your spreadsheet. A deal thesis that treats DOJ sign-off as terminal is now a deal thesis with a hole in it.
What It Means for the Streaming Endgame
Strip out the legal drama and the strategic logic of this deal has not changed.
Legacy media has a scale problem, not a growth problem. In a business with high fixed content costs and thin differentiation, size is not vanity. It is the actual business model. Paramount and Warner each ran the numbers alone and concluded they were subscale. The merger is an admission of that, not a display of strength. We made the same argument when the DOJ cleared the deal in June.
Netflix, which lost the bidding war and walked away with $2.8 billion, is meanwhile rebuilding the bundle from the inside with live channels and advertising. It is solving the same engagement and monetization problem without an antitrust trial.
That contrast is the whole strategic lesson. Netflix is buying scale organically through product. Paramount is buying it through a transaction that requires a court’s permission. One of those approaches has an external dependency you cannot control.
If the deal stalls, the combined HBO Max and Paramount+ service does not launch, the CBS Sports and TNT Sports merger does not happen, and roughly $6 billion in projected synergies sits in a filing cabinet accruing interest. WBD, meanwhile, is stuck operating as a standalone company it has already told the market it is done being.
FAQ
Who is suing Paramount? Attorneys general from California, Arizona, Colorado, Connecticut, Massachusetts, Minnesota, Nevada, New Jersey, New Mexico, New York, Oregon, and Washington, led by California AG Rob Bonta.
Didn’t the DOJ already approve this deal? Yes. The Justice Department’s Antitrust Division closed its review on June 12, 2026 without challenging the merger. State attorneys general have independent authority to bring federal antitrust claims, so DOJ clearance does not preclude a state suit.
What is a ticking fee? A contractual payment to the target’s shareholders for each period the deal remains unclosed past an agreed date. Here it is $0.25 per WBD share per quarter starting September 30, 2026, roughly $650 million per quarter for Paramount.
Is the lawsuit about CNN? Not legally. The complaint’s three defined markets are theatrical film distribution, blockbuster film distribution, and basic cable licensing. News concentration was raised rhetorically at the press conference but is not part of the claims.
When will we know if the deal is blocked? The states asked the court to rule on their TRO motion by July 22, 2026, which is also the European Commission’s deadline for its own decision. A TRO would pause the deal, not kill it, and Paramount would almost certainly appeal.
The Business Model Analyst Take
Paramount built its winning bid on a promise of regulatory certainty. That was the entire pitch against Netflix: our path is cleaner, our close is faster, and we will pay you a ticking fee to prove we believe it. WBD’s board bought the argument and took $31 a share in cash.
The bid worked. The premise did not survive contact with reality.
What Paramount got wrong was not the law. It was the map of who enforces it. The company optimized hard for a single gatekeeper, won that gate, and discovered there were twelve more standing behind it, each with its own courthouse and none of them subject to the lobbying that worked in Washington. The ticking fee, engineered as a credibility signal, is now a $7 million per day tax on being wrong about that.
The broader lesson for anyone underwriting a horizontal merger in a politically salient industry: federal clearance is necessary and no longer sufficient. State AG coalitions have discovered they can independently freeze billion-dollar transactions with a TRO, and they have now done it twice in five months. Price that in, or someone will price it in for you.
The deal is probably still more likely than not to close eventually. The states’ market definitions are aggressive, the streaming-competition rebuttal is real, and appellate courts have been skeptical of theories this ambitious. But “eventually” is doing a great deal of work in that sentence, and at $650 million a quarter, eventually is the most expensive word in Paramount’s vocabulary.