Rob Bonta canceled Monday’s settlement meeting over leaks. The bond demand, the Tennessee threat and the leaks themselves are one instrument: an attempt to move the cost of delay onto somebody else’s balance sheet.
California Attorney General Rob Bonta scrapped a Monday settlement meeting with Paramount CEO David Ellison, accusing the company of leaking and misrepresenting a Friday planning session. A week earlier Paramount asked the court to make the 12 suing states and the Writers Guild post a $1.88 billion bond. The number everyone is watching is the $7.2 million per day ticking fee. The number that should worry Paramount more sits in its own motion: the US antitrust clearance underpinning this deal expires on February 19, 2027, eleven days before the trial that decides it.
Bonta pulled the meeting down late Sunday night. Lawyers for both sides had spent Friday setting an agenda for what would have been the first substantive settlement conversation since the states sued in July. By Monday afternoon the two camps were trading statements about who talked to reporters.
The collapse looks like a story about manners. It is a story about a deadline.
What Happened
Bonta’s office confirmed it had canceled the August 24 meeting with Ellison, citing Paramount’s failure to keep the Friday session confidential. Bonta accused the company of leaking the substance of the discussions and misstating them, which he called “a lack of good faith.” Paramount answered that it “has not been the source of the leaks” and said it remains ready to negotiate.
Going into the room, Bonta was expected to ask Paramount to divest some cable channels and commit to keeping the Paramount film studio operating separately from Warner Bros. He has said he wants structural changes, not promises about behavior, and he has called the deal illegal.
The meeting existed because Governor Gavin Newsom, Los Angeles Mayor Karen Bass, the DGA, IATSE and a run of Hollywood trade groups pushed Bonta to settle rather than freeze two studios for another eighteen months. That pressure campaign is now the most valuable asset Paramount has in California, and Bonta answered it by walking away from the table.
| Metric | Figure |
|---|---|
| Bond Paramount is demanding | $1,884,726,092.73, to be posted by September 30, 2026 |
| Ticking fee | $0.25 per WBD share per quarter from October 1, 2026 |
| Daily cost of that fee | About $7.22 million, or roughly $650 million a quarter |
| Ticking fees Paramount claims through post-trial briefing | $1.3 billion |
| The remainder of the bond demand | About $585 million, or 31% |
| US HSR clearance expires | February 19, 2027 |
| Trial opens | March 2, 2027, scheduled for 12 days |
| Jurisdictions that have cleared the deal | 68 |
| Regulatory termination fee if the deal dies | $7 billion |
| Deal terms | $31.00 per share cash, about $81 billion equity, $110 billion enterprise value |
The Backstory
Paramount won Warner Bros. Discovery in February by outbidding Netflix on terms rather than price alone. The ticking fee was part of that package. Ellison told WBD’s board that his regulatory path was cleaner than Netflix’s and offered to pay Warner shareholders $0.25 a share every quarter after September 30, 2026 to prove he believed it. The board took the deal.
The clearance arrived first. Paramount certified compliance with the Justice Department’s Second Request in February, and the Hart-Scott-Rodino waiting period expired at 11:59 pm on February 19, 2026. The Antitrust Division closed its review on June 12 without challenging the merger. Sixty-eight jurisdictions have now signed off, including the European Commission in July and the UK in August, each one billed to the synergy target rather than to cash.
Then twelve state attorneys general sued in the Northern District of California on July 13 under Section 7 of the Clayton Act. Judge Araceli Martínez-Olguín granted a temporary restraining order on July 20 and declined to require the states to post any bond, writing that they had brought the case “to enforce important public interests.” Paramount then agreed to hold off closing until the case resolves or June 2027 arrives, whichever comes first, rather than fight a preliminary injunction it might lose. That stipulation is the order Paramount is now trying to unwind.
The Plan
Paramount is running three plays at once, and none of them argues the merits.
The first is the bond motion, filed August 17 and signed by former federal prosecutor Danielle Sassoon. It asks the court to dissolve the standstill order unless the plaintiffs post $1,884,726,092.73 by September 30. If Paramount wins at trial, it collects.
The second is geography. Ellison told his leadership team that he will begin moving Paramount out of California on October 1 absent settlement talks, with Georgia, Texas and Tennessee on the shortlist and roughly 30,000 jobs in play over five years. Bonta has called that blackmail twice.
The third is publicity, and it is the one that just backfired. Somebody described Friday’s meeting to reporters. Bonta canceled Monday’s session over it.
The Business Model Angle
Start with the arithmetic Paramount put in its own filing.
The company told the court it will have burned $1.3 billion in unrecoverable ticking fees by the time post-trial briefing wraps. At $7.22 million a day from October 1, that lands on March 30, 2027, which fits a twelve-day trial opening March 2. So the fee accounts for $1.3 billion of the ask. The other $584.7 million, 31% of the total, covers financing fees, delayed synergies and the cost of refiling for approvals. Paramount is telling a federal judge that delay costs it 45% more than its own contract says it does.
That gap is the tell. The ticking fee is the part of this Paramount can quantify, and it is the smaller problem.
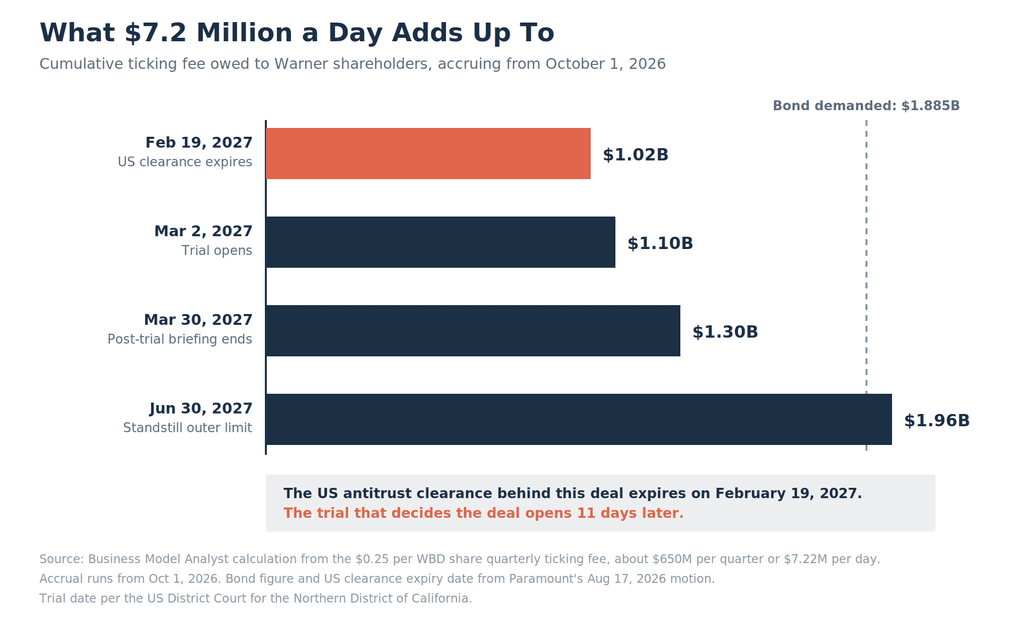
Buried in the same motion is the sentence that reframes the case. Paramount says a March 2027 trial will leave it “forced to restart the regulatory-approval process in certain jurisdictions,” and it names the United States, whose approval expires on February 19, 2027.
Run the date back. Under HSR rules, parties have one year from the expiration of the waiting period to close. Paramount’s waiting period expired February 19, 2026. One year later the statutory clearance lapses, and the trial that decides whether Paramount may use it opens eleven days after that.
Regulatory approvals are inventory. They arrive one at a time, they carry expiry dates, they cost real money to acquire, and they have to be valid at the same moment for a deal to close. Nobody depreciates them. They sit nowhere on a balance sheet. Paramount has assembled 68 of them across two years and is now watching the shelf life run out on the most important one while a single holdout keeps the closing date out of reach.
Financing works the same way. The $47 billion equity commitment from the Ellison family and RedBird, and the $54 billion of debt commitments behind it, carry their own expiry dates and their own repricing risk in a rate environment nobody underwrote for mid-2027. The $6 billion synergy program that holds up the 4.3x leverage promise does not start compounding until close.
For any operator, the transferable point is that permission is a perishable asset. Licenses, certifications, permits, distribution agreements, app store approvals, term sheets and lender commitments all expire on someone else’s calendar. Your binding constraint is the shortest-dated one, and you find out which one that is at the worst possible moment. Paramount spent two years optimizing for breadth of approval and is losing on duration.
The Risk
Four arguments cut against reading this as a Paramount defeat.
The bond motion will probably fail, and Paramount’s lawyers know it. Martínez-Olguín already waived a bond once on public interest grounds, courts rarely impose security on sovereign plaintiffs enforcing antitrust law, and the states have no fund to draw on. Which makes the motion a pressure instrument aimed at a settlement, not a recovery mechanism. Whether that pressure lands on Bonta, who is seeking re-election and has publicly enjoyed the fight, is a different question.
Paramount’s side of the fairness argument is stronger than Bonta’s soundbites suggest. The company agreed to the standstill under the shadow of a preliminary injunction it might have lost, so calling that agreement voluntary flatters the record. The losses accrue whoever turns out to be right, and the point of a bond requirement is exactly to protect a defendant later found to have been wrongly restrained.
The states have the better structural argument. A ticking fee is a private contract term Paramount wrote to beat Netflix in an auction. If a defendant can convert its own bid sweetener into a claim against public enforcers, then every future acquirer writes a larger fee into the agreement and every state AG faces a nine-figure invoice for asking a court to look at a merger. That template is worth more than this deal.
The HSR expiry may prove routine. The same Antitrust Division that declined to challenge the merger in June 2026 would receive the refiling, and a second filing restarts a waiting period rather than guaranteeing a second Second Request. The counterpoint is that a 2027 Justice Department is not the 2026 one, and by then a full trial record built by twelve attorneys general will be sitting in the public docket for whoever is running the division to read.
The relocation threat is the weakest of the three plays. Paramount can move an executive floor to Nashville. It cannot move the Melrose lot, the crews, the soundstages or the vendors, and Bonta’s authority comes from California consumers rather than Paramount’s mailing address. The threat reaches Newsom and Bass. It does not reach the attorney general.
Quick Questions
What is a ticking fee? A payment to the target’s shareholders for each period a deal stays unclosed past an agreed date. Here it runs $0.25 per WBD share per quarter starting October 1, 2026, about $650 million a quarter for Paramount.
Why does Paramount want a bond? Federal rules let a wrongly restrained defendant recover damages from security posted by the party that sought the restraint. Paramount argues the states and the WGA should carry the cost of a delay it says has no legal basis.
Will the states have to pay it? Unlikely. The judge already declined to require a bond when she issued the July restraining order, citing the public interest in the states’ claims.
What happens if the US clearance expires before trial? Paramount refiles under Hart-Scott-Rodino and waits out a new period. The risk is not automatic rejection, it is another delay handed to a company already paying $7.22 million a day.
Is Paramount actually leaving California? Ellison has set October 1 as the trigger and named Georgia, Texas and Tennessee. Moving corporate headquarters is straightforward. Moving production infrastructure takes years and has no effect on the lawsuit.
The Business Model Analyst Take
Paramount bought this deal with time. The ticking fee, the $7 billion regulatory break fee and the $2.8 billion it handed Netflix all priced the same promise: we will close faster than the other bidder. WBD’s board bought it, and the Justice Department validated it in June.
The promise has now inverted. Speed was the product, delay is the tax, and Paramount spent August trying to sell the delay to somebody else. A bond motion computed to the penny, a threat to relocate 30,000 jobs, an op-ed campaign and a leaked settlement meeting are the moves of a company that has run out of arguments about the merger and moved on to arguments about the calendar.
The deeper problem is one most companies share and few track. Paramount holds 68 regulatory approvals, an equity commitment, a debt package and a merger agreement, and every one of them expires. Permission is an asset with a maturity date, and no accounting standard makes you write it down as it ages. The company optimized for collecting approvals and never priced the risk that they would go stale before it could use them all at once.
Bonta understands this better than Paramount’s public relations operation does. He does not need to win in March. He needs the calendar to keep running, because at $7.22 million a day with the US clearance lapsing eleven days before opening statements, every week of silence costs Paramount more than any concession Bonta would have asked for on Monday.
That is why he canceled the meeting.