
Outback Steakhouse looks like a franchise chain. It has a mascot-grade signature dish, a national ad budget, a slogan people can still recite, and more than a thousand locations worldwide. Every instinct trained on McDonald’s says the same thing: this is a brand that collects royalties while somebody else runs the restaurants.
It is not. And that single structural fact explains almost everything that has happened to Outback in the last two years, including why its parent company suspended a dividend it had been paying for years in order to close its own restaurants.
This is a breakdown of how the Outback Steakhouse business model actually works, where the money comes from, where it leaks out, and why the numbers behave the way they do.
What is the Outback Steakhouse business model?
Outback Steakhouse is a casual-dining steakhouse concept owned by Bloomin’ Brands (Nasdaq: BLMN). It makes money almost entirely by operating restaurants itself and selling food and drink directly to guests, not by franchising. Of the 666 Outback locations in the United States as of December 28, 2025, Bloomin’ Brands owned and operated 548 of them, roughly 82%. Royalties from the remaining 118 U.S. franchised units and 355 international franchised restaurants are a rounding error next to company restaurant sales.
The core economic engine is volume: sell a $29 average check to a lot of people, and manage the spread between that check and the cost of beef, labor, and rent. It is a margin business disguised as a brand business.
The One Number That Explains Outback
Start with ownership, because everything else follows from it.
Bloomin’ Brands’ FY2025 Form 10-K, filed February 25, 2026, lays out the U.S. footprint with unusual clarity. Across all four of its brands, the company owned and operated 957 restaurants and franchised just 138. That is an 87% company-owned mix in a category where the franchise business model is supposed to be the default.
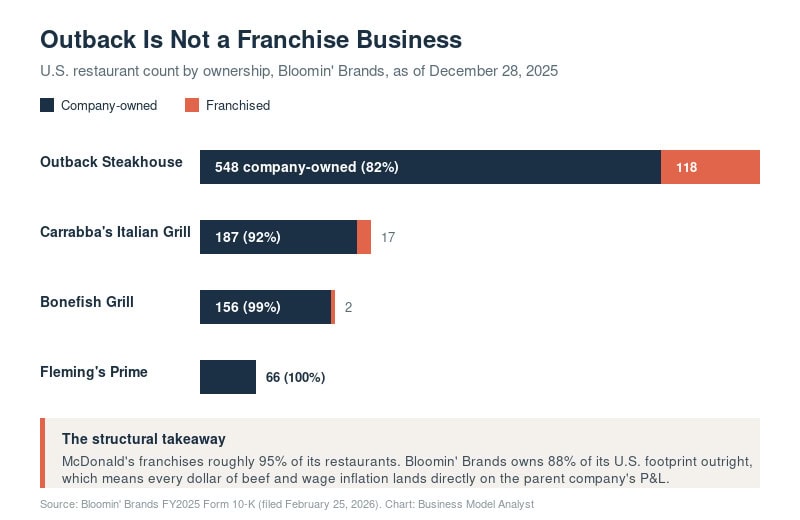
Compare this to the McDonald’s business model, where roughly 95% of restaurants are franchised. McDonald’s is, in a meaningful sense, a real estate and brand-licensing company that happens to sell hamburgers. When beef prices spike, the pain lands first on thousands of independent operators. McDonald’s still collects its percentage.
Outback has no such buffer. When beef goes up, Bloomin’ Brands pays for the beef. When wages go up, Bloomin’ Brands pays the wages. When a lease renews at a worse rate, Bloomin’ Brands signs it. There is no fee stream sitting between the parent company and the input cost.
This is the difference between an asset-light franchisor and an operator. And it is why a bad year at Outback does not produce a slightly softer quarter. It produces a dividend suspension.
Where the Revenue Actually Comes From
Bloomin’ Brands generated $3.956 billion in total revenues in fiscal 2025. The revenue architecture has four components, and they are wildly unequal in size.
| Revenue stream | How it works | Relative scale |
|---|---|---|
| Company restaurant sales | Food, non-alcoholic beverage, and alcohol sold at the 957 U.S. company-owned restaurants across all four brands | The overwhelming majority of the $3.96B |
| U.S. franchise royalties | Monthly royalty of 3.50% to 5.75% of gross restaurant sales from 138 U.S. franchised units, plus a $40,000 initial franchise fee | Minor |
| International franchise royalties | Monthly royalty of 2.75% to 5.00% from 355 franchised restaurants across 11 countries and Guam, plus initial fees of $35,000 to $75,000 | Minor |
| Brazil equity income | A 33% retained stake in the Brazilian operations, sold down from 100% on December 30, 2024, plus franchise royalties from 188 Brazilian restaurants | Immaterial, and currently a net loss |
That table is the whole story. Outback is a restaurant operator with a small franchising side business, not a franchisor with a small operating arm.
The international line deserves a note. On December 30, 2024, Bloomin’ Brands sold 67% of its Brazil operations and retained 33%. Overnight, 174 company-owned Brazilian Outbacks became unconsolidated franchisees. This was a deliberate move toward asset-light economics in the one market where the brand was actually growing, and it tells you management understands the problem. They just applied the fix 5,000 miles from where it was needed most.
The Value Proposition, and Why It Stopped Working
Outback’s original promise was legible: a slightly indulgent steak dinner, in a fun room, at a price a normal family could clear without wincing. “No Rules, Just Right.” The Bloomin’ Onion was the whole positioning in a single appetizer, a deep-fried permission slip to not take dinner too seriously.
That proposition depended on a spread. Steak had to feel like an upgrade over a burger, while costing meaningfully less than a real steakhouse.
Both sides of the spread have been compressed.
On the top end, guests trading up have LongHorn and Texas Roadhouse, both of which have been posting comparable sales growth that Outback has not come close to matching. On the bottom end, value-forward casual chains like Chili’s and Applebee’s have been aggressively defending the deal-seeking diner. Outback got squeezed in the middle, which is the least defensible position on any price ladder.
Then look at the check.
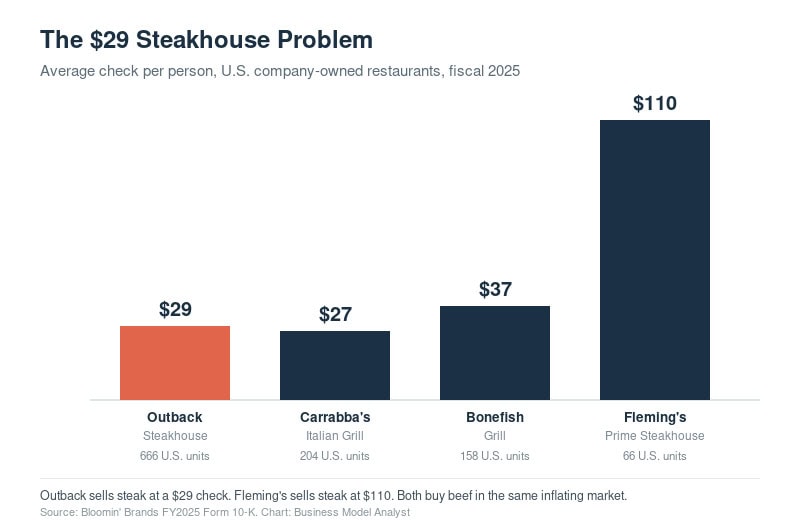
Outback runs a $29 average check per person. Fleming’s Prime Steakhouse, sitting inside the same corporate parent, runs $110. Both brands buy beef in the same market, from the same concentrated supplier base. Bloomin’ Brands disclosed that in 2025 it purchased more than 80% of its beef raw materials from just four suppliers.
When beef inflates, the $110 check absorbs it. The $29 check does not. This is the arithmetic behind beef becoming an affordable luxury: the brands positioned on quality can price through a commodity spike, and the brands positioned on value get crushed by it. Bloomin’ Brands guided to 4.5% to 5.5% commodity inflation for 2026. Outback is the brand least equipped to eat it.
The Sales Mix Problem Nobody Talks About
Here is where the model gets genuinely interesting, and where most analysis of Outback stops short.
Restaurant profitability is not driven by revenue. It is driven by mix. Two lines on a restaurant P&L matter far more than their share of sales suggests: alcohol, which carries the fattest margins in the building, and off-premises, which carries packaging costs, third-party delivery commissions, and none of the ambience you paid rent for.
Outback is on the wrong side of both.
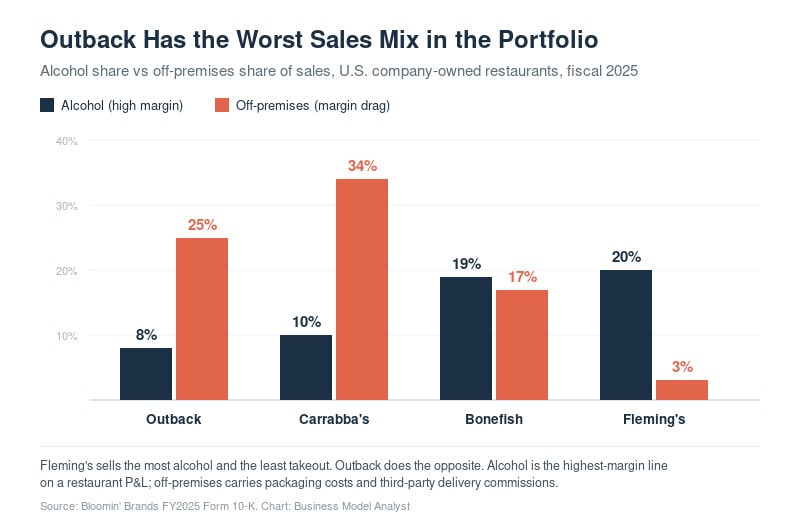
Alcohol is just 8% of Outback’s sales. At Bonefish it is 19%, at Fleming’s 20%. Meanwhile 25% of Outback’s sales are off-premises, versus 3% at Fleming’s.
Read those two facts together and the picture is stark. A quarter of Outback’s business is takeout steak, a product category that is objectively worse in a box, that generates zero bar revenue, and that often routes through a delivery platform taking a cut. Fleming’s, by contrast, sells almost nothing to-go and pours a fifth of its revenue in wine and cocktails.
Outback carries the portfolio on unit volume. It does so with the least profitable revenue mix of the four brands. That combination is not a marketing problem. It is a business model problem.
What the Financials Show
Fiscal 2025 is the cleanest illustration of the operator’s dilemma you will find in a public filing.
| Metric | FY2024 | FY2025 |
|---|---|---|
| Total revenues | $3.955B | $3.956B |
| Operating income | $139.8M | $37.2M |
| Net income | $(122.7)M | $13.2M |
| Adjusted diluted EPS | $1.45 | $1.14 |
| Outback U.S. comparable sales | Negative | (0.6)% |
Revenue was flat. Operating income fell 73%.
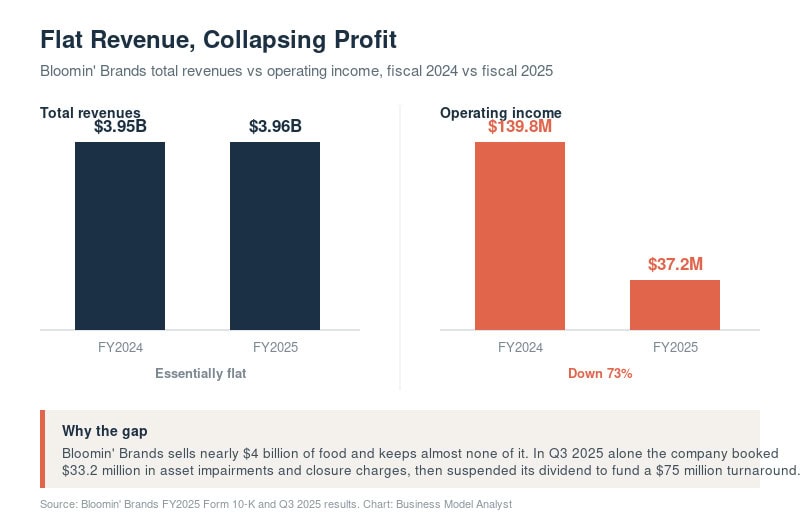
A franchisor with flat system sales has a boring year. An operator with flat system sales and rising input costs has a crisis, because every dollar of cost inflation comes straight out of operating income with nothing in between.
The turnaround response, announced November 6, 2025, was correspondingly blunt. Bloomin’ Brands recognized $33.2 million in asset impairments and net closure charges in Q3 2025, closed 21 U.S. restaurants, declined to renew leases on 22 more, and suspended its dividend entirely to redirect free cash flow into a $75 million Outback investment program spread across 2026 to 2028. The plan includes upgrading steak quality, remodeling nearly every Outback location by the end of 2028, and cutting server sections from six tables to four.
That last detail is the most revealing one in the entire turnaround. Reducing a server’s tables from six to four is a direct, permanent increase in labor cost per cover, made deliberately, in the hope that better service brings back traffic. It is an operator’s move. A franchisor could never make it, because a franchisor cannot force independent owners to volunteer margin.
There are early signs it is working. Outback posted its first quarter of positive traffic since Q4 2021 in the fourth quarter of 2025. In Q1 2026 the company reported revenue of $1.06 billion, GAAP diluted EPS of $0.64 against $0.50 a year earlier, and a restaurant-level operating margin of 14.0%.
The Hidden Risk in the Franchise Line
The franchise business is small, but it is not simple, and it contains a concentration risk that is easy to miss.
Of the 118 franchised Outback restaurants in the United States, 74 belong to a single operator: Out West Restaurant Group, the exclusive Outback franchisee across California, Arizona, Colorado, Nevada, and New Mexico. That is roughly 63% of the entire U.S. franchise base sitting with one counterparty.
That counterparty is distressed. Bloomin’ Brands has been operating under a forbearance arrangement with Out West and its lenders since December 31, 2023, covering prior payment defaults, reduced advertising fees, and payment priorities. The agreement expires on December 27, 2026. The company’s own 10-K states plainly that upon expiration or earlier termination, the deferred amounts become due, the lenders gain priority rights to pursue remedies including foreclosure, and there is no assurance the franchisee can satisfy them.
Bloomin’ Brands then disclosed in its Q1 2026 10-Q that, subsequent to the quarter’s close, it received notice from the agent for Out West’s senior lender that Out West was in default of its separate credit agreement.
A small franchise line item is not automatically a small risk. When 63% of it sits with one leveraged operator whose forbearance clock runs out in December 2026, it is a live structural exposure that a genuinely asset-light franchisor with thousands of operators would never carry.
The Outback Business Model Canvas
For a quick structural view, here is Outback mapped to the Business Model Canvas.
| Building block | Outback Steakhouse |
|---|---|
| Customer segments | Middle-income U.S. families and casual diners seeking an affordable steak occasion; suburban, value-conscious, celebration-adjacent |
| Value proposition | A grilled steak dinner with bold flavors and a relaxed Australian-themed atmosphere at a $29 average check |
| Channels | 666 U.S. restaurants (75% in-restaurant, 25% off-premises), online ordering, third-party delivery apps, brand app and website |
| Customer relationships | Dine Rewards loyalty program, national television and digital advertising, Restaurant Managing Partner ownership culture |
| Revenue streams | Company restaurant sales (food, non-alcoholic beverage, and 8% alcohol); U.S. franchise royalties of 3.50% to 5.75%; international royalties of 2.75% to 5.00%; initial franchise fees |
| Key resources | The Outback and Bloomin’ Onion trademarks; 548 company-owned restaurants; approximately 64,000 team members; supply chain and four-supplier beef relationships; the smaller-footprint “Joey” prototype |
| Key activities | Restaurant operations, supply chain and commodity purchasing, menu development, marketing, remodeling and site selection, franchisee management |
| Key partners | Four primary beef suppliers; custom distribution companies; third-party delivery platforms; franchisees including Out West Restaurant Group; the Brazilian joint venture partner |
| Cost structure | Cost of sales (beef-heavy, guided to 4.5% to 5.5% commodity inflation for 2026); labor (81% hourly turnover); occupancy and leases; national advertising; G&A |
Information Gain: The Numbers Most Coverage Misses
| Data point | Figure | Why it matters |
|---|---|---|
| Outback U.S. units, company-owned | 548 of 666 (82%) | The model is operating, not franchising |
| Outback average check | $29 | Steakhouse inputs on a casual-dining check |
| Outback alcohol share of sales | 8% | Lowest in the portfolio; forfeits the best margin line |
| Outback off-premises share | 25% | Highest margin drag of the three casual brands |
| Fleming’s alcohol / off-premises | 20% / 3% | The inverse mix, inside the same company |
| Beef supplier concentration | Over 80% from four suppliers | Minimal negotiating leverage on the key input |
| Alcohol as % of U.S. restaurant sales | 11% | Consolidated, across all four brands |
| Franchise concentration | 74 of 118 U.S. franchised Outbacks with one operator | Counterparty risk hiding in a small line item |
| Forbearance expiry | December 27, 2026 | A dated, disclosed cliff |
| U.S. hourly turnover, 2025 | 81% | Service consistency is structurally hard to fix |
| 2026 Outback openings planned | Approximately 6 | The growth story is remodeling, not expansion |
| Restaurants to be remodeled by 2028 | Nearly all Outbacks | Capital intensity of the operator model |
The “Joey” prototype is worth flagging as the quiet strategic bet. It is a roughly 5,000 square foot freestanding building seating about 190 guests, deliberately smaller than the legacy Outback box. Smaller footprint means lower rent, lower build cost, and higher return on invested capital per unit. It is the closest thing Outback has to a structural answer for its cost problem, and it addresses occupancy rather than beef.
How Outback Compares
| Outback (Bloomin’ Brands) | McDonald’s | Chipotle | |
|---|---|---|---|
| Ownership model | ~82% company-operated (U.S. Outback) | ~95% franchised | ~100% company-operated |
| Primary revenue | Restaurant sales | Franchise royalties and rent | Restaurant sales |
| Exposure to commodity inflation | Direct and full | Buffered by fee model | Direct and full |
| Pricing power | Constrained by value positioning | Constrained, but pain is distributed | Strong; premium positioning accepted |
| Capital intensity | High (remodels, leases, equipment) | Low (asset-light) | High |
Chipotle is the useful comparison, not McDonald’s. The Chipotle business model is also almost entirely company-operated and also fully exposed to input costs. The difference is that Chipotle built a premium value proposition that permits price increases, while Outback built a value proposition that punishes them. Same structure, opposite pricing power. That is what makes company-operated models work or fail.
The same lesson shows up in the Starbucks business model: a company-operated footprint is only survivable if the experience justifies the price. When the experience degrades, the premium stops feeling earned, and an operator has nowhere to hide.
Frequently Asked Questions
Is Outback Steakhouse a franchise? Mostly not. As of December 28, 2025, 548 of the 666 U.S. Outback Steakhouse restaurants were owned and operated by Bloomin’ Brands. Only 118 were franchised. Internationally the picture inverts, with 355 franchised restaurants across 11 countries and Guam, including 188 in Brazil and 101 in South Korea.
Who owns Outback Steakhouse? Bloomin’ Brands, Inc. (Nasdaq: BLMN), headquartered in Tampa, Florida. Bloomin’ Brands also owns Carrabba’s Italian Grill, Bonefish Grill, and Fleming’s Prime Steakhouse & Wine Bar. Its primary operating entity is OSI Restaurant Partners, LLC.
How much does an Outback franchise cost? The initial franchise fee for a U.S. full-service Bloomin’ Brands restaurant is generally $40,000, with monthly royalties of 3.50% to 5.75% of gross sales, plus contributions to national marketing and required local advertising spend. International initial fees range from $35,000 to $75,000 with royalties of 2.75% to 5.00%. Note that Bloomin’ Brands is not actively building out its U.S. franchise base; the company plans to open approximately six Outback restaurants in 2026.
How does Outback Steakhouse make money? Almost entirely through direct restaurant sales at company-owned locations. Guests spend an average of $29 per person, with 92% of that going to food and non-alcoholic beverage and 8% to alcohol. Bloomin’ Brands then manages the spread between that check and the cost of beef, labor, and occupancy. Franchise royalties are a small secondary stream.
Why did Bloomin’ Brands suspend its dividend? On November 6, 2025, alongside Q3 2025 results, Bloomin’ Brands suspended its dividend entirely in order to redirect free cash flow toward debt paydown and a $75 million Outback turnaround investment running through 2028. The company recognized $33.2 million in asset impairments and net closure charges in that quarter, closed 21 restaurants, and declined to renew leases on 22 more. Note that this was a full suspension, not a reduction.
Why is Outback closing restaurants? Underperformance concentrated in weak locations, amplified by beef and labor inflation landing directly on a company-operated P&L. Operating income fell from $139.8 million in fiscal 2024 to $37.2 million in fiscal 2025 on essentially flat revenue. Closing the weakest units and remodeling the rest is the cheapest available lever for an operator that cannot pass costs through to franchisees.
Is the Outback turnaround working? There is early evidence. Outback recorded its first quarter of positive traffic since Q4 2021 in the fourth quarter of 2025, and Bloomin’ Brands reported Q1 2026 GAAP diluted EPS of $0.64 versus $0.50 in the prior year, with restaurant-level operating margin at 14.0%. Whether that holds through a 4.5% to 5.5% commodity inflation year, and through the December 2026 expiry of the Out West forbearance agreement, is the open question.
The Business Model Analyst Take
The temptation is to read Outback as a brand problem. The room feels dated, the steaks got inconsistent, the ads stopped landing, so fix the room and the steaks and the ads and traffic comes back. That is the story management is telling, and to their credit, it is the story the early numbers support.
But the brand problem is downstream of the structural one, and the structural one is this: Outback built a company-operated cost base and a franchise-brand value proposition. It committed to owning every restaurant, every lease, and every hour of labor, while promising guests a steak dinner cheap enough that it can never raise prices enough to pay for any of it.
That works beautifully when beef is cheap. It becomes an existential squeeze the moment beef is not.
The instructive detail is the $29 check sitting in the same 10-K as the $110 check. Fleming’s is the control group. Same parent, same supply chain, same four beef suppliers, same wage market. Fleming’s is fine, because a $110 check can absorb commodity inflation and a 20% alcohol mix subsidizes everything else. Outback cannot and does not.
So the real question for anyone studying this model is not whether the remodels will land. It is whether a company-operated steakhouse can survive at a value price point at all, or whether the only stable versions of that business are premium (Fleming’s, and Texas Roadhouse’s pricing discipline) or asset-light (McDonald’s). Outback is currently attempting a third path: stay cheap, own everything, and out-execute the math. Cutting server sections from six tables to four is the purest expression of that bet, spending margin today to buy back traffic tomorrow.
It might work. Positive traffic and a 14.0% restaurant-level margin say the operating fix has real traction. But traction is not the same as a structural answer, and the structural answer is not in the remodel budget. It is in the Joey prototype, in the Brazil sale, and in whatever Bloomin’ Brands decides to do about 74 restaurants in the American West whose forbearance clock runs out in December.
Watch those three, not the steaks.