
A New York Times report warns the whole economy now leans on the AI boom. It never names the company doing the heaviest leaning. The gap between what OpenAI has promised to spend and what it actually earns is the fulcrum the entire story balances on.
The New York Times argued this week that the U.S. stock market and the broader economy have fused into one big bet on artificial intelligence. The piece stops at the abstract version of the risk: if one large AI company stumbles, the ripples spread. That company has a name. OpenAI carries more than $1 trillion in multi-year compute commitments while running at roughly a $25 billion revenue rate, and it loses about $1.22 for every dollar it takes in. That mismatch, not investor mood, is the real load-bearing wall.
There is a comfortable way to read the AI-and-the-economy story and an uncomfortable one. The comfortable read is that markets get frothy, sentiment cools, prices correct, and life goes on. The uncomfortable read is that a single private company sits underneath the demand curve for chips, power, and data centers, and that company has signed contracts it cannot yet pay for out of operations. Pull on that thread and the macro story stops being about psychology and starts being about one balance sheet.
What Happened
On July 22, the Times published a report making the case that the stock market and the economy are now effectively the same trade, both riding on AI. The argument is sound as far as it goes: the market has doubled over the past decade to more than $75 trillion, a small group of AI-linked names drives most of the gains, and the capital expenditure funding data centers and power lines is propping up real activity.
What the piece leaves implicit is which entity is generating the demand that justifies all of that spending. Strip away the index-level framing and you arrive at OpenAI, the company whose infrastructure appetite anchors the order books of nearly every vendor in the chain. The macro risk the Times describes is really a question about whether one company’s promises hold.
The Backstory
OpenAI is growing revenue faster than almost any company in software history. It went from about $3.7 billion in 2024 to a run rate near $25 billion by mid-2026, roughly $2 billion a month. Impressive on its own terms. The problem is the shape of that revenue and the cost of producing it.
Around 70% of the money comes from ChatGPT subscriptions, most of it $20-a-month consumer plans. API usage adds roughly a quarter, and Sora plus licensing makes up the rest. Against that, the cost of answering every query keeps the economics underwater. In the first quarter of 2026 the company posted an operating margin near negative 122%, and full-year losses are projected around $14 billion on the internal, compensation-excluded measure, with several outside estimates running higher once stock compensation is added back. The blunt version, which our OpenAI business model teardown walks through, is that this looks like a capital-intensive infrastructure business wearing a software company’s valuation.
The Plan
The strategy is to spend through the losses on the belief that scale and cheaper compute eventually flip the math. To get there, OpenAI has committed to an infrastructure build measured in the trillions. Reported obligations stack up across roughly seven vendors between 2025 and 2035 and total in the neighborhood of $1.15 trillion: Broadcom near $350 billion, Oracle around $300 billion, Microsoft near $250 billion, Nvidia up to $100 billion, AMD about $90 billion, Amazon Web Services near $38 billion, and CoreWeave around $22 billion.
Funding that gap is the entire purpose of the coming IPO. OpenAI was last valued near $852 billion and is preparing to go public at a valuation reported as high as $1 trillion, and it has been stacking its board with financial heavyweights to make the books look credible before anyone opens them, a move we covered in OpenAI’s recent bank-CEO board hires. The bet baked into that price is simple and enormous: that compute gets dramatically cheaper before the commitments come due.
The Business Model Angle
Here is the part the macro coverage skips. OpenAI is trying to underwrite a hyperscaler-sized capital program with a business that is mostly consumer subscriptions. Microsoft, Amazon, and Google fund their data-center build-outs from mature, high-margin cash machines. OpenAI is funding its build-out from $20 monthly plans, a thin API line, and outside capital, while losing money on each unit of usage.
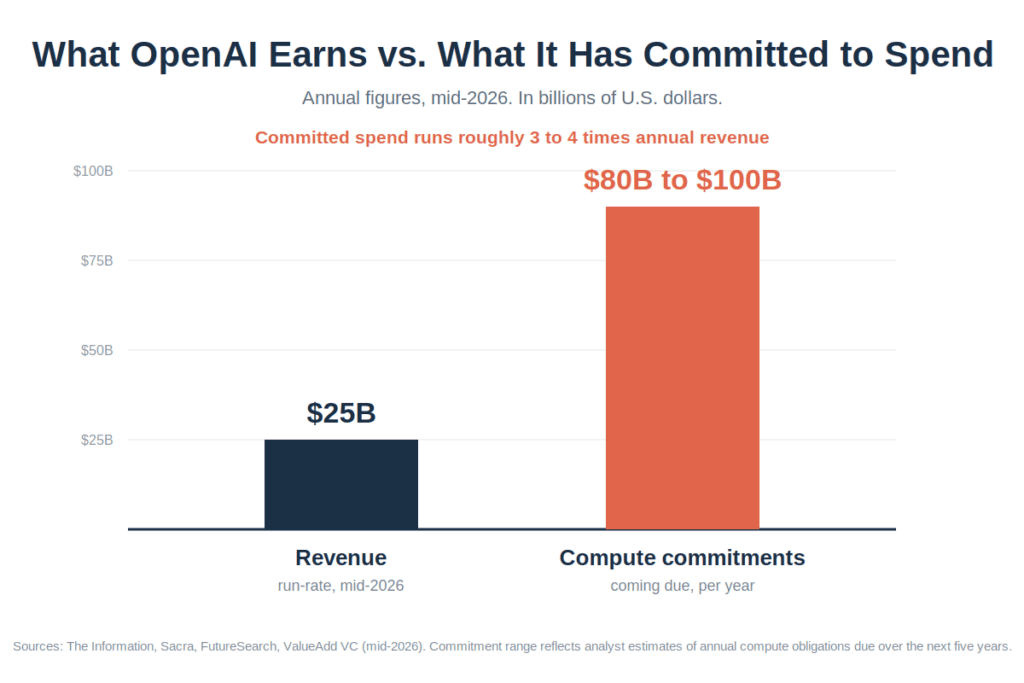
That is why the commitment-to-revenue gap matters more than any single quarter’s loss. Over the next five years, analysts estimate OpenAI faces something like $80 billion to $100 billion in annual compute commitments coming due, against a current revenue run rate near $25 billion. A normal business does not sign spending contracts at three to four times its annual revenue unless it is certain the revenue is about to explode or the capital will keep flowing. OpenAI is betting on both at once. Strip either assumption away and the model does not close.
The Risk
The Times frames the danger as a wealth-effect chain reaction: AI confidence falters, stocks fall, wealthy consumers pull back, layoffs follow. That is the demand-side story. The supply-side story runs through OpenAI’s contracts, and it is faster.
If OpenAI’s revenue growth slows, or the IPO prices weak, or the capital markets tighten, the company has to choose between honoring its commitments and preserving cash. Either choice sends a signal down the chain. Trimmed orders hit Nvidia, Oracle, Broadcom, and the power and construction firms building for them. Some of those same vendors are also investors in OpenAI, which means a slowdown does not travel in a straight line. It loops. The concentration the Times worries about at the index level is even tighter than it looks, because so many of the deals point back to one customer.
Quick Questions
How much revenue does OpenAI actually make? Roughly a $25 billion annualized run rate by mid-2026, about $2 billion a month, up from $13.1 billion in booked revenue for full-year 2025. Around 70% comes from ChatGPT subscriptions.
Is OpenAI profitable? No. It is projected to lose around $14 billion in 2026 on the internal measure, with some estimates higher, and it reportedly loses about $1.22 for every dollar of revenue.
How much has OpenAI committed to spend? Reported multi-year infrastructure commitments total roughly $1.15 trillion across about seven vendors through 2035, with something like $80 billion to $100 billion a year coming due over the next five years.
Why does this matter for the economy? Because much of the AI capital expenditure holding up growth traces back to OpenAI’s demand. If its commitments wobble, the effect spreads to chipmakers, cloud providers, and the power and construction sectors serving them.
The Business Model Analyst Take
The market-is-the-economy warning is correct, but it is aimed one level too high. The vulnerability is not diffuse investor sentiment. It is a specific, contractual gap between one company’s promises and one company’s income statement. OpenAI has committed to spend like the most profitable firms on earth while earning like a fast-growing but deeply unprofitable startup, and it is asking public markets to bridge the difference.
That can work. Revenue is compounding fast, compute costs may fall, and a successful IPO refills the tank. But it only works if nothing in that sequence slips. The uncomfortable truth buried in the macro coverage is that the economy’s soft landing now depends on a consumer-subscription business paying for an industrial-scale build-out. When the load-bearing wall of an entire boom is a single set of contracts signed at three to four times revenue, the honest question is not whether it holds. It is how much weight it can take before it does not.
Reporting and data drawn from The New York Times, The Information, Sacra, FutureSearch, Forbes, and OpenAI’s own disclosures, Q1 2026 through mid-2026. Revenue figures are run-rate unless noted.