
Sam Altman has reportedly offered the United States government a 5% stake in OpenAI. At the company’s $852 billion valuation, that is roughly $42.6 billion of equity, handed over for nothing.
The obvious read is that this is a political payoff. Washington is nervous about AI, so OpenAI buys goodwill with stock. That read is not wrong. It is just shallow.
Here is the sharper one. Equity is the cheapest currency OpenAI has and the only currency Washington actually wants. Paying it now does not plug a hole in the balance sheet. It builds something far more valuable: a government that owns the upside of a company carrying $665 billion in compute obligations against $25 billion of revenue.
Once the state owns the upside, it inherits the downside. That is not philanthropy. That is underwriting.
Definition Box Bailout insurance is a pre-emptive arrangement in which a company transfers ownership or influence to the state before a crisis, so that the state has a direct financial interest in preventing that company’s failure. Unlike a bailout, which is requested under distress, bailout insurance is offered from a position of strength, on terms the company sets.
What Was Actually Proposed
According to the Financial Times, OpenAI held early, conceptual talks with the Trump administration about handing the US government a 5% equity stake, with Altman engaging directly with President Trump, Commerce Secretary Howard Lutnick, and Treasury Secretary Scott Bessent.
Two details matter more than the headline.
First, the proposal is not OpenAI-only. Altman reportedly suggested the government hold 5% of each leading US AI developer, including Anthropic, Google, and Meta, likely through a sovereign wealth fund vehicle. Second, any real version of this would probably require an act of Congress.
That second point is the tell. A stake structured through legislation is not a handshake. It is a permanent institutional relationship.
| Element | Detail |
|---|---|
| Stake proposed | 5% of OpenAI equity |
| Implied value | About $42.6 billion at an $852 billion valuation |
| Scope | Extended to other major US AI firms, including Anthropic, Google, Meta |
| Vehicle | Sovereign wealth fund or public wealth fund style entity |
| Status | Preliminary and conceptual, may require Congress |
| Precedent | The US took a roughly 10% stake in Intel in 2025 |
The Bailout Case Does Not Rest on the 5%
Let us kill the lazy version of this argument first, because plenty of commentators are about to run with it.
“OpenAI is broke, so it is begging Washington” does not survive contact with the numbers. A company two quarters from the wall does not give away $42.6 billion of stock. It also does not close the largest private round in history in March, file a confidential S-1 in June, and target a listing above $1 trillion. OpenAI has a structural cash problem, not an imminent liquidity problem. Those are different diseases.
The bailout evidence lives somewhere else entirely, and it is much stronger than the equity offer.
| Signal | The number |
|---|---|
| Long-term compute procurement commitments | About $665 billion through 2030 |
| Annualized revenue, mid-2026 | About $25 billion |
| Q1 2026 revenue vs cash burn | $5.7 billion vs $3.7 billion |
| Q1 2026 operating loss | About $9.3 billion, excluding non-cash charges |
| Projected cash burn | About $27 billion in 2026, about $63 billion in 2027 |
| First cash-flow positive year | 2030, on current projections |
| Systemic exposure | Roughly 45% of Microsoft’s $625 billion cloud backlog is tied to OpenAI |
| Credit contagion | Barclays warned Oracle’s rating could drift toward junk under Stargate spending |
Read the top two rows together. OpenAI has committed to buying roughly 27 years of its current annual revenue in compute. That gap is not closed by ads, by Sora, or by a hardware device. It is closed by capital markets staying open, continuously, for the rest of the decade.
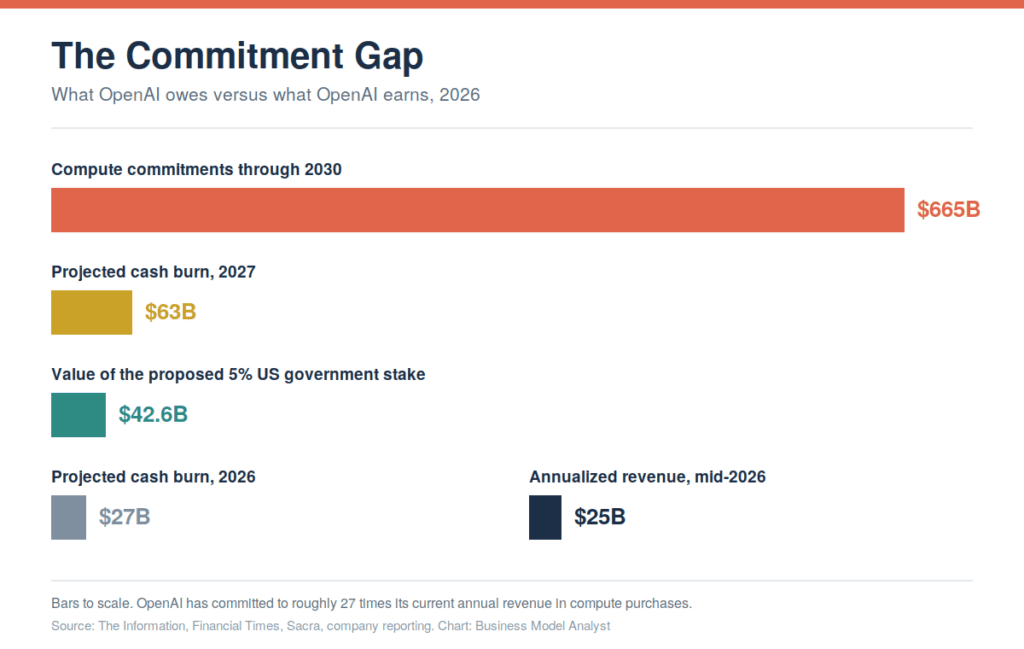
Which means the real risk is not that OpenAI runs out of money. It is that OpenAI runs out of lenders at exactly the moment its obligations come due. Those are the conditions under which every bailout in modern history has actually happened.
The Backstop Nobody Forgot
In November 2025, CFO Sarah Friar floated the idea of a federal “backstop” for AI infrastructure financing. The walkback took less than a day. Altman said publicly that OpenAI did not want government guarantees.
Treat that as a failed trial balloon, not a retracted belief. The company tested whether Washington would insure its compute buildout, discovered the answer was politically radioactive, and stopped asking.
Eight months later, it is offering equity instead.
This is the strategic inversion worth writing down: you cannot ask for a backstop, but you can create the conditions under which one becomes inevitable. A government that holds $42.6 billion of OpenAI stock inside a sovereign wealth fund, with the proceeds notionally earmarked for the public, does not calmly watch that company hit a financing wall in 2028. It intervenes. Not out of favoritism, but because the alternative is writing down a public asset and detonating Oracle, CoreWeave, and a chunk of Microsoft’s backlog in the process.
Fannie Mae and Freddie Mac carried an implicit government guarantee for three decades before anyone had to cash it. Nobody ever signed a document promising a rescue. The entanglement was the promise.
The Counterarguments a Smart Skeptic Will Raise
Three of them are serious, and any honest version of this analysis has to answer them.
“It’s a regulatory bribe, not a financial one.” Strong argument. Washington has grown wary of frontier model cyber capabilities and Chinese open-source competition. OpenAI’s GPT-5.6 launch was gated pending a government preview, and Anthropic had access to its most advanced models suspended entirely under export controls before the restrictions were lifted. Equity buys release velocity. This explanation is real, and it may be the primary motive. It is also not mutually exclusive with the bailout thesis. The same entanglement that speeds up releases also makes rescue rational.
“The market read it as bullish, not desperate.” Also true. Wedbush analysts viewed an outcome consistent with the reported plan as positive for the sector, citing stronger government support for AI supply chains and fewer model release delays. Markets are not stupid here. They are simply pricing the same entanglement from the other direction. “The government will support this company” is exactly what a bailout thesis predicts, and exactly what an equity holder wants to hear. Bulls and bears agree on the mechanism and disagree only on whether it is a feature.
“It’s anchoring, not desperation.” The sharpest objection. Bernie Sanders has pushed for the government to take a 50% stake in major AI companies through a sovereign wealth fund. Altman offering 5% first is classic negotiation: set the anchor low, in your own frame, before somebody else sets it at ten times the price. If that is the whole story, the offer says nothing about OpenAI’s finances at all. The honest response is that anchoring explains the number. It does not explain why OpenAI wants a state shareholder in the first place, when Google and Meta clearly do not.
Why the Other Names on the List Give It Away
The detail most coverage skipped: OpenAI proposed the government take 5% of everyone, including Anthropic, Google, and Meta. Google and Meta generate enormous free cash flow. They do not need a state shareholder and have no obvious reason to want one.
That is not an argument against the bailout thesis. It is the strategy.
A stake taken only in OpenAI is a rescue, and it looks like one. A stake taken across the entire frontier is industrial policy, and it looks like patriotism. Bundling yourself with three companies that do not need the deal is how you make the deal you need look like a public good. If a US AI sovereign wealth fund exists and OpenAI is inside it, the government has no way to let OpenAI fail without admitting that its own portfolio was mispriced.
Altman is not asking to be saved. He is arranging to be unsaveable-from.
The Business Model Analyst Take
The 5% proposal is not evidence that OpenAI is running out of money. It is evidence that OpenAI’s leadership has correctly modeled the scenario in which it does, and is acting eight quarters early.
Every genuine bailout in the last fifty years shared one precondition: the failing entity was already politically entangled before the crisis arrived. Chrysler had the unions. The banks had the deposit system. Fannie had the housing market and an implicit guarantee written nowhere. The rescue was never negotiated in the crisis. It was negotiated years earlier, quietly, when nobody was watching.
OpenAI has $665 billion in commitments, $25 billion in revenue, no cash-flow positive year until 2030, and an IPO that will hand it public shareholders and quarterly scrutiny. Somewhere in that gap is a financing window that closes. When it does, the question will not be whether Washington helps. It will be whether Washington has a choice.
Altman is making sure it does not. That is the trade. Forty-two billion dollars in stock is a cheap premium on a policy that pays out in the tens of billions, and the beauty of it is that everyone gets to call it generosity on the way in.
Watch for one signal above all: whether this structure gets drafted into legislation. Conceptual talks are cheap. A statutory sovereign wealth fund holding AI equity is a permanent claim, and permanent claims come with permanent obligations in both directions.
Frequently Asked Questions
Is OpenAI actually running out of money? Not imminently. OpenAI holds substantial reserves, closed a record round in March 2026 at an $852 billion valuation, and has filed confidentially for an IPO. The problem is structural, not immediate: projected cash burn of about $27 billion in 2026 and about $63 billion in 2027, with no cash-flow positive year expected until 2030.
How much is the 5% stake worth? Roughly $42.6 billion, based on OpenAI’s $852 billion post-money valuation from its March 2026 funding round.
Would other AI companies have to do the same? Under the reported proposal, yes. Altman suggested the government take similar 5% stakes in other leading US AI developers including Anthropic, Google, and Meta. It is not clear that any of them support the idea.
Has the US government taken stakes in private companies before? Yes. The Trump administration acquired a roughly 10% stake in Intel in 2025 and has taken positions in other chipmaking and critical mineral companies.
What is the difference between a bailout and bailout insurance? A bailout is emergency capital delivered under distress, on the rescuer’s terms. Bailout insurance is entanglement created in advance, on the company’s terms, so that a future rescue becomes the rational choice for the state rather than a political fight.
Related reading on Business Model Analyst:
- OpenAI Leaked Financials: $38B Loss on $13B Revenue
- OpenAI Files Confidentially for IPO
- OpenAI Business Model: How OpenAI Makes Money
- Top OpenAI Competitors and Alternatives
- OpenAI Ships GPT-5.6 and Points It at Anthropic