
Fenix International distributed more cash in 2025 than it earned. For an asset almost nobody is allowed to buy, the dividend was the exit.
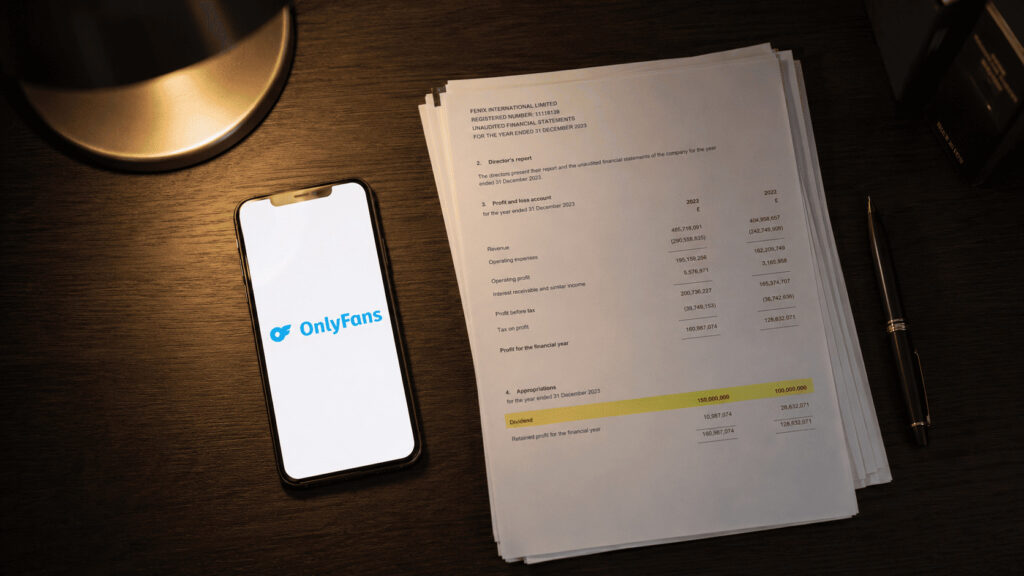
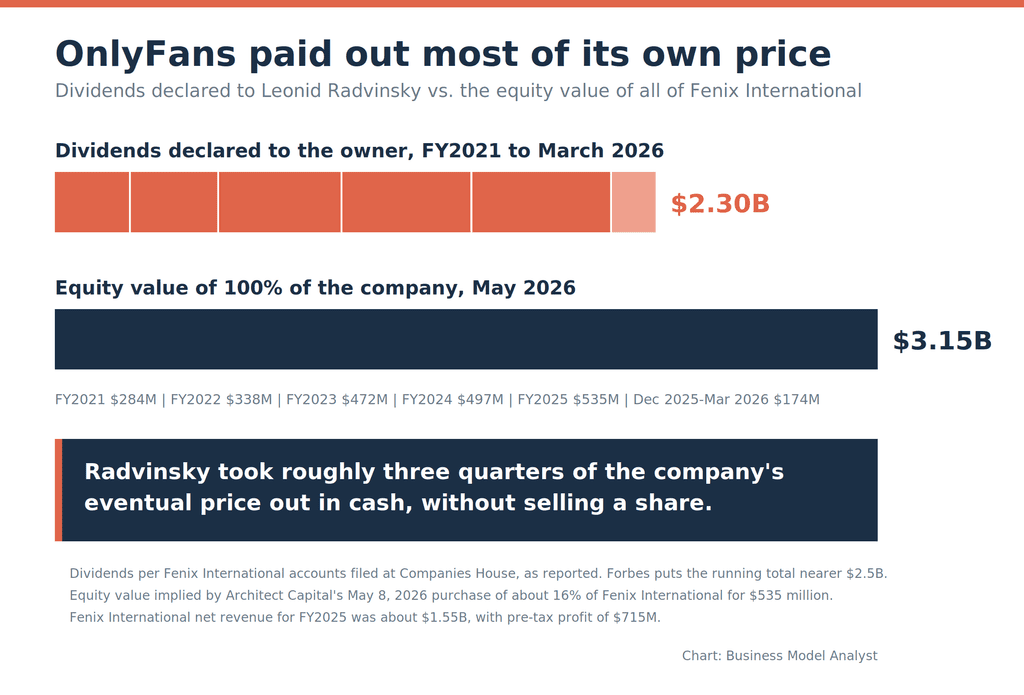
OnlyFans parent Fenix International paid founder Leonid Radvinsky $535 million in dividends for the year ended November 30, 2025, plus another $174 million between December and March, weeks before he died of cancer at 43. The FY2025 dividend came to about 103% of post-tax profit. Add the earlier years and Radvinsky pulled roughly $2.3 billion out of a company that a buyer priced at $3.15 billion in May. He never sold a share of it. The distribution policy was the only liquidity the asset could produce, and the failed sale process proved it.
Most coverage of the filing is running the same line: tiny company, enormous cash, awkward content. Forty-seven employees, $1.55 billion of net revenue, a founder who never gave an interview and died young. All true, and all beside the point.
The number worth staring at sits in the payout column. In FY2025 Fenix earned about $521 million after tax and declared $535 million of dividends. It distributed more than it made. Then it distributed $174 million more in the four months that followed. A company growing revenue at 10% a year, with a pre-tax margin near 46%, chose to retain nothing.
Growth companies do not do that. Cash cows in mature categories do not do that either. The S&P 500, in the twelve months to September 2025, returned about 80 cents of every dollar of net income to shareholders through dividends and buybacks, and that was a record. Lodge Cast Iron, a 130-year-old family manufacturer we wrote about last week, keeps 70 cents of every pre-tax dollar inside the business. Fenix kept nothing.
What Happened
Fenix International filed accounts at Companies House this week covering the year to November 30, 2025. Net revenue rose about 10% to roughly $1.55 billion. Pre-tax profit rose 5% to $715 million. Operating profit rose 6.5% to $709 million. Post-tax profit came in above $521 million.
Underneath the platform revenue sits the gross number. Creators collected about $6.2 billion during the year after OnlyFans took its 20% cut, which puts total payments through the site near $7.75 billion. Since 2016 the platform has moved roughly $30 billion to creators. The company counted 5 million creator accounts, of which 2.5 million transacted during the year, against 132 million active fan accounts. The United States is the largest market, followed by the United Kingdom and continental Europe.
Fenix employed 47 people. It also contracted about 1,500 outside content moderators, a spokeswoman told the WSJ.
Radvinsky received $535 million in dividends for the financial year, then four further tranches totaling $174 million between January and the end of March. He died in March. Control passed to a family trust headed by his widow, Yekaterina “Katie” Chudnovsky. The filing notes the director does not recommend a further dividend for the current period, which would be the first pause in five years.
The Backstory
Tim Stokely and his father Guy launched OnlyFans in 2016. Radvinsky, who had built the cam site MyFreeCams, bought control in 2018 and became sole owner of the London-based parent. He never gave a public interview. One photograph of him circulates online.
The dividend record starts in 2021 and climbs without interruption: $284 million, then $338 million, $472 million, $497 million, and $535 million for FY2025. Add the $174 million paid in early 2026 and the disclosed annual figures total about $2.3 billion. Forbes puts the running tally nearer $2.5 billion once the between-year tranches are counted.
Set that against the sale process, which ran on a parallel track and failed repeatedly.
In May 2025, Bloomberg and Reuters reported Radvinsky exploring a sale at around $8 billion, with an investor group led by Los Angeles firm Forest Road Company. Days earlier the New York Post had reported he was struggling to find buyers at an implied $1.46 billion to $2.42 billion. The spread between those two reports is the entire problem in one line: nobody agreed what the asset was worth, because almost nobody was allowed to bid.
By January 2026 the WSJ reported exclusive talks with Architect Capital, a San Francisco firm founded in 2021 to lend against assets that mainstream capital avoids. The structure: about 60% of the business at $3.5 billion of equity value, or $5.5 billion including $2 billion of debt. Forbes calculated that price at just over seven times earnings and called it cheap. Architect founder James Sagan needed to raise $2 billion of equity from venture funds, buyout funds and family offices, plus $2 billion of debt, and the deal was meant to close by the end of March.
Then Architect wrote to its potential investors with an update. The deadline had slipped by months, and the debt was no longer needed, because OnlyFans itself would help finance the purchase through a seller’s note paying Radvinsky 7.5% a year.
Read that structure again. The seller was going to lend the buyer the money to buy his own company, because no bank, syndicate or credit fund would write the paper on ordinary terms. Even the exit had to reach him as a coupon from the same business.
Investors then learned that Radvinsky had terminal cancer, and that his health was driving both the sale and its speed. He died in March. On May 8, Fenix announced that Architect had bought about 16% for $535 million, valuing the company at $3.15 billion, financed through a special purpose vehicle backed by Australian billionaire James Packer and Slow Ventures partner Sam Lessin. The board voted for it unanimously. Chief executive Keily Blair stays. The family trust keeps control.
The ask fell from $8 billion to $3.15 billion in twelve months. Over the same twelve months, revenue grew 10% and pre-tax profit grew 5%. The business improved while the price fell by more than half.
The Plan
Architect’s stated purpose is financial plumbing. The firm will help OnlyFans build banking and payment products for creators who, in the company’s phrasing, are underserved by traditional financial institutions. Sagan has told investors he wants to increase the stake over time and has argued there is no regulatory obstacle to a US listing, adding that he has found institutions receptive to the idea. Reports have put an IPO target around 2028.
That plan is the direct answer to the discount. If the reason nobody would pay eight times earnings is that banks, card networks, app stores and index funds treat the platform as untouchable, then the way to fix the multiple is to own the rails rather than rent them. Architect is buying the constraint and proposing to remove it.
Now price the stake. Architect paid $535 million for roughly 16%. Fenix declared $535 million of dividends in FY2025. A 16% holder with a pro-rata claim on that stream would have collected about $86 million, a 16% cash yield on the purchase price in year one. Use the trailing sixteen-month run rate of $709 million instead and the claim rises to about $113 million, or 21%.
Those are private credit returns on an equity position. Architect built its business lending to companies the banks skip, and it has now bought one on terms that look like a loan with equity upside stapled on. The caveat matters: the filing signals no further dividend for the current period, so the yield is a look-back rather than a promise, and a company preparing for an IPO usually stops emptying its own balance sheet.
The Business Model Angle
Three things make this company an outlier, and only one of them is the one everyone quotes.
The headcount number describes a legal boundary. Net revenue per employee runs about $33 million, and gross payments per employee run about $165 million. No company on any public exchange is close. But the 1,500 outside moderators are 32 times the payroll, and they perform the function that carries the legal risk. Fenix drew the edge of the legal entity so that the labor sits outside it. The productivity statistic is an artifact of where that line was drawn.
Nothing on the income statement is a real cost of goods. OnlyFans commissions no content, holds no inventory, pays no advances, signs no exclusives, and buys no rights. Creators arrive with their own audiences, which means the platform also skips the demand-generation cost that Netflix, Spotify and YouTube all carry. The 20% take rate applies to distribution the platform does not perform. Compare it to Patreon, which runs a similar structure at an 8% to 12% blended rate. OnlyFans charges roughly double, and creators pay it, because the alternative is not another platform. It is no payment processor at all.
With nothing to reinvest in, the money leaves. Look at what happened the one time Fenix tried to hold capital rather than distribute it. Between 2021 and 2022 the company put $19.89 million of working capital into Ethereum, disclosed under intangible asset purchases. By the November 2022 year end the holding was worth $11.4 million, and Fenix booked an impairment of $8.46 million. A business with no capex requirement, no acquisition pipeline and no product roadmap that needs funding parked its surplus in ETH, lost 42% of it, and went back to writing dividend checks.
Put those together and the payout policy stops looking like a choice. A company that cannot deploy capital internally, cannot be sold at a normal multiple, and cannot borrow against itself on ordinary terms has one route for turning profit into wealth. Pay it out, every year, in full.
The valuation confirms the reading. At $3.15 billion, Fenix trades at about 6.0 times post-tax profit, 4.4 times pre-tax profit and 2.0 times net revenue. A subscription marketplace growing 10% with a 46% pre-tax margin in an ordinary category would clear 15 to 25 times earnings without an argument. The gap between those two numbers is the price of a restricted buyer pool, and it has been sitting in the filings since 2021.
Airtable sold to Bending Spoons at 2.7 times revenue this month, and we argued that the SaaSpocalypse is an ownership transfer rather than a demand collapse. OnlyFans is the same trade run in reverse. Airtable’s price fell because its growth broke. OnlyFans grew the whole way through and Radvinsky still could not find a bidder, because the constraint sat outside the operation.
The Risk
The regulatory exposure is priced into everything above.
Ofcom fined Fenix £1.05 million in March 2025 for submitting inaccurate age-verification data over two years, and noted in its decision that the company is large, well resourced and aware of its obligations. Under the Online Safety Act, penalties can reach 10% of qualifying worldwide revenue or £18 million, whichever is greater. On a $1.55 billion revenue base that ceiling is around $155 million. Whether the regulator would apply the percentage to net revenue or to the $7.75 billion of gross payments is not a question the company wants tested.
The pressure is also moving up the stack, away from websites and toward the money. Germany changed its rules in December 2025 so authorities can require banks and payment providers to stop processing for non-compliant adult platforms. Mastercard’s AN 5196 program requires performer identity and age documentation. The US Supreme Court declined to block Texas’s App Store Accountability Act on July 6, 2026, and roughly 25 states now enforce age-verification laws. OnlyFans reversed its own adult-content ban within days in 2021 after processor pressure, so this failure mode has already happened once.
Two counterarguments deserve a hearing.
The first: the low multiple might be correct rather than unfair. Growth has decelerated from pandemic-era rates to 10%, creator accounts and fan accounts are maturing, and a business whose supply side can migrate to Fansly or a self-hosted stack has thinner defenses than its margins suggest. Buyers who passed at $8 billion were not all squeamish. Some of them ran the numbers.
The second: Sagan may be right. If Architect builds creator banking that works, gets an audit and a listing venue, and drags the company through a US IPO by 2028, then $3.15 billion was the floor rather than the ceiling, and the family trust sold 16% at the worst possible moment. That is the falsifier for this piece. Watch for a named auditor, a US listing venue and a resumed dividend. If all three arrive, the discount was temporary and the extraction strategy will look like a failure of nerve rather than a correct reading of the market.
Quick Questions
Did OnlyFans pay out more than it earned? In FY2025, yes. Fenix declared $535 million of dividends against post-tax profit above $521 million, a payout ratio near 103%. Add the $174 million paid between December 2025 and March 2026 and total declared distributions reach $709 million.
How much did Radvinsky take out in total? Disclosed annual dividends from 2021 through March 2026 total about $2.3 billion. Forbes puts the figure closer to $2.5 billion once between-year tranches are included. He bought control in 2018.
Why is OnlyFans worth only $3.15 billion? Because the pool of buyers is small. Payment networks, banks, app stores, advertisers and index funds all treat adult platforms as high risk, so the auction has few bidders and the winner sets the price. At $3.15 billion the company trades at about six times post-tax profit while comparable subscription businesses clear 15 to 25 times.
How does OnlyFans make money? It takes 20% of everything a creator earns through subscriptions, tips, pay-per-view content and paid messages. Creators keep 80%. Our full breakdown of the OnlyFans business model covers the structure in detail.
Who runs the company now? A family trust headed by Radvinsky’s widow, Yekaterina Chudnovsky, holds control. Keily Blair remains chief executive. Architect Capital owns about 16% and has said it wants more.
Does 47 employees mean OnlyFans is the most efficient company in the world? Only on paper. Fenix also contracts around 1,500 outside content moderators, which is 32 times its payroll. The headcount figure describes the legal entity rather than the operation.
The Business Model Analyst Take
Every founder is told that the exit is the payoff. Build the asset, hold the equity, sell once, retire. Radvinsky ran the opposite play, and the filings suggest he ran it on purpose.
He bought OnlyFans in 2018, took no salary story to the press, built no war chest, made no acquisitions, and shipped no expensive product line. He paid himself the profit. Every year, all of it, rising from $284 million to $535 million. When he tried to convert the asset into a single number in 2025, the market told him what it thought: an $8 billion ask, no takers, and eventually a minority sale at $3.15 billion with the seller offering to finance the buyer.
The dividends were worth more than the exit ever would have been. Roughly three quarters of the company’s eventual price came out in cash while he still owned every share.
The lesson generalizes past adult content. If you run a business the capital markets will not underwrite, at any size and in any category, then retained earnings are trapped capital and reinvestment is a bet you cannot cash. Founders in gambling, firearms, cannabis, debt collection, vape and crypto infrastructure all face a version of this. The correct financial policy in that position looks reckless from the outside and is the only rational one from the inside: distribute aggressively, keep the balance sheet thin, and treat the terminal value as a bonus rather than a plan.
Architect Capital is betting the constraint is removable. It bought 16% at a price that yields like private credit, and it wants to spend the next two years making OnlyFans bankable enough to list. If that works, the company will be worth several times what the trust just sold at, and the dividend will stop, because a public company reinvests.
Radvinsky did not live long enough to find out whether the discount was permanent. He also did not need to. He had already taken the money.