
Anthropic and Blackstone have put a name and a price tag on a bet that should make every founder rethink where AI value actually lives. The bet is not on a smarter model. It is on the people who install one.
That bet is called Ode with Anthropic, a $1.5 billion AI implementation company launched as a joint venture between Anthropic, Blackstone, Hellman & Friedman, Goldman Sachs, and others. Its founders think it can become a trillion-dollar business. The interesting part is not the ambition. It is what the move quietly admits about the state of the AI model race.
What Ode actually is
Ode is an AI services firm. It sends elite engineers into large companies to figure out where AI can rewire a core process or product, then builds the custom system to make it happen. Think of it as a “scaled boutique,” a consultancy that wants the polish of a small shop and the reach of a giant.
The company currently runs about 100 engineers and works hand in hand with Anthropic’s applied AI team. Anthropic’s own internal team stays focused on strategic, mission-aligned deployments, so Ode is the commercial arm that goes wide.
CEO Chris Taylor did not undersell it. He told TechCrunch it is “pretty easy to imagine this as a trillion-dollar company someday if we execute well.” He also named the catch in the same breath: how do you grow that fast without the quality falling apart?
Why Blackstone built it in the first place
Ode did not start as an Anthropic idea. It started as a Blackstone problem.
When Blackstone tried to roll AI across the companies it owns, it hired big consulting firms and small AI boutiques to do the work. One of those boutiques, an AI engineering startup called Fractional AI, stood out. So the joint venture simply bought it. Fractional walked away from an 11-month partnership with OpenAI on its way out the door, and it now forms the technical core of Ode.
That origin story matters. This was not a lab dreaming up a services arm. It was a private equity giant discovering that the hard part of AI is not access to a model. It is getting the model to do something useful inside a real business.
The real bet: implementation is the moat
Here is the thesis stated plainly by Ode’s chief technologist, Eddie Siegel: model choice matters, but it is not where the effort goes. He compared picking a model to picking a programming language. Nobody defines a company’s transformation by whether the team wrote it in Python or Java.
Read that as a signal, not just a soundbite. When a company partly owned by Anthropic says the model is just one ingredient, it is telling you the model itself is becoming a commodity. The margin, the lock-in, and the defensibility are moving up the stack into implementation.
This is a classic strategy move: when your core product is at risk of commoditizing, you go capture the layer next to it. AI labs are watching model performance converge and prices fall. Services is where the stickiness lives.
“Claude-first” is the real tell
Ode runs on a “Claude-first” principle. Wherever possible, it installs Anthropic’s tech, including features like Claude’s shared assistant inside Slack. It can use rival models when a job demands it, but the default is Claude.
That is the quiet genius of the whole structure. Every deployment embeds Claude deeper into a customer’s most important workflows. Once Claude is running the process a CEO cares about most, swapping it out for a competitor’s model becomes a nightmare of re-engineering, not a casual switch. The services revenue is almost the secondary prize. The primary prize is a distribution channel that turns model wins into permanent ones.
It rhymes with Anthropic’s other recent moves, from putting its knowledge-work agent on every phone to embedding assistants where employees already work. Different products, same playbook: get inside the building and stay there.
The deployment land grab is already crowded
Ode is not entering an empty field. It is walking into a brawl.
OpenAI built its own version, called The Deployment Company. Microsoft committed a staggering $2.5 billion and 6,000 engineers to its enterprise deployment unit, Frontier Company. Consulting incumbents Deloitte and Accenture have each spun up their own forward-deployed engineering practices. Everyone has decided at once that embedding engineers inside customers is the next big thing.
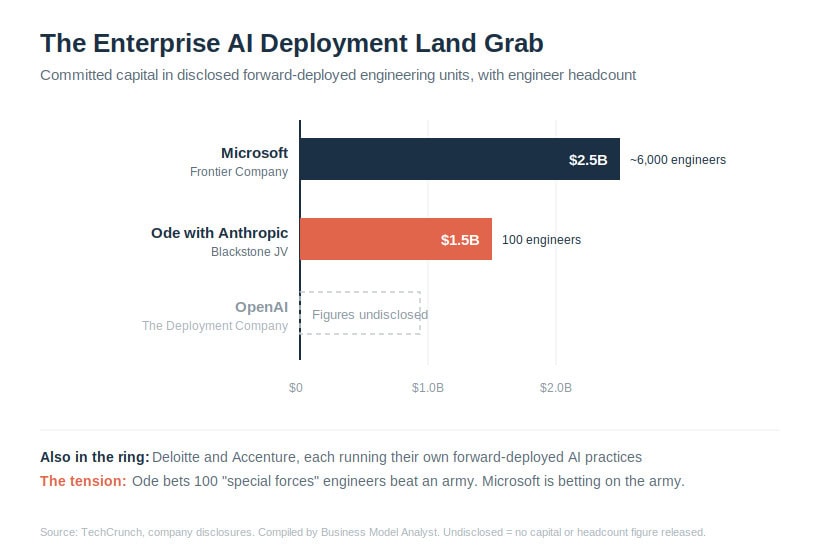
The two disclosed war chests tell the strategy in one glance. Microsoft is buying scale. Ode is buying selectivity.
Special forces versus the army
The chart hides the sharpest question in the whole story. Microsoft is fielding 6,000 engineers. Ode has 100.
Ode’s leaders are proud of that gap. They describe their people as elite generalists, over half of them former founders, the kind who can wrestle a hard technical problem and own a project end to end. One Blackstone executive called them “grown-up” engineers, “special forces” rather than an army.
That positioning is a genuine strength and a genuine trap. The strength: quality and trust with a CEO who is betting a top priority on the work. The trap: this talent does not scale like software. If your ideal hire needs founder scars, systems thinking, AI skill, and enterprise judgment all at once, you cannot mint them fast. Demand for these teams already outstrips supply, by the venture’s own admission.
The trillion-dollar number deserves a hard look
Here is where a skeptic should push back. Services companies do not get software valuations, and for good reason.
Accenture, the benchmark for this kind of work, employs roughly 780,000 people and pulls in about $70 billion a year. Its market value sits well under $100 billion. Ode wants to reach a trillion with 100 engineers and a boutique-quality promise. The only routes there are to hire a massive army, which kills the special-forces quality it is selling, or to productize the work into something that scales without bodies, which nobody at Ode has actually described yet.
That is not a small gap in the story. It is the entire business. The CEO admitted the core challenge is surviving hypergrowth without losing quality, and right now that is a hope, not a plan.
Who wins if the bet is right
Strip away the trillion-dollar talk and there is a claim worth taking seriously: the biggest winners of the AI era may be old, non-AI companies that adopt the technology well.
That is a refreshing counter to the “AI-native startup eats everything” narrative. A boring logistics firm or regional bank with deep proprietary data and real customer relationships could get more value from rewiring one core process with AI than a dozen thin AI wrappers ever will. The bottleneck is talent those companies do not have in house. Ode is selling exactly that talent. If it is right about the winners, the demand is real even if the trillion-dollar dream is not.
What to watch next
Three signals will tell you whether Ode is a real business or a well-funded press release.
First, watch for customers outside the private equity family. The backers will funnel their own portfolio companies in as early clients, so early “traction” is partly captive. Open-market logos are the real test.
Second, watch the headcount-to-quality math. If Ode scales past a few hundred engineers while keeping its results sharp, it has cracked something hard. If quality slips, it becomes just another consultancy with a fancier logo.
Third, watch whether the “Claude-first” default holds as customers demand model flexibility. That default is the whole moat. If it erodes, Ode is a services firm, not a strategic weapon.
The Business Model Analyst Take
The headline says “implementation, not models,” but that framing undersells what is happening. This is not Anthropic discovering that services are lucrative. It is Anthropic building a moat around a product it fears is commoditizing.
The model is becoming the easy part. Everyone can rent a frontier model, and they are all converging on similar performance at falling prices. What cannot be copied cheaply is a team embedded inside your most important process, and a switching cost that grows every month they stay. That is what Ode is really selling, and it fits neatly with Anthropic’s larger pattern of turning capability into permanence, the same instinct behind its infrastructure-heavy $965 billion raise and its climb past OpenAI on enterprise share.
For founders, the lesson is bigger than one joint venture. When the leaders of a category start giving away the thing everyone fights over, in this case the model, and racing to own the thing next to it, in this case the implementation, that is your signal about where the durable money actually sits. It is rarely in the shiny object. It is in the boring, sticky layer wrapped around it.
The trillion-dollar tag is marketing. The strategic read underneath it is not. Watch the moat, not the model.