
The $500 billion headline buried the phrase that explains the whole structure, and Nvidia printed it in its own press release subhead.
Nvidia will cover up to 25% of the residual value shortfall on chips pledged as collateral in the new compute financing platforms. Read as a concession, that number looks like a vendor propping up its own resale market. Read against the press release subhead, which promises long-duration usage-linked revenue alongside hardware sales, the 25% works as a purchase price. Nvidia paid a slice of the downside to install a meter on hardware it has already sold once.
Jensen Huang spent Tuesday explaining a number he had not put in Monday’s announcement. The stock had dropped about 3%. The five-year credit default swap spread on Nvidia’s own debt sat near 80 basis points, more than double where it traded in late May. So he published an essay on X and the company blog, took the question head on, and disclosed the cap. Bond desks stopped selling. Almost nobody read the sentence Nvidia had already written above the fold.
What Happened
On August 10, Nvidia signed memorandums of understanding with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to build compute financing platforms targeting more than $500 billion of third-party capital. Debt gets raised through special purpose entities. The collateral is the compute itself.
The announcement said nothing about what Nvidia would guarantee. Credit investors noticed. The next day Huang published a piece titled around AI factory compute becoming an investable asset class, and answered the circular financing charge directly. In some cases, he wrote, Nvidia may provide a residual value support mechanism for “up to 25% of an opportunity”, assessed project by project. He framed the support as limited, tied to residual value, and designed to sit alongside the lenders’ own underwriting rather than substitute for it. He also noted the share runs below other compute financing arrangements.
That last line is defensible and awkward at the same time. Meta gave the Hyperion joint venture a residual value guarantee covering the first sixteen years, which is what carried that paper to an S&P A+ rating. Broadcom’s AI XPV structure reportedly covers 100% of any shortfall to the senior tranches, dragging them near Broadcom’s own investment grade rating without touching Broadcom’s balance sheet. Nvidia offered a quarter, capped, case by case. Huang described the gap as discipline. A credit committee reads the same sentence as a smaller cushion.
The Backstory
We wrote on Monday that the missing residual guarantee was the story, and that Nvidia faced a fork: put the guarantee in writing and turn $500 billion into a contingent liability, or refuse and watch the senior paper price wide of investment grade. Nvidia answered inside twenty-four hours, and answered partway. Our Monday analysis of the $500 billion compute financing structure laid out both paths.
The credit market had been pricing this since July. Nvidia’s five-year CDS spread traded near 42 basis points in late June, jumped to 57.3 in mid-July on reports of roughly $750 billion in hyperscaler data center spending, then hit 82 on July 27 after Bloomberg tallied about $750 billion of circular deals across Nvidia’s summer. It peaked at 83.7 on July 29. Monday’s announcement left it at 79.8. After Huang clarified, it settled near 72.
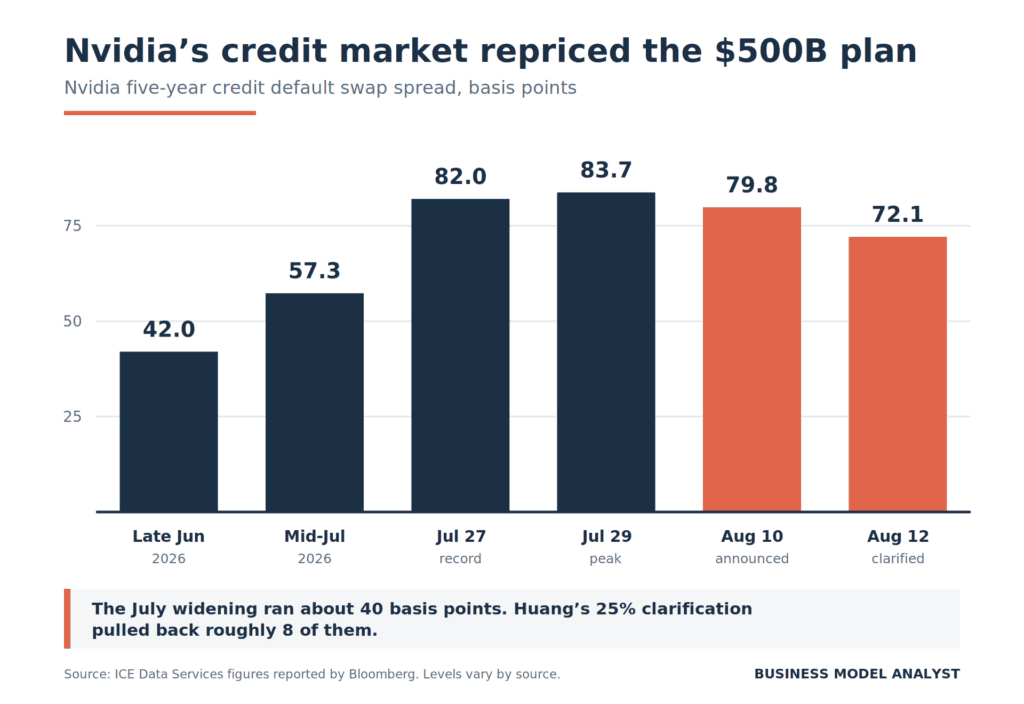
Eight basis points back out of a forty basis point move. Credit investors believed the cap and kept most of their repricing. For scale, S&P cut Oracle to BBB- this summer and Oracle’s five-year protection trades around 215 basis points, so Nvidia remains in a different league. The direction still matters more than the level.
The Plan
Nvidia titled the release with a subhead most coverage skipped. It says the platforms turn Nvidia compute into an investable asset class, broaden access to AI factories, and enable “Long-Duration Usage-Linked Revenue” while supporting ecosystem growth across hardware sales and software adoption.
Usage-linked revenue is a royalty. Nvidia sells the rack once at roughly 75% gross margin, then takes a cut of what the rack earns for the rest of its working life.
The mechanic already shipped. On July 1, Nvidia launched a revenue-sharing AI cloud program with Sharon AI and Firmus committing 210,000 Grace Blackwell GPUs, where Nvidia collects hardware revenue plus a usage-linked royalty on the same capacity. The financing platforms scale that arrangement and hand the capital raising to six firms managing several trillion dollars between them.
Morgan Stanley ran the numbers and liked what it found. Assuming Nvidia captures 35% of the surplus from GPU usage revenue, rental prices hold near $13 per hour, and the world adds 5 gigawatts of capacity a year, the bank models roughly $51 billion of potential new annual revenue at gross margins approaching 100%, worth about a 9.83% lift to fiscal 2029 earnings per share. Those assumptions carry a lot of weight and none of them are contracted. The shape of the bet is what counts.
The Business Model Angle
Huang built his residual value defense on rental prices, and he published the series himself. One-year H100 contracts moved from about $1.70 per GPU-hour in October 2025 to about $2.35 by March 2026. Cross-provider on-demand median pricing went from roughly $2.00 to $2.70 between October 2025 and June 2026. Blackwell B200 capacity commands somewhere between $5.30 and $7.05 per GPU-hour. He also pointed at the A100, introduced in 2020 and still booking multi-year commitments six years later, with an economic life stretching toward a decade.
Rising rents on a four-year-old part measure scarcity. Buyers pay $2.70 an hour for H100 time because they cannot get Blackwell, not because the H100 improved. The entire purpose of mobilizing $500 billion is to build enough capacity that the shortage ends. Nvidia is underwriting collateral against a price series the financing exists to flatten, and it has now attached a royalty to the same series.
That leaves a business model question worth more than the 25% argument. Nvidia’s revenue today is capex-shaped: lumpy, tied to buyer budget cycles, and priced by the market at a hardware multiple even as Nvidia’s business model has drifted toward platform economics. Usage-linked revenue is opex-shaped: recurring, tied to utilization rather than procurement, and priced at a software multiple. A vendor that converts even a fraction of its installed base into a metered stream gets a different valuation and a different downside profile.
The 25% is the entry fee. Nvidia posted a partial residual backstop, and in exchange the six largest infrastructure allocators agreed to fund a structure that routes usage economics back to Nvidia for the asset’s whole life. Every gigawatt those platforms finance becomes a chip sale today and a toll tomorrow. That framing also explains why Huang keeps arguing the A100 case: an old chip that still earns rent still pays Nvidia. The margin migration argument we made in AI bubble margin migration points the same direction. Whoever owns the constrained input collects the rent, and Nvidia is writing the lease.
The Risk
The correlation problem is worse than the version circulating this week. Analysts describe wrong-way risk: Nvidia’s obligations grow as AI demand weakens, exactly when its revenue is falling. True, and incomplete. Stack the exposures.
In a downturn, GPU rental rates fall, which shrinks the royalty. Residual values fall, which triggers the backstop. Chip orders fall, which cuts the hardware line. Three revenue and liability streams keyed to one variable, and Nvidia now sits on all three.
Nobody has published terms. No rate, no tenor, no first-loss position, no definition of how the residual gets marked. Huang called the support supplementary, which implies Nvidia does not absorb the first loss, and the MOUs are subject to execution of final agreements. Until the contracts surface, the 25% is a stated intent.
Michael Burry called the arrangement a “sign of desperation”. Hedgeye’s Felix Wang offered a sharper read: the backstop makes Nvidia’s product cheaper without cutting the sticker price, and it makes future demand more sensitive to credit conditions. If capital markets tighten, orders now tighten with them.
The honest counterargument runs the other way. Jim Cramer noted that when Goldman bankers pitched auto loan securitization in 1985, skeptics said cars do not last long enough, and auto-backed paper became one of the largest asset classes in structured credit. American Compute’s June 2026 residual study, built on 76,775 completed secondary-market transactions covering 622,098 units, concluded that datacenter GPU useful life can reach eight years and lenders can book residuals above 10% of equipment cost over five. Nvidia holds 74.9% gross margins and generated $48.6 billion of free cash flow in a single quarter. A company with that balance sheet can absorb a quarter of a residual shortfall on a lot of deals before anyone notices.
Concentration is the quieter risk. The offtakers who will populate these platforms are the same frontier labs and neoclouds already carrying enormous compute commitments, which is the pattern we flagged when AMD’s record quarter met the wrong customer. Diversification across six lenders does not diversify the demand side.
Quick Questions
Is Nvidia putting $500 billion of its own money at risk? No. The $500 billion is third-party capital the six firms aim to mobilize over time. Nvidia’s stated exposure is the residual support, capped at 25% of a given opportunity and assessed deal by deal.
What does 25% cover? If a borrower defaults and the lender liquidates the chips for less than the book value assumed at financing, Nvidia covers part of that gap. The cap is a share of the opportunity, not a floor under the whole loan.
Why did the stock and the bonds react differently? Equity investors read a bigger addressable market. Credit investors read a new contingent liability on a balance sheet that has never carried one at this scale. The CDS spread moved before the announcement and only partly retraced after it.
Is this Lucent again? The structures differ. Lucent lent its own money and booked the receivables. Nvidia is signing MOUs with allocators deploying client capital and offering a capped residual backstop. The similarity is that both vendors made their own demand easier to finance. Whether that ends the same way depends on whether AI workloads generate revenue, which telecom’s dark fiber never did.
When do we find out if this works? Watch for the first executed platform agreement and its disclosed terms, and watch Nvidia’s second-quarter report in late August for any commentary on usage-linked revenue as a reported line.
The Business Model Analyst Take
Every commentator this week priced the 25% as a cost. Burry called it desperation, deVere asked why a confident seller underwrites its own customers’ financing, and the credit market charged Nvidia thirty extra basis points for the privilege. All of that assumes Nvidia gave something up.
Nvidia bought something. It put a capped residual backstop on the table and walked away with six of the world’s largest infrastructure allocators committed to funding a structure that meters Nvidia’s installed base for the life of the asset. The company that has spent three years selling shovels wants a percentage of the gold.
Whether that trade works turns on one number nobody has published: what fraction of usage revenue Nvidia captures, and for how long. Morgan Stanley guessed 35%. If the real figure lands there and the platforms scale, Nvidia converts a cyclical hardware business into an annuity and earns a different multiple for it. If the figure lands at 5%, Nvidia wrote a put on its own product cycle and got a rounding error back.
The 25% is the price tag. Watch for the receipt.