
Ilya Sutskever’s lab spent two years selling nothing to nobody. Its first real transaction was not compute for cash. It was secrecy for silicon.
Nvidia committed a reported $5 billion to Safe Superintelligence and handed it access to the Vera Rubin platform, raising SSI’s compute by roughly tenfold. The strange part sits in Nvidia’s own press release: the chipmaker signed only after gaining rare access to SSI’s guarded research.
Sutskever built Safe Superintelligence around a refusal. No products, no API, no revenue, no interim releases to keep investors warm. One goal, one product, arriving whenever it arrives. That refusal was the pitch, and investors handed over billions on the strength of it. Two years later the lab needed something money alone could not buy at the scale it wanted, and it paid with the only other asset on the balance sheet.
What Happened
Nvidia and SSI announced a long-term partnership on July 27, 2026, pairing an equity investment with access to Nvidia’s next-generation Vera Rubin systems. Neither company disclosed the size. Bloomberg put it at $5 billion, and TechCrunch reported that the figure stretches into multiple billions, citing a source familiar with the deal.
The compute number is the headline everyone will run with. SSI says the Vera Rubin allocation lifts its available compute by an order of magnitude. Sutskever framed it in one sentence: the lab has research worth scaling, and a big Nvidia computer lets it scale.
Read the Nvidia statement one paragraph further and the transaction changes shape. Nvidia says it entered the partnership after obtaining rare access into SSI’s closely guarded research. It also says the two companies will collaborate on advancing Nvidia’s current and future compute platforms, drawing on SSI’s insights into where AI is heading.
That second clause is a supply agreement running in reverse. Nvidia sells SSI chips and SSI sells Nvidia a view of what chips to build.
The Backstory
Sutskever co-created AlexNet with Alex Krizhevsky and Geoffrey Hinton, the 2012 result that proved GPU scaling plus deep neural networks worked. He then spent nearly a decade as OpenAI’s chief scientist, ran the Superalignment team, and left in 2024 after the failed attempt to remove Sam Altman.
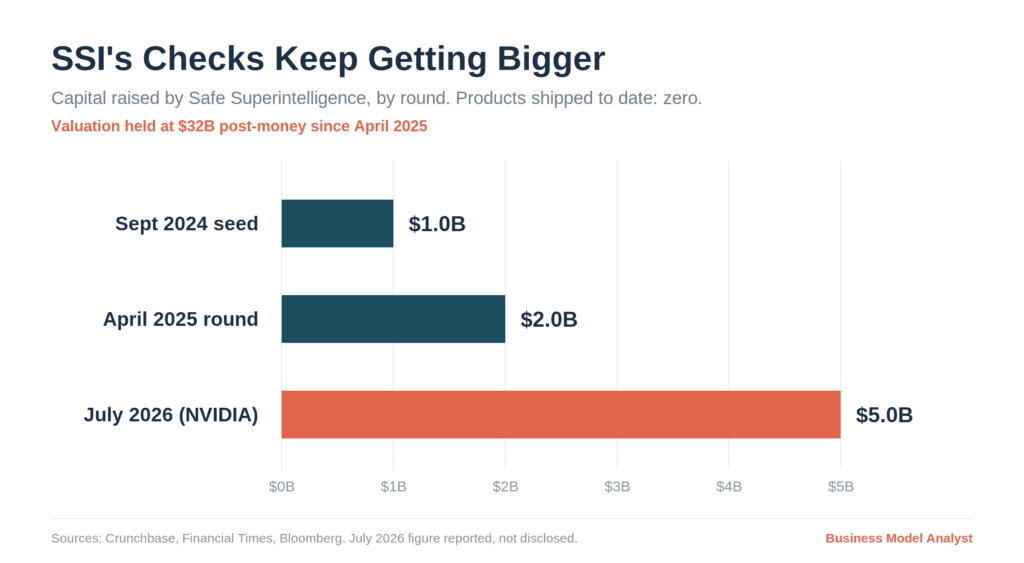
He incorporated SSI in June 2024 with Daniel Gross and Daniel Levy. Three months later the company raised $1 billion at roughly a $5 billion valuation from Andreessen Horowitz, Sequoia, DST Global, and SV Angel, with no product and barely a website. In April 2025 it raised about $2 billion more at $32 billion post-money, led by Greenoaks with a reported $500 million check. Alphabet and Nvidia both came in as strategic investors on that round, and Google Cloud became SSI’s primary compute supplier through a TPU allocation.
One accounting detail deserves attention. Publicly announced rounds total roughly $3 billion, but PitchBook puts SSI’s lifetime raise at $7 billion. Several billion dollars entered this company without a press release. A lab that guards its research this tightly guards its cap table the same way.
The Plan
SSI calls itself a straight-shot lab. No intermediate products, no revenue milestones, no commercial distractions between now and a safe superintelligence. Gross left for Meta in 2025 and Sutskever took the CEO seat, and the charter did not move.
Financially that structure works like a clinical-stage biotech rather than a software company. You raise against a binary outcome, burn the capital on research, and generate zero revenue until the one asset either works or does not. Biotech investors understand this shape. They price it with milestone-based tranches, and they accept that most bets return nothing.
The awkward part for SSI is that its burn is compute, and compute is not getting cheaper for a lab that wants ten times more of it. Google TPUs covered the first phase. Vera Rubin covers the next. Both suppliers now sit on the cap table.
The Business Model Angle
Ask what SSI actually had to trade and the deal explains itself. No revenue means no cash. No product means no distribution to offer a partner. No published papers means no reputational currency in the usual academic sense. The lab holds equity and it holds information, and Nvidia took some of each.
Now flip to Nvidia’s side, because that is where this gets interesting for anyone studying the Nvidia business model.
Nvidia’s hardest strategic problem is not demand. Demand is spectacular, with data center revenue at $75.2 billion in a single quarter. The problem is that Nvidia’s largest customers are also its most motivated competitors. Google runs TPUs. Amazon runs Trainium. Meta builds MTIA. OpenAI has a custom accelerator program with Broadcom. Every one of those labs sees Nvidia’s roadmap, and every one of them has a team working on how to need less of it.
SSI is the exception. A lab whose charter forbids shipping commercial products will never sell a chip, never sell a cloud instance, never sell an API that competes with a Nvidia customer. It is the only frontier research operation on the board that can look at the Vera Rubin roadmap with no incentive to route around it.
Nvidia bought the last neutral research partner in the industry, and it paid roughly 6.6% of one quarter’s data center revenue for the position. Against the $100 billion committed to OpenAI in 2025, this is a rounding error with an option attached.
The Risk
Three things make this uncomfortable, and one of them cuts against the case above.
Secrecy was a product feature at SSI, not a habit. Sutskever’s argument for the straight-shot structure rests on insulating research from commercial pressure and competitive leakage. Selling a window into that research to a company with commercial relationships across every rival lab puts a hole in the wall. Nvidia will say the information is firewalled. Firewalls at Nvidia protect Nvidia.
Concentration is the second problem. SSI’s compute now comes from Google and Nvidia, and both hold equity. When your suppliers are your shareholders, the negotiation over next year’s allocation is not an arm’s length transaction. OpenAI has spent 2026 discovering what happens when compute commitments outrun revenue, a dynamic covered in our piece on OpenAI spending like a utility while priced like software. SSI has no revenue at all.
The strongest counterargument runs the other way. Corporate venture arms buy technical intelligence all the time, and a chip company that gets an early read on what frontier training runs will demand in 2028 can save billions in architecture mistakes. Jensen Huang has been explicit that Nvidia sells the whole AI factory rather than the chip, a strategy visible in how the company set warm-water cooling as the Rubin default. Buying a research feed to inform that stack is boring corporate strategy, not a governance scandal.
Both readings can be true. The question is whether SSI’s differentiation survives contact with a shareholder that talks to everyone.
Quick Questions
Does SSI have any revenue? None. The company has never shipped a commercial product and says it will not until it reaches a safe superintelligence.
How much has SSI raised? Public rounds total about $3 billion, plus the reported $5 billion from Nvidia. PitchBook lists lifetime funding at $7 billion, which implies several billion raised without announcement.
What is Vera Rubin? Nvidia’s next-generation compute platform, successor to Blackwell. SSI says access to it multiplies its compute by roughly ten.
Why would Nvidia invest in a company with no product? Two reasons. SSI spends its money on Nvidia hardware, and the agreement gives Nvidia research input into future chip design from a lab that will never compete with it.
Is this circular financing? Partly, in the same way the OpenAI arrangement is. The distinguishing feature here is the information flowing back to Nvidia, which the cash-and-chips framing misses.
The Business Model Analyst Take
Founders reading this should take one lesson from Sutskever, and it is not about superintelligence.
When you have no revenue and no product, you still hold assets. Your data, your research, your customer insight, and your visibility into where a market is heading all have buyers, and those buyers are often your suppliers. SSI converted proprietary knowledge into a compute allocation worth more than its entire seed round. That trade is available to companies far smaller than a $32 billion lab, and most founders never think to make it.
The catch is that you can only sell that access once. Information does not come back. Sutskever built a company whose entire moat was the gap between what he knows and what the rest of the field knows, and he has now narrowed that gap by choice, in exchange for the compute to widen it again. That bet works if the research on the other side of ten times more compute is far enough ahead to justify the disclosure.
Watch what SSI does at its next raise. A lab that sold research access for hardware in 2026 has established a price for the thing it said it would never trade. Buyers remember prices.